Last updated: November 3, 2026 · Originally published: October 28, 2026 · By Alex Petrov
My colleague bought a $185,000 rental property inside his self-directed IRA real estate account in 2019. Seven years later, that property has appreciated to $265,000, collected $126,000 in total rent, and he has paid zero income tax on any of it. When he turns 59½, he can withdraw the gains tax-free (Roth) or tax-deferred (traditional). The same property in a taxable account would have generated $30,000+ in federal and state income taxes over the same period.
Self-directed IRA real estate investing lets you use retirement funds — IRA, Roth IRA, SEP IRA, Solo 401(k) — to buy investment property. The property is owned by the IRA, not by you personally. All income flows back into the IRA tax-free. All expenses are paid from the IRA. The catch: strict rules govern what you can and cannot do with IRA-owned property, and violating them triggers the entire account being treated as a distribution — with taxes and penalties that can exceed the property’s value.
This guide covers how self-directed IRA real estate works, the rules you must follow, how to choose a custodian, and whether this strategy makes sense for your portfolio. Run property numbers with the rental property calculator to see if the deal works inside an IRA structure.
How Self-Directed IRA Real Estate Works
A self-directed IRA (SDIRA) is an IRA held by a specialized custodian that allows alternative investments — including real estate. The custodian holds the legal title to the property on behalf of your IRA. You direct the investment decisions, but the custodian executes transactions, holds funds, and ensures IRS compliance.
The Basic Structure
- You find the property, negotiate the deal, and arrange inspections
- Your IRA custodian signs the purchase contract, wires funds, and holds title
- The IRA owns the property — not you personally. Title reads “ABC Custodian FBO [Your Name] IRA”
- All income goes INTO the IRA. Rent checks are deposited to the IRA account.
- All expenses come OUT of the IRA. Taxes, insurance, repairs, PM fees — all paid from IRA funds.
- You cannot personally benefit. You cannot live in the property, use it as an office, or perform work on it yourself.
Tax Advantages
| IRA Type | Contribution | Growth | Withdrawal |
|---|---|---|---|
| Traditional SDIRA | Tax-deductible | Tax-deferred | Taxed as ordinary income at 59½+ |
| Roth SDIRA | After-tax | Tax-FREE | Tax-FREE at 59½+ (if held 5+ years) |
| SEP IRA | Tax-deductible (up to 25% of income) | Tax-deferred | Taxed at 59½+ |
| Solo 401(k) | Tax-deductible + Roth option | Tax-deferred or free | Depends on contribution type |
The Roth SDIRA is the most effective vehicle: buy a property for $200,000, collect rent and appreciation for 20 years, sell for $400,000 — and pay zero tax on the $200,000 gain plus all the rental income collected over two decades. No depreciation recapture, no capital gains, no income tax. This is why sophisticated investors prioritize Roth conversions before executing self-directed IRA real estate purchases.
The Rules: What You Cannot Do
IRS rules on self-directed IRA real estate are strict. Violations trigger a “prohibited transaction” that disqualifies the entire IRA — meaning the full account balance is treated as a distribution, subject to income tax plus a 10% early withdrawal penalty if you are under 59½. On a $300,000 IRA, that penalty can exceed $100,000.
Prohibited Transactions
- You cannot live in the property — not even one night. No “I will just stay there while visiting.”
- You cannot do repairs yourself. Even if you are a licensed contractor. All work must be hired out and paid from IRA funds.
- You cannot rent to “disqualified persons”: yourself, your spouse, parents, children, grandchildren, or their spouses. You also cannot rent to any entity you own 50%+ of.
- You cannot use IRA property as collateral for a personal loan.
- You cannot mix personal and IRA funds. If the property needs a $5,000 repair and the IRA does not have enough cash, you cannot pay from your personal account. The IRA must have sufficient reserves.
- You cannot receive any indirect benefit — no using the property’s furniture, no storing your belongings there, no using the garage.
What You CAN Do
- Direct all investment decisions (which property to buy, what rent to charge, which PM to hire)
- Hire a property manager (paid from IRA funds) to handle day-to-day operations
- Hire contractors (paid from IRA funds) for repairs and improvements
- Rent to unrelated third parties at market rates
- Sell the property and reinvest proceeds — all within the IRA
How to Buy Real Estate in a Self-Directed IRA: Step by Step
- Choose an SDIRA custodian. Top custodians: Equity Trust, Advanta IRA, IRA Financial Group, Entrust Group. Compare fees — custodians charge $200-$500/year plus transaction fees ($50-$250 per transaction). Some charge asset-based fees (0.15-0.50% of account value).
- Fund the account. Transfer or rollover from existing IRA, 401(k), or other qualified retirement account. Roth conversions are also possible (pay taxes now, grow tax-free). Allow 2-4 weeks for transfers.
- Find a property. Analyze deals with the rental property calculator. Remember: all expenses must be paid from IRA funds, so you need cash reserves inside the IRA beyond the purchase price.
- Submit purchase direction. Tell your custodian to make an offer. They sign the contract “FBO [Your Name] IRA.” You do not sign personally.
- Close through the custodian. The custodian wires funds from your IRA to the closing agent. Title is held by the custodian for your IRA. Budget closing costs from IRA funds.
- Manage through PM. Hire a property manager (paid from IRA). All rent deposits go directly to the IRA custodian account. All expenses are paid from that account.
- Maintain reserves. Keep 6-12 months of expenses in the IRA cash account. You cannot inject personal funds if the IRA runs short. See our cash reserves guide.
SDIRA Real Estate: The Numbers
Here is a real comparison: same $200,000 property, same $1,400/month rent — one owned personally, one inside a Roth SDIRA.
| Metric (10-year hold) | Personal Ownership | Roth SDIRA |
|---|---|---|
| Purchase price | $200,000 | $200,000 |
| Down payment | $50,000 (25%) | $200,000 (100% cash) |
| Total rent collected (10 yr) | $168,000 | $168,000 |
| Annual cash flow (after mortgage) | $3,600/yr | $9,600/yr (no mortgage) |
| Income tax on rent (24% rate) | $40,320 over 10 yr | $0 |
| Appreciation (3.5%/yr) | +$82,000 | +$82,000 |
| Capital gains tax on sale | ~$18,000 | $0 |
| Depreciation recapture tax | ~$12,700 | $0 |
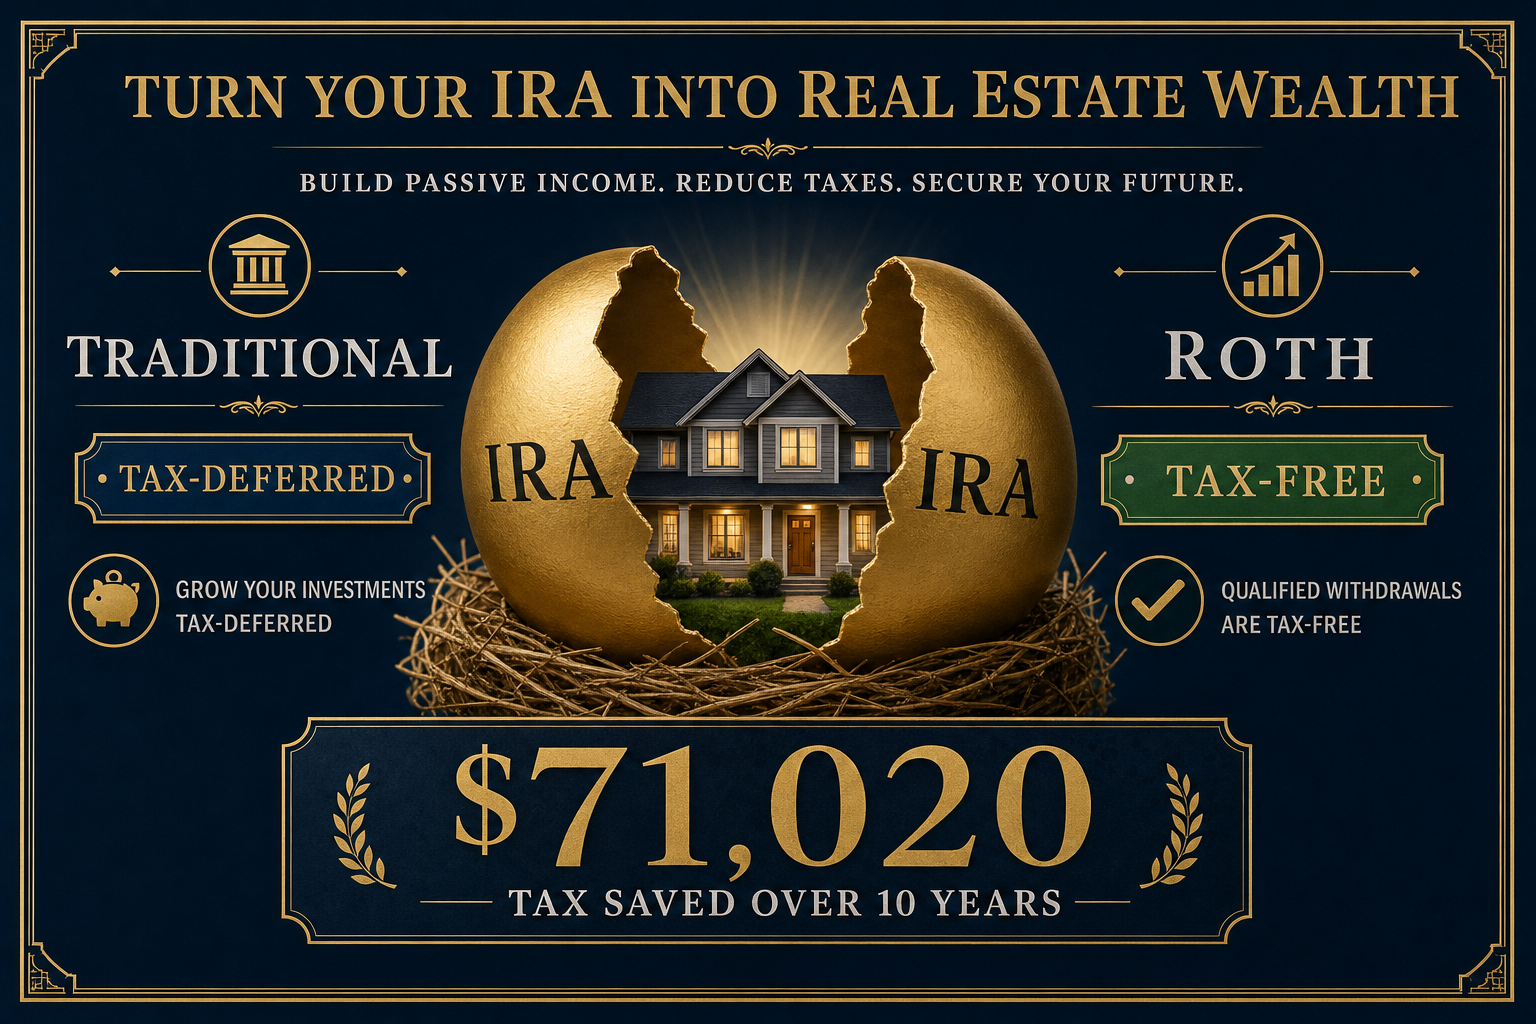
| Total tax paid | $71,020 | $0 |
| Net wealth created | $178,980 | $250,000 |
The Roth SDIRA creates $71,020 more wealth over 10 years — entirely from tax savings. The tradeoff: the SDIRA requires $200,000 cash (no mortgage — see UBIT section below), while personal ownership only needs $50,000 down. If you have $200,000 in retirement funds sitting in index funds earning 8%, the decision comes down to whether real estate inside the IRA outperforms stocks over your holding period. Model both scenarios with the rental property calculator.
UBIT: The Tax Trap on Leveraged IRA Property
If your SDIRA takes a mortgage to buy property (called “acquisition indebtedness”), the portion of income attributable to debt is subject to Unrelated Business Income Tax (UBIT) per IRS UBIT rules. This partially negates the tax advantage.
Example: buy a $200,000 property with $120,000 cash from IRA + $80,000 mortgage. The mortgage is 40% of the purchase price. Approximately 40% of the property’s net income is subject to UBIT at trust tax rates (up to 37%).
Most self-directed IRA real estate investors buy all-cash to avoid UBIT entirely. Solo 401(k) plans have an exception: they can use “non-recourse” loans without triggering UBIT. This makes Solo 401(k) the preferred vehicle for leveraged self-directed IRA real estate purchases.
Best Properties for SDIRA Investing
- All-cash purchases under $250,000. Avoids UBIT, keeps the deal simple. Markets like Indianapolis ($210K), Memphis ($180K), Columbus ($240K) work well.
- Stabilized cash-flowing rentals. The IRA needs income to cover expenses. Value-add and rehab projects are risky because the IRA must fund all repairs from existing cash — you cannot contribute extra mid-project.
- Properties with low maintenance. Newer properties (post-2000) with recent systems (roof, HVAC) minimize surprise expenses that could drain IRA reserves.
- Single-family or small multifamily. Easier to manage, more liquid to sell when you want to exit.
Avoid: heavy rehab projects, properties needing $20,000+ in immediate work (IRA may not have sufficient reserves), and any property where you might be tempted to do work yourself (prohibited transaction). Check property fundamentals with the cap rate calculator and NOI calculator.
How to Choose an SDIRA Custodian
| Custodian | Annual Fee | Transaction Fee | Best For |
|---|---|---|---|
| Equity Trust | $225-$2,250 | $250 | Largest SDIRA custodian, most experience |
| Advanta IRA | $285-$400 | $75-$200 | Lower fees for smaller accounts |
| IRA Financial Group | $360/yr flat | Included | Best for Solo 401(k) with checkbook control |
| Entrust Group | $199-$599 | $95-$250 | Good mid-range option |
Key factors: fee structure (flat vs asset-based), transaction speed (some custodians take 5-10 business days to wire funds — can lose deals), customer service responsiveness, and experience with real estate specifically. Ask how many RE transactions they process monthly.
Common Mistakes in Self-Directed IRA Real Estate
- Doing repairs yourself. Even painting a room is a prohibited transaction. Hire contractors for everything and pay from IRA funds. No exceptions.
- Insufficient IRA reserves. The property needs a $4,000 repair and the IRA has $500 in cash. You cannot contribute personal funds fast enough (annual IRA contribution limits apply). Keep 6-12 months of expenses as cash reserve inside the IRA.
- Renting to family members. Your adult child needs an apartment — your IRA owns a vacant unit. This is a prohibited transaction regardless of whether you charge market rent.
- Using personal credit cards for property expenses. Every expense must come from IRA funds. If you accidentally pay a $200 repair from your personal account, you may have committed a prohibited transaction.
- Forgetting UBIT on leveraged purchases. Taking a mortgage inside an IRA (except Solo 401(k)) triggers UBIT on the debt-financed portion of income. Buy all-cash or use a Solo 401(k) to avoid this.
Frequently Asked Questions
Can I buy rental property with my IRA?
Yes. A self-directed IRA real estate account allows you to purchase rental property, commercial real estate, raw land, and other real property using retirement funds. You need a specialized custodian (not Fidelity/Schwab — they do not allow real estate). The IRA owns the property, collects rent, and pays expenses. All growth is tax-deferred (traditional) or tax-free (Roth).
How much money do I need in my IRA to buy real estate?
Enough to cover the full purchase price (for all-cash buy to avoid UBIT) plus closing costs plus 6-12 months of operating reserves. For a $200,000 property: approximately $220,000-$235,000 total. If your IRA balance is $150,000, you can buy properties in the $120,000-$130,000 range after accounting for closing costs and reserves. Markets like Memphis, Dayton, and Toledo have cash-flowing properties in this range.
Can I use a mortgage inside my IRA?
Traditional and Roth SDIRAs can use non-recourse mortgages (the lender can only claim the property, not other IRA assets). However, the leveraged portion triggers UBIT — partially negating the tax advantage. Solo 401(k) plans are exempt from UBIT on real estate debt, making them the preferred vehicle for leveraged purchases. Non-recourse lenders for IRA purchases charge 1-2% higher rates than conventional mortgages.
What happens if I break the rules?
A prohibited transaction disqualifies the entire IRA. The full account balance (not just the property value) is treated as a distribution in the year the violation occurs. You owe income tax on the full amount plus a 10% early withdrawal penalty if under 59½. On a $300,000 IRA at a 24% tax rate: $72,000 income tax + $30,000 penalty = $102,000. The rules are strict and the consequences are severe — consult a CPA specializing in SDIRAs before purchasing.
The IRS publishes guidance on prohibited transactions in IRC Section 4975. Review this before your first self-directed IRA real estate purchase. The rules have not changed significantly in decades, but enforcement has increased — the IRS now cross-references property records with IRA custodian reports more systematically than in previous years.
Is self-directed IRA real estate worth it?
For investors with $150,000+ in retirement accounts, stable cash-flowing properties, and the discipline to follow IRS rules — yes. The tax savings over a 10-20 year hold are substantial ($50,000-$150,000+ depending on property performance and tax bracket). It is NOT worth it for: investors with small IRA balances (under $100K), anyone who wants hands-on property management, or investors who cannot maintain adequate IRA reserves. The rules are strict enough that one mistake can cost more than the tax savings.
Is SDIRA Real Estate Right for You?
Self-directed IRA real estate is an advanced strategy with sharp edges. The tax savings are real — $50,000-$150,000+ over a 10-20 year hold. But the rules are unforgiving: one prohibited transaction can trigger a six-figure tax bill. This strategy works best for investors who have $150,000+ in retirement accounts they want to deploy into real estate, are disciplined enough to never touch the property personally, and can maintain adequate reserves inside the IRA.
Start by analyzing whether a specific property works inside an IRA structure: run it through the rental property calculator with 100% cash (no mortgage) and zero tax deductions (IRA does not claim depreciation). Compare the after-tax return to keeping the funds in index funds. If real estate wins — and it often does for well-selected properties — find a custodian and begin the process. If the numbers are close, the simplicity of index funds may outweigh the tax advantage given the SDIRA’s management complexity.