Published: September 24, 2026 · By Alex Petrov
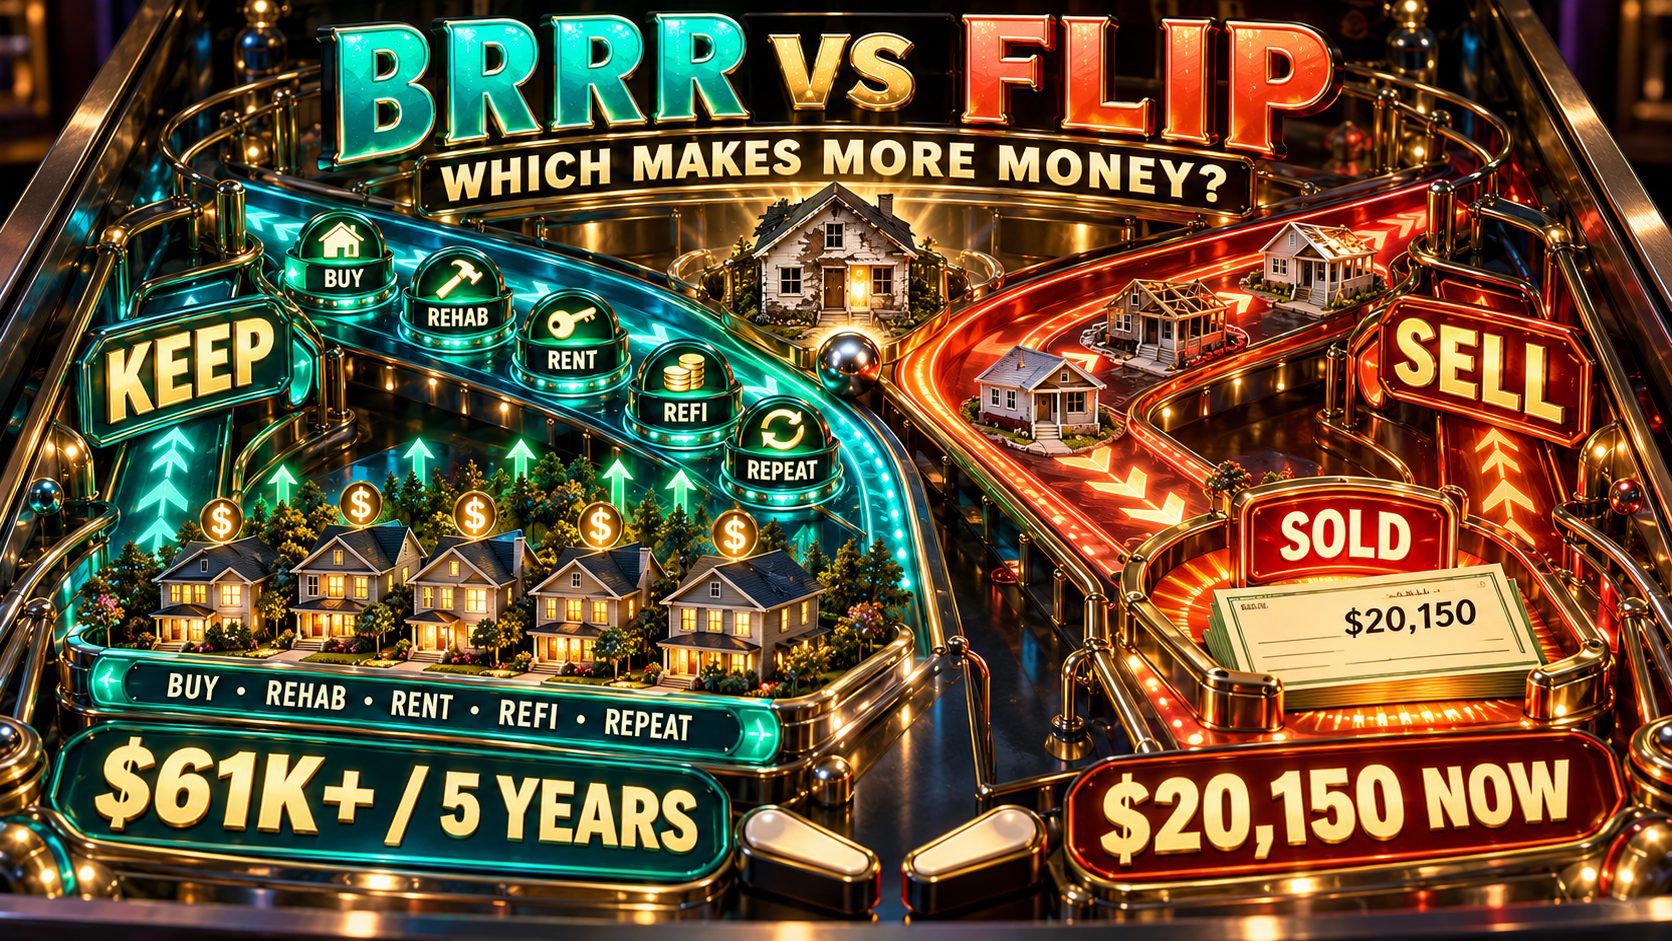
BRRRR vs Flip — The Core Difference
The BRRRR vs flip decision comes down to one question: do you want cash now or wealth later? Both strategies start the same way — you find a distressed property, buy it below market, and fix it up. That’s where the similarity ends.
nnOn This Page
- BRRRR vs Flip — The Core Difference
- How Each Strategy Works
- Worked Example — Same Property, Two Strategies
- When BRRRR Beats Flipping
- When Flipping Beats BRRRR
- The Math That Decides
- Tax Implications
- The Hybrid Approach
- 5 Mistakes
- FAQ
With BRRRR — Buy, Rehab, Rent, Refinance, Repeat — you keep the property. You rent it out, pull your equity back out through a cash-out refinance, and roll that capital into the next deal. Your money keeps working. Your portfolio grows.
With a flip, you sell. You take the profit check, pay taxes on it, and go find the next deal. Clean, fast, and cash in hand — but you no longer own anything.
Same property. Same rehab. Completely different financial outcome five years from now.
One strategy builds a rental portfolio and long-term wealth. The other generates short-term income you can redeploy into more deals — or spend. Neither is wrong. But picking the wrong one for a specific deal costs you real money.
How Each Strategy Works (Side by Side)
Here’s a step-by-step breakdown of each path:
| Step | BRRRR | Fix and Flip |
|---|---|---|
| 1 | Buy distressed property (cash or hard money) | Buy distressed property (cash or hard money) |
| 2 | Rehab to rent-ready condition | Rehab to retail-ready condition (higher finish level) |
| 3 | Rent to a qualified tenant | List with an agent or sell direct |
| 4 | Refinance with DSCR or conventional loan at 75% ARV | Close sale, collect net proceeds |
| 5 | Take cash out, repeat on next deal | Pay taxes, redeploy capital |
| Timeline | 6–12 months to complete refinance | 3–6 months to close sale |
| Capital needed | $30K–$60K (often recovered via refi) | $30K–$60K (stays tied up until closing) |
| Exit | Keep the property, recurring income | Sell, one-time profit |
The rehab quality differs too. Rental rehabs don’t need quartz countertops or designer fixtures. You want durable, functional, and tenant-proof. A flip rehab needs to compete with retail homes — buyers compare your kitchen to move-in-ready listings down the street. That difference can add $5,000–$15,000 to your flip rehab budget.
Use the fix and flip calculator and the BRRRR calculator to model your specific numbers before you commit to an exit strategy.
Worked Example — Same Property, Two Strategies
Let’s take a single deal and run it both ways.
The property: 3BR/2BA single-family in a mid-tier rental market. Purchase price: $120,000. Rehab: $35,000. After-repair value (ARV): $195,000.
Total all-in cost before exit: $155,000.
Run your own ARV estimate using the ARV calculator — it’s the single number that drives both strategies.
Path A: BRRRR
After rehab, you place a tenant at $1,550/month. That’s a solid rent for a $195K ARV home — roughly the 0.8% rent-to-price ratio you’ll find in many Midwest and Southeast markets.
You then do a cash-out refinance at 75% of ARV:
$195,000 × 75% = $146,250 loan
You put in $155,000. You pull out $146,250. Cash left in the deal: $8,750.
Monthly cash flow breakdown (principal + interest on 30yr at 7.5%, taxes, insurance, vacancy, maintenance):
| Item | Monthly Amount |
|---|---|
| Gross rent | $1,550 |
| Mortgage P&I ($146,250 @ 7.5%, 30yr) | –$1,023 |
| Property taxes | –$175 |
| Insurance | –$85 |
| Vacancy (5%) | –$78 |
| Maintenance/CapEx reserve | –$62 |
| Net monthly cash flow | +$127 |
That’s $1,524/year on $8,750 invested — a 17.4% cash-on-cash return. Check that math with the cash-on-cash return calculator.
And that’s just the cash flow. Over five years you also get:
Year 5 total return breakdown (BRRRR):
| Return Component | 5-Year Total |
|---|---|
| Cash flow ($127/mo × 60) | $7,620 |
| Principal paydown (approx.) | $23,400 |
| Appreciation at 3%/yr on $195K | ~$30,000+ |
| Total 5-year return | $61,000+ |
On $8,750 still tied up. The IRR on that is extraordinary.
Path B: Flip
You list the property after rehab. You’re holding it on hard money at 12% — about $1,550/month in interest alone on $155K. Add taxes, insurance, and utilities and you’re burning roughly $1,240/month in holding costs.
5-month hold: $6,200 in holding costs.
Then selling costs hit:
| Cost | Amount |
|---|---|
| Buyer’s agent commission (3%) | $5,850 |
| Listing agent commission (3%) | $5,850 |
| Closing costs / transfer tax (1%) | $1,950 |
| Total selling costs | $13,650 |
Net profit calculation:
$195,000 (sale price) – $155,000 (all-in) – $6,200 (holding) – $13,650 (selling) = $20,150 profit
ROI on $155K invested over 5 months: 13.0%. Annualized: approximately 31%.
That’s a strong flip. Use the fix and flip calculator to stress-test it before you commit — because the numbers above assume everything goes to plan.
Which Wins on This Deal?
| Metric | BRRRR | Fix and Flip |
|---|---|---|
| Immediate cash | $0 (you kept the house) | $20,150 |
| Capital still at work | $8,750 | $0 (freed up $155K) |
| Year 1 income | $1,524 | $20,150 (one-time) |
| Year 5 total return | $61,000+ | $20,150 (taxed) |
| Asset owned? | Yes | No |
| Tax liability | Low (depreciation offset) | High (ordinary income) |
The flip gives you $20,150 cash right now. The BRRRR gives you $127/month forever — and you still own the house at the end. Do the math: at $127/month, it takes about 13 years of BRRRR cash flow to equal the flip’s $20K. But at year 13, the BRRRR investor also owns a paid-down rental worth $280,000+ (at 3% appreciation). The flip investor has nothing unless they kept redeploying capital.
That’s the real tradeoff. Not which strategy earns more — but when you need the money and what you’re building toward.
When BRRRR Beats Flipping
BRRRR works best when the numbers support keeping the property. Here’s when that’s usually true:
Strong rent-to-price ratios. If you can hit 0.8%–1%+ of purchase price in monthly rent, a BRRRR deal pencils out. Markets like Indianapolis, Memphis, Cleveland, and parts of Texas and the Carolinas regularly hit these numbers. Check current cap rates with the NOI calculator before you commit.
Your DSCR clears 1.0+ after refi. If the rental income covers the refinanced loan payment, you can actually get the loan. Lenders want to see DSCR of at least 1.0, usually 1.25+. Run it through the DSCR calculator first — there’s no point executing a BRRRR on a property that won’t qualify for the refi.
You want portfolio growth, not just income. BRRRR builds equity, generates passive income, and creates tax write-offs that stack over time. If your goal is financial independence via rental income, BRRRR is the engine that gets you there.
You want tax advantages. Rental properties come with depreciation deductions, mortgage interest write-offs, repair deductions, and more. Read our full breakdown of rental property tax deductions to see how much of your cash flow you can shield from tax.
Lower interest rate environment. When mortgage rates drop, BRRRR deals that didn’t cash flow suddenly do. A refinance at 6.5% instead of 7.5% on a $146K loan saves $75/month — turning a break-even deal into a cash flowing one.
You want to minimize capital deployed. A perfect BRRRR deal pulls out 100% of your capital. Even pulling out 85% — like our $8,750 left in — lets you do 10x more deals with the same cash than buying and holding without refinancing.
When Flipping Beats BRRRR
Flipping isn’t the consolation prize. For the right deal, in the right market, with the right investor profile, it’s the smarter play.
You need capital now. If you’re early in your investing career with limited capital, flipping generates the cash to scale. Two or three solid flips can fund your first BRRRR deal with significant cash to spare. Many experienced investors flip to fund, then BRRRR to build.
The property won’t cash flow as a rental. High property tax markets (Illinois, New Jersey, Connecticut), expensive coastal cities, and markets with weak rent-to-price ratios often produce BRRRR deals with negative monthly cash flow after refinancing. If the DSCR is under 1.0, you can’t even get the refinance loan. Flip it.
It’s a hot appreciation market. If you’re in Phoenix in 2021 or Miami in 2022 — markets running up 20%+ annually — locking in ARV today and selling may beat holding through a correction. Flipping captures peak appreciation. BRRRR holds through the cycle.
The rehab is too extensive for a rental. A full gut-down-to-the-studs renovation with luxury finishes doesn’t make sense as a rental. You can’t charge enough rent to justify the cost. Flip it to a buyer who wants the premium finish level.
You don’t want to be a landlord. Managing tenants, maintenance calls, lease renewals, evictions — this is real work. Some investors want nothing to do with it. Flipping is a fully transactional business. You don’t deal with tenants at all. If that appeals to you, that’s a legitimate reason to flip.
You’re using hard money and can’t hold long-term. Hard money loans typically have 12–18 month terms. If you’re in a market where refinancing is difficult or takes longer than expected, you may be forced to sell before the BRRRR can be completed. Model the realistic rehab timeline before deciding which strategy to pursue.
The Math That Decides: BRRRR vs Flip
Most investors agonize over which strategy to use and ignore the numbers that actually answer the question. Here are the four checks that tell you what to do:
Check 1: DSCR after refinance. Run the refinanced loan amount through the DSCR calculator. If DSCR is under 1.0, you can’t get the loan — and shouldn’t BRRRR this property. Flip it.
Formula: DSCR = Net Operating Income ÷ Annual Debt Service
Using our example: NOI = ($1,550 × 12) – taxes – insurance – vacancy – maintenance = $14,520. Annual debt service on $146,250 at 7.5% = $12,276. DSCR = 1.18. That clears 1.0 — BRRRR works.
Check 2: Cash-on-cash return after refi. Use the cash-on-cash return calculator. If your CoC falls below 8% after refinancing, your capital may generate better returns deployed elsewhere — including into another flip. Our example hit 17.4%, so BRRRR wins on this metric.
Check 3: Flip holding costs per month. Every month you hold a flip adds $1,000–$2,000 in carrying costs. Hard money at 12% on a $155K loan = $1,550/month in interest alone. Add taxes ($175), insurance ($85), utilities ($100) = $1,910/month. A 3-month rehab delay on your flip just wiped out $5,730 of your profit.
Check 4: Opportunity cost. The $20,150 flip profit may be redeployed into the next deal in 5 months. The BRRRR investor has $8,750 tied up indefinitely. But if the BRRRR investor can do 10 BRRRRs with the same $155K it takes to do one flip — because they keep pulling their capital back out — the portfolio math gets very different very fast.
Model both scenarios side-by-side with the rental property investment analysis framework before you make a decision.
Tax Implications — BRRRR vs Flip
This is where flipping gets painful and most new investors get surprised.
Flip profits are taxed as ordinary income. If you flip properties regularly, the IRS treats you as a dealer — not an investor. Your $20,150 profit gets hit with:
| Tax | Rate | Amount on $20,150 Profit |
|---|---|---|
| Federal income tax (24% bracket) | 24% | $4,836 |
| Self-employment tax | 15.3% | $3,083 |
| State income tax (varies) | 0–10% | $0–$2,015 |
| Total taxes | ~39–49% | $7,900–$9,870 |
That $20,150 profit? After taxes, you’re keeping somewhere between $10,280 and $12,250. That changes the math considerably. Read the full breakdown in our house flipping taxes guide.
Per IRS Topic 409, if you sell a property you’ve held less than a year, it’s short-term capital gains — taxed at your ordinary income rate.
BRRRR rental income is taxed differently — and far more favorably.
Rental income is taxed at your marginal rate, yes. But it’s offset by depreciation. Under IRS Publication 527, residential rental property depreciates over 27.5 years.
Our $155,000 basis (excluding land, say 80% = $124,000 depreciable): $124,000 ÷ 27.5 = $4,509/year depreciation write-off.
Our annual cash flow is $1,524. Our depreciation deduction is $4,509. On paper, this rental property shows a $2,985 loss even though you’re cash flowing positive. That loss offsets other income (subject to passive activity rules).
Tax on $1,524 rental income: potentially zero. Tax on $20,150 flip profit: $7,900+. Use the depreciation calculator to see your exact write-off for any property.
The tax advantage of BRRRR compounds over time. A portfolio of 10 rental properties can generate $45,000/year in paper losses that shelter other income entirely. Flips give you no such protection.
Can You Do Both? The Hybrid Approach
Most experienced investors don’t choose one strategy and stick with it forever. They sequence them.
The common pattern: flip 3–5 properties to build $75,000–$150,000 in capital, then use that war chest to fund BRRRR deals. Every BRRRR deal either recycles capital (if you pull it all back out) or requires a small top-up from flip income. Over time, the rental portfolio carries itself and the flip income becomes optional.
“Flip to fund, BRRRR to build” is how most serious portfolio investors describe their first five years.
The other approach: let the deal choose the strategy. Some properties have great rent-to-price ratios and work as BRRRRs. Others are in high-appreciation markets where selling is more profitable. Others have rehab scopes that price themselves out of rental cash flow. You run the numbers on each deal and let the math tell you what to do.
Forcing a BRRRR on a property that should be flipped — or flipping a property that would have cash flowed for 20 years — is a mistake that’s easy to avoid if you model both exits before you close.
Check the BRRRR strategy guide and the fix and flip guide to understand the full execution details of each approach before you combine them.
5 Mistakes When Choosing BRRRR vs Flip
Mistake 1: Forcing a BRRRR on a property that won’t cash flow. If the rent doesn’t cover PITI + expenses after refinancing, you’ve bought yourself a money-losing rental. Run the DSCR check before you commit. A deal that doesn’t cash flow as a BRRRR should be flipped — or walked away from entirely.
Mistake 2: Flipping in a market where you should be holding. Some markets have such strong rent growth and appreciation that selling today means missing 10 years of compounding returns. If you’re in a metro with rising rents, falling vacancy, and strong job growth, think twice before handing that upside to a buyer.
Mistake 3: Ignoring taxes on flip profit. Investors model $20K profit and plan to spend $20K. The IRS takes $8K–$10K of that. Model after-tax profit, not gross. This single mistake causes investors to chronically undercapitalize their next deal after a flip.
Mistake 4: Overestimating ARV on a flip. BRRRR ARV overestimates hurt you at refinance time. Flip ARV overestimates can wreck the whole deal — you renovated to $195K ARV but the market caps out at $175K. Comps need to be tight: same neighborhood, same square footage, sold within 90 days, similar condition. Use the ARV calculator conservatively and run three comps minimum.
Mistake 5: Underestimating holding costs on a flip. Hard money at 12% on a $155K loan is $1,550/month. A rehab that runs two months over costs you $3,100 in extra interest before you even count taxes, insurance, and utilities. Holding cost surprises are the single biggest profit-killer on flips. Build in a 20% buffer on your timeline and cost every month of hold explicitly.
FAQ
Is BRRRR vs flip — which is more profitable?
Depends on the timeframe. Over 10+ years, a well-executed BRRRR almost always generates more total wealth than flipping the same property — because you keep the asset and capture appreciation, principal paydown, and cash flow simultaneously. In the short term (1–2 years), flipping wins on cash generated. The honest answer: BRRRR builds more wealth, flipping generates more immediate cash. Most successful investors use both at different stages.
How much money do I need to start BRRRR?
You need enough to cover the purchase and rehab — typically $30,000–$80,000 depending on your market. The BRRRR advantage is that a successful cash-out refinance returns most or all of that capital, letting you reuse it on deal #2. With a $50,000 starting capital and deals that return 90% of capital on refi, you can theoretically execute 5–7 BRRRRs before you need more outside capital. That said, always keep a reserve — refinances take time, tenants don’t always pay, and rehab overruns happen.
Can I BRRRR with hard money?
Yes, and most people do. Hard money covers the purchase and rehab phase. Once the property is stabilized with a tenant, you refinance into a DSCR loan or conventional investment property loan to pay off the hard money. The key is timing: hard money loans typically run 12–18 months. You need to rehab, rent, and refinance within that window. Budget your rehab timeline conservatively and get the refinance pre-approved in principle before you close the purchase.
Which is riskier — BRRRR or flipping?
They carry different risks. Flips have higher execution risk — overruns, market shifts, and carrying costs can turn a $20K profit into a $5K loss quickly. But the risk is time-limited: once you sell, you’re done. BRRRR has lower per-deal risk (you’re not depending on selling into a specific market) but carries ongoing landlord risk — bad tenants, vacancies, major repairs. Flipping is riskier short-term. BRRRR accumulates risk over time as your portfolio grows. Both risks are manageable with proper underwriting and reserves.
How many flips before switching to BRRRR?
There’s no magic number, but the typical pattern is 2–5 flips to build enough capital for a BRRRR down payment and reserves. A realistic target: $75,000–$100,000 in capital before starting BRRRR, so you can fund the deal, cover the rehab, weather a slow refinance, and still have $20,000–$30,000 in reserves. If you’re in a low-cost market, you might get there in 2 flips. In expensive markets, it might take 5–7. The hybrid model — keep flipping while you BRRRR — is what most high-volume investors do indefinitely.
Related Calculators
Run both exit strategies on your next deal before you commit. Here are the tools you need:
- BRRRR Calculator — Model purchase, rehab, rent, and cash-out refinance in one tool. See cash left in deal, CoC return, and Year 1–5 projections.
- Fix and Flip Calculator — Calculate net profit after purchase, rehab, holding costs, and selling costs. Includes hard money interest modeling.
- Cash on Cash Return Calculator — Determine your annual return on invested capital for any rental property scenario.
- ARV Calculator — Estimate after-repair value from comparable sales. The single number that drives both BRRRR and flip math.
- NOI Calculator — Calculate net operating income for any rental property to check profitability before you buy.
For deeper analysis, the DSCR calculator tells you whether a refinanced BRRRR deal will actually qualify for the loan — and the depreciation calculator shows you the annual tax write-off you’d get on a BRRRR hold.
According to National Association of Realtors research data, residential investment property continues to outperform most asset classes over 10+ year periods — a fact that makes the “hold via BRRRR” case stronger for long-term wealth building than the raw cash-flow numbers alone suggest.
Leave a Reply