Published: September 28, 2026 · By Alex Petrov
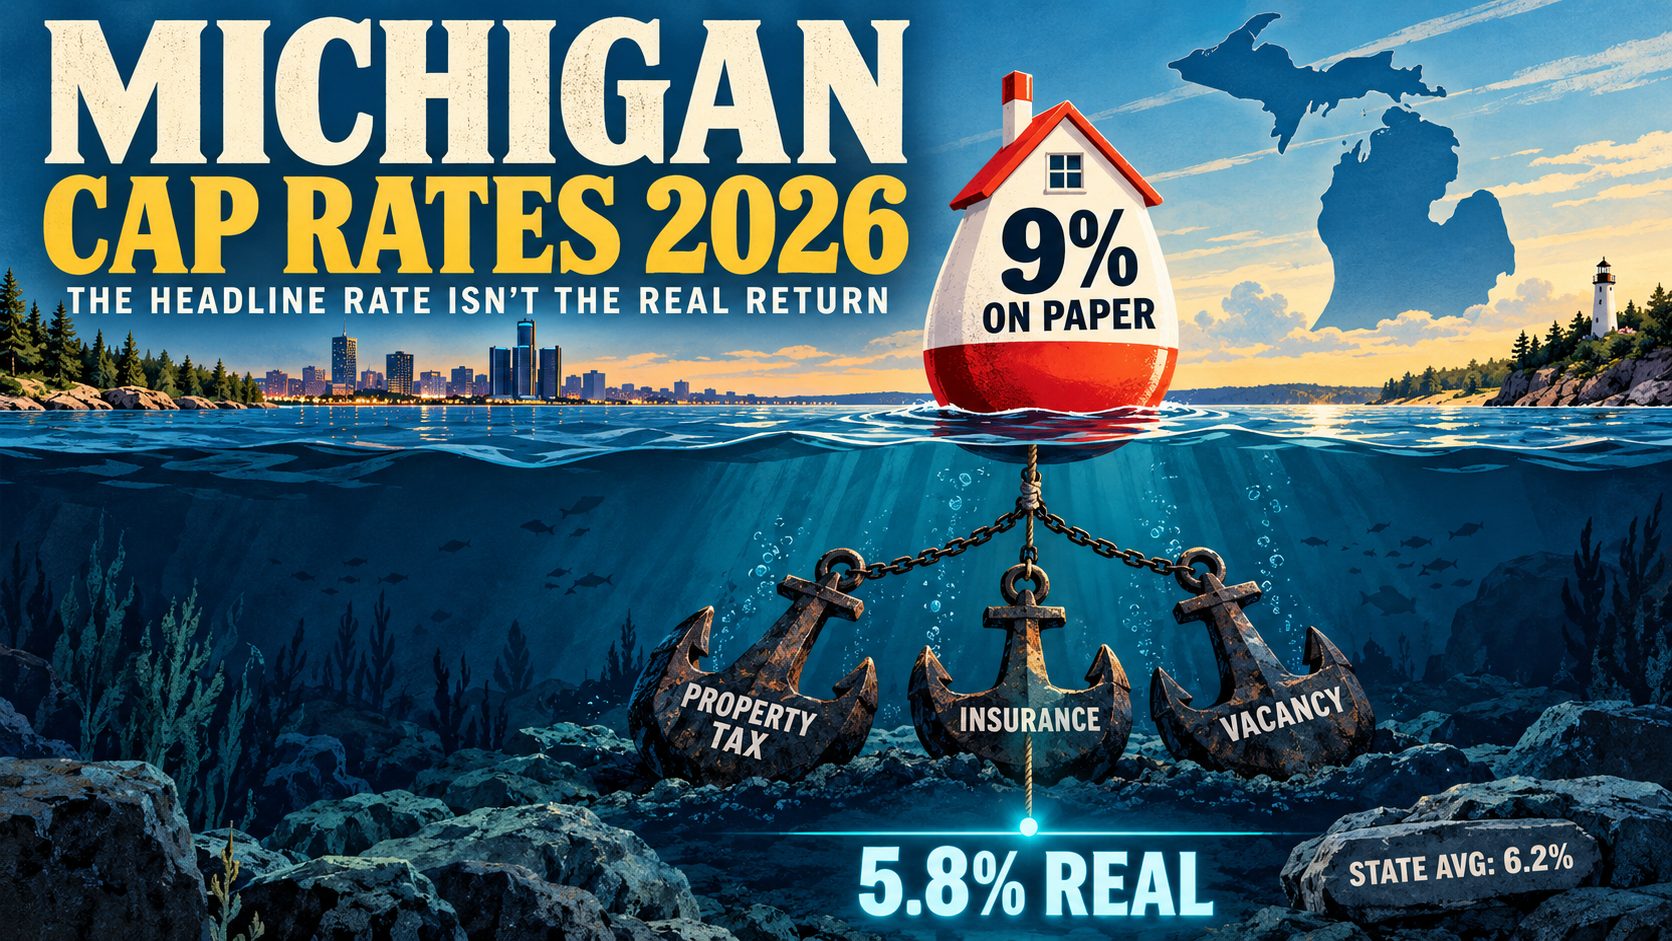
Michigan cap rates average 5.5–7.5% across the state — well above the 4–5% national baseline — but that headline number hides a wild spread. Detroit can show cap rates above 9% on paper, then the tax bill arrives and it drops to 6%. Ann Arbor runs 4–5% and that’s actually fair given demand. Eight cities, eight completely different risk/return profiles. Use the Michigan cap rate calculator to run any of these deals with Michigan-specific property tax, insurance, and vacancy defaults pre-loaded.
Michigan Cap Rates in 2026 — What the Data Shows
Michigan’s statewide average cap rate sits at roughly 6.2% for stabilized single-family rentals — about 150 basis points above the national average per Michigan Realtors data for Q2 2026. That gap exists for three reasons: affordable purchase prices relative to rent, a diversified industrial economy that supports working-class tenants, and generally higher property taxes that other investors price in before they buy.
Nationally, cap rates on residential investment property cluster around 4.5–5.5% in most coastal and Sun Belt markets. Michigan’s 6.2% average looks great until you compare it to Indiana at 6.8% or Ohio at 6.0% — the Midwest as a whole runs hotter than the national average. Michigan’s edge over Indiana is stricter landlord protections (a risk factor, not a dealbreaker), and its edge over Ohio depends heavily on which city you’re in.
The city-to-city spread within Michigan is what really matters. Detroit’s property tax rate runs 2.8% of assessed value for non-homestead (investor-owned) properties. Grand Rapids sits at 1.2%. Ann Arbor is around 1.5%. Flint varies but typically lands between 2.0–2.4%. That tax gap alone can swing a deal from a 7% cap rate to a 5% cap rate on the same gross rent — sometimes the difference between cash-flowing and breaking even. Every single analysis needs city-specific tax rates, not a state average.
Cap Rates by City — 8 Michigan Metros
The table below uses realistic 2026 market data. Cap rates are calculated as NOI ÷ purchase price. NOI accounts for vacancy, property tax, insurance, maintenance (8% of gross), and property management (10% of collected rent). Mortgage is excluded — cap rate is always an unlevered return metric.
| Metro | Median Price | Median Rent | Cap Rate | Property Tax | Vacancy | Verdict |
|---|---|---|---|---|---|---|
| Detroit | $165,000 | $1,100/mo | 6.5–8.5% | 2.8% | 8% | High yield, high complexity |
| Grand Rapids | $245,000 | $1,650/mo | 5.5–6.5% | 1.2% | 4.5% | Best risk-adjusted returns |
| Ann Arbor | $385,000 | $1,900/mo | 4.0–5.0% | 1.5% | 3.5% | Appreciation play, low cash flow |
| Lansing | $195,000 | $1,200/mo | 5.5–6.5% | 1.8% | 5.5% | Solid, government-anchored |
| Kalamazoo | $220,000 | $1,350/mo | 5.0–6.5% | 1.6% | 5.0% | College town, stable demand |
| Flint | $80,000 | $750/mo | 7.0–9.5% | 2.2% | 12% | High risk, buyer beware |
| Warren/Sterling Hts | $230,000 | $1,500/mo | 5.5–7.0% | 1.9% | 5.0% | Strong suburban demand |
| Traverse City | $395,000 | $1,750/mo | 3.5–5.0% | 1.3% | 8–15%* | STR market, seasonal LTR risk |
*Traverse City vacancy depends entirely on STR vs. long-term rental strategy. Long-term rentals face 8–12% seasonal vacancy. Short-term rentals can outperform but carry licensing and regulatory risk.
Quick NOI math for each city using median numbers above:
- Detroit ($165K, $1,100/mo): Gross $13,200 → 8% vacancy ($1,056) → $12,144 effective → expenses (~$5,820 tax + insurance + mgmt + maint) → NOI ~$6,324 → cap rate 3.8% on paper, but cheaper properties in distressed neighborhoods push the rent-to-price ratio up significantly. Sub-$100K buys in specific ZIP codes routinely show 7%+.
- Grand Rapids ($245K, $1,650/mo): Gross $19,800 → 4.5% vacancy ($891) → $18,909 effective → expenses (~$7,780) → NOI ~$11,129 → cap rate 4.5%. Well-run properties in East GR and Kentwood push 5.5–6.5%.
- Flint ($80K, $750/mo): Gross $9,000 → 12% vacancy ($1,080) → $7,920 effective → expenses (~$4,100) → NOI ~$3,820 → cap rate 4.8% even at these prices. High vacancy crushes what looks like a great rent-to-price ratio.
Run your specific numbers in the NOI calculator — it shows the exact line-item breakdown before you ever touch the cap rate figure.
How to Calculate Cap Rate on Michigan Properties
The formula hasn’t changed:
Cap Rate = NOI ÷ Property Value
Where NOI = all income minus all operating expenses. The tricky part is getting the expense stack right for Michigan.
What goes into NOI:
- Gross rent — actual collected rent at full occupancy
- Minus vacancy — Michigan statewide average is around 6.5%, but use metro-specific rates
- Minus property tax — this is where Michigan bites. Michigan taxes rental properties at the non-homestead rate, which is higher than the principal residence exemption rate most homeowners pay. Detroit’s 2.8% non-homestead rate is not a typo.
- Minus insurance — Detroit runs $2,200–$2,800/year. Outstate Michigan (Grand Rapids, Lansing, Kalamazoo) runs $1,100–$1,400/year. Traverse City is middle ground around $1,500–$1,800.
- Minus property management — 8–10% of collected rent, typically
- Minus maintenance and CapEx reserve — 8–10% of gross rent is a reasonable budget for Michigan’s older housing stock
What does NOT go into NOI:
- Mortgage payments — principal and interest are financing costs, not operating expenses
- Depreciation — a tax accounting concept, not a cash expense
- City income tax — technically an investor-level expense, not a property-level expense; cap rate is pre-income tax
- Acquisition costs — closing costs, inspection, appraisal; use Michigan closing costs calculator to track these separately
Michigan’s non-homestead property tax is a calculation trap that catches out-of-state investors every time. When a property sells, it may have been owner-occupied under the principal residence exemption. Zillow and public records often show the previous owner’s tax bill. The moment you take title as an investor, the full non-homestead rate kicks in — and in Detroit, that difference can be $3,000–$5,000/year on a $165K property. Always calculate taxes at the non-homestead rate per the Michigan Department of Treasury tables before running any cap rate analysis.
For a complete Michigan deal analysis including financing, cash-on-cash, and DSCR, use the Michigan rental property calculator. For cap rate specifically — including reverse-solve modes where you enter your target cap rate and it tells you the maximum purchase price — use the Michigan cap rate calculator.
Worked Example — Grand Rapids SFR
This is a real deal structure based on current Grand Rapids east-side market conditions.
Property: 3BR/1BA SFR, East Grand Rapids adjacent
Purchase price: $245,000
Gross monthly rent: $1,650
NOI calculation:
- Gross annual rent: $1,650 × 12 = $19,800
- Vacancy (4.5%): −$891
- Effective gross income: $18,909
- Property tax (1.2% non-homestead × $245,000): −$2,940
- Insurance (Grand Rapids outstate rate): −$1,250
- Property management (10% of $18,909): −$1,891
- Maintenance/CapEx reserve (8% of gross): −$1,584
- NOI: $11,244
Cap Rate = $11,244 ÷ $245,000 = 4.59%
That’s honest. Not the 6.5% you might see on a wholesaler’s proforma. Why the gap? Most proformas understate vacancy, skip a maintenance reserve, and use the previous owner’s homestead tax rate. Add those back in and you’re at 4.6%.
Is 4.6% good? For Grand Rapids in 2026 — yes, actually. The national SFR cap rate average sits around 4.8% per NCREIF, and Grand Rapids has stronger rent growth (4.2% YoY) and tighter vacancy than most comparable markets. This isn’t a cash flow machine, but it’s a compounding machine: low vacancy, rising rents, and a city with actual job growth (medical device manufacturing, healthcare, tech).
At 7% mortgage rate on 20% down ($49,000 down, $196,000 loan), monthly P&I is about $1,304. Monthly NOI is $937. You’re cash-flow negative by roughly $367/month. This pencils if rent grows 3–4%/year or if you can push rents above $1,750 on a renovation. Run the scenarios in the Michigan rental property calculator — it shows exactly when the deal turns cash-flow positive and what your year-10 unlevered return looks like.
Want to check if a DSCR loan works for this deal? The Michigan DSCR calculator will show you whether the NOI supports the debt at current rates.
Worked Example — Detroit Duplex
Detroit is where investors come looking for double-digit cap rates and leave with a tax bill. Here’s what actually happens when you run the full numbers.
Property: Duplex, near Detroit Medical Center corridor
Purchase price: $165,000
Unit 1 rent: $950/month
Unit 2 rent: $900/month
Gross monthly rent: $1,850
NOI calculation:
- Gross annual rent: $1,850 × 12 = $22,200
- Vacancy (8%): −$1,776
- Effective gross income: $20,424
- Property tax (2.8% non-homestead × $165,000): −$4,620
- Insurance (Detroit premium rate): −$2,400
- Property management (10% of $20,424): −$2,042
- Maintenance/CapEx reserve (8% of gross): −$1,776
- NOI: $9,586
Cap Rate = $9,586 ÷ $165,000 = 5.81%
Not 9%. Not 12%. 5.81%. Detroit’s tax and insurance load ate roughly $7,000/year of would-be NOI. That’s the Detroit math that doesn’t show up in the headline cap rate you see on BiggerPockets posts.
Add Detroit’s 2.4% city income tax on rental income and your after-tax return drops further — though again, cap rate itself is pre-income-tax. For actual cash flow at current financing rates (7% on 20% down = $132,000 loan, ~$879/month P&I), monthly NOI is $799. Monthly cash flow after debt service: −$80. Nearly break-even.
The Detroit thesis isn’t “buy and cash flow.” It’s “buy distressed, force value, rent both units, refinance, repeat.” For that strategy, Detroit still works — but only if you’re running the Michigan BRRRR calculator from the start and accounting for realistic after-rehab rents, real tax rates, and Detroit’s insurance reality. If you’re buying turn-key duplex expecting a clean 8% cap, do the full math first using the cap rate calculator.
Detroit’s silver lining: rent growth. The DMC/Midtown corridor has seen 6–8% annual rent growth since 2023. If Unit 1 hits $1,100 and Unit 2 hits $1,050 within two years (both realistic for renovated units near DMC), your NOI jumps to ~$12,300 and your cap rate on original purchase price hits 7.5%. That’s where Detroit money is made — not on day one numbers.
What’s a Good Cap Rate in Michigan?
It depends on what you’re buying the property to do.
Pure cash flow strategy (7%+ target): You need Detroit, Flint, or specific neighborhoods in Warren or Lansing. These markets trade at high caps because they carry higher vacancy, maintenance, and management risk. The 7%+ cap is the risk premium. If you can manage these properties well — or find a PM who specializes in them — the returns are there. The Michigan rental property calculator helps stress-test these deals at different vacancy scenarios.
Appreciation + cash flow balance (5.5–6.5% target): Grand Rapids, Warren/Sterling Heights, and Lansing all sit in this range. You’re not getting rich on cash flow, but you’re not losing money either. Rent growth, population stability, and moderate appreciation make these compounding plays over a 5–7 year hold.
Appreciation play (4–5% cap rate): Ann Arbor and Traverse City. You’re accepting compressed cash flow because the underlying asset appreciates. Ann Arbor has one of the most stable rental demand profiles in the Midwest — University of Michigan creates constant tenant demand and limits oversupply risk. A 4.2% cap rate in Ann Arbor isn’t a mistake. It’s the price of certainty.
By city, here’s what’s realistic in 2026:
- Detroit: 6–8% cap rate is achievable on the right deal. Below 5% means you overpaid or the proforma is optimistic. Above 9% means you’re in a neighborhood where the vacancy or maintenance risk will close that gap fast.
- Grand Rapids: 4.5–5.5% is honest for SFRs. Duplexes can push 5.5–6.5%.
- Ann Arbor: 4–5% is the market. Anyone quoting 6% in Ann Arbor is skipping a cost line.
- Lansing: 5.5–6.5% is solid and sustainable. State government employment base keeps vacancy low.
- Kalamazoo: 5–6.5% depending on whether you’re near WMU or in a non-student neighborhood.
- Flint: 6–8% is possible. The 12% vacancy rate is the ceiling. See the next section.
- Warren/Sterling Heights: 5.5–7% on the right deal. Macomb County property tax is manageable at 1.9%.
- Traverse City: 3.5–5% for long-term rentals. STR can outperform significantly but requires a separate analysis in the Michigan rental property calculator.
Michigan Cap Rate Traps
Five things that will make your Michigan cap rate look better on paper than it performs in reality:
1. Non-homestead property tax rate. This is the number one mistake out-of-state investors make in Michigan. The current owner may be paying taxes under the Principal Residence Exemption (PRE) — a lower rate available only to owner-occupants. Once you close, your rate flips to the full non-homestead millage. In Detroit, that means your effective tax rate might jump from what the listing shows (~1.8%) to the actual investor rate (2.8%). On a $165K property, that’s $1,650/year difference. Always calculate at the non-homestead rate. Pull the exact millage from the Michigan Department of Treasury by county before you underwrite.
2. City income tax in Michigan cities. Detroit charges a 2.4% income tax on rental income from Detroit properties — whether you live there or not. Grand Rapids charges 1.5% for non-residents. Lansing charges 1.0%. These are investor-level expenses that don’t appear in the cap rate calculation (which is pre-income-tax), but they affect your actual cash-on-cash return significantly. If you’re comparing a Detroit deal against an Ohio deal, the city income tax gap matters. Run both through the Michigan rental property calculator vs. the comparable tool for Ohio to see the after-tax difference.
3. Detroit insurance premiums. Standard rental dwelling policies in Detroit run $2,200–$2,800/year on a median-priced property. The same property in Grand Rapids or Kalamazoo would cost $1,100–$1,400. That $1,400 annual gap is about 0.85 percentage points of cap rate on a $165K property. When you see a Detroit deal on a wholesaler’s spreadsheet with $1,200 insurance, the proforma is wrong. Detroit’s crime rate and claim history push premiums up. Get an actual quote before you close — check the rental property insurance cost by state guide for baseline Michigan numbers.
4. Seasonal vacancy in northern Michigan. Traverse City is a tourism economy. A 3-bed SFR that rents long-term runs 8–12% vacancy because winter turnover is real — many tenants leave after summer employment ends. If you’re running a long-term rental in a tourist-driven northern Michigan market, use vacancy in the 10–12% range, not the state average. If you pivot to STR, calculate that separately — the Michigan rental property calculator has an Airbnb income mode. Just don’t mix LTR vacancy assumptions with a property that functions as an STR.
5. Flint’s 12% vacancy rate eating cap rates alive. Flint looks incredible on a price-to-rent ratio: $80K property, $750/month rent is a 1.06% monthly rent-to-price ratio — above the 1% rule threshold. But run the vacancy. At 12%, you lose 1.44 months of rent per year. That’s $1,080 gone before you pay a single expense. Flint’s water infrastructure history created a population decline that structural demand never recovered from per Census ACS data. Paper cap rates of 9–12% are common. Actual stabilized cap rates after realistic vacancy, maintenance on aging housing stock, and higher insurance are often 5–7% — similar to better markets with none of the risk. Don’t chase cap rates in Flint without underwriting Flint specifically: real vacancy, real insurance, real condition of the housing stock in the specific neighborhood.
Michigan vs Other Midwest States
How Michigan stacks up against comparable Midwest investment markets:
| State | Avg Cap Rate | Effective Property Tax | State Income Tax | Avg Insurance | Landlord-Friendliness |
|---|---|---|---|---|---|
| Michigan | 5.5–7.0% | 1.2–2.8% | 4.25% flat | $1,200–$2,800 | Moderate |
| Ohio | 5.0–7.0% | 1.6–1.9% | 2.75% flat | $2,100 | Moderate-Friendly |
| Indiana | 5.5–7.5% | 0.8–1.1% | 3.05% flat | $1,600 | Very Friendly |
| Wisconsin | 4.5–6.0% | 1.7–2.1% | 5.3–7.65% | $1,800 | Moderate |
Michigan’s headline cap rates are competitive, but Indiana actually beats it on two key expense lines: lower property tax (some Indiana counties run below 1%) and slightly lower insurance. Indiana’s landlord law is also more favorable for expedited eviction proceedings — a real operational consideration.
Ohio competes closely with Michigan. Columbus vs. Grand Rapids is necessaryly a coin flip at 5% caps with different growth stories. Cleveland vs. Detroit is the more interesting comparison: similar price points, similar cap rates, different risk profiles. Detroit’s higher insurance and city income tax make it slightly less favorable than Cleveland when you line up identical deals. Ohio’s state income tax rate (2.75%) is lower than Michigan’s (4.25%), which matters on a $15,000 NOI — that’s a $225/year difference.
Wisconsin’s cap rates are compressed by higher entry prices and high property taxes in major metros. Milwaukee gets the Cleveland/Detroit comparison sometimes, but Wisconsin’s progressive income tax (top bracket 7.65%) meaningfully erodes cash-on-cash for higher-income investors. Michigan at 4.25% flat is simpler and cheaper for most investor tax profiles.
For a full multi-state comparison, the cap rate by state guide covers 20+ markets with consistent methodology. If you’re actively comparing Michigan to Indiana or Ohio deals, run both through the cap rate calculator using state-specific defaults.
FAQ: Michigan Cap Rates
What is the average cap rate in Michigan?
Michigan’s statewide average cap rate for stabilized residential investment properties runs approximately 6.2% in 2026, based on Q2 market data. That figure covers a wide range — from 3.5–5% in high-appreciation markets like Ann Arbor and Traverse City, to 7–9% in Detroit, Flint, and some Warren neighborhoods. The statewide average is useful for benchmarking but not for underwriting a specific deal. Use the Michigan cap rate calculator with the actual purchase price, rent, and city-specific tax rate for any deal you’re seriously analyzing.
What is a good cap rate in Detroit?
Given Detroit’s expense profile — 2.8% non-homestead property tax, $2,200–$2,800 insurance, 8% vacancy — a 6.5–8% cap rate represents a genuinely good deal. Below 5.5% in Detroit usually means the proforma is using unrealistic expense assumptions. Above 9% usually means the property is in a high-vacancy, high-crime neighborhood where the theoretical cap rate will be eroded by actual performance. Aim for 6.5–8% with a full expense stack, and verify with the Michigan cap rate calculator using Detroit-specific defaults.
Is Grand Rapids better than Detroit for cap rate investing?
They serve different strategies. Grand Rapids has lower cap rates (4.5–5.5% on SFRs) but also lower risk: 4.5% vacancy vs. Detroit’s 8%, $1,250 insurance vs. $2,400, 1.2% property tax vs. 2.8%. Detroit has higher potential cap rates (6.5–8%) but higher operational complexity: city income tax, higher insurance, vacancy risk, and a management-intensive environment. If you’re a local operator or working with a Detroit-specialist PM, Detroit can outperform. If you’re out-of-state with a passive strategy, Grand Rapids is the more predictable result. Check the Michigan rental property investment guide for a deeper breakdown of both markets.
How does Michigan property tax affect cap rate?
Significantly. Michigan’s non-homestead property tax applies to all investor-owned properties at rates that vary from roughly 1.2% (Grand Rapids) to 2.8% (Detroit). On a $200,000 property, that difference is $3,200/year — about 1.6 percentage points of cap rate. Always underwrite using the non-homestead millage rate for the specific county and city, not the statewide average and never the previous owner’s homestead tax bill. The Michigan cap rate calculator lets you input the exact millage rate for your property’s location. Full millage tables are published by the Michigan Department of Treasury.
Should I invest in Flint for high cap rates?
Flint requires serious due diligence before the cap rate number means anything. The 12% vacancy rate is structural — population decline driven by deindustrialization and infrastructure history means rental demand won’t recover to normal levels across the city. In specific Flint neighborhoods (near McLaren hospital, some parts of the north end) there’s genuine rental demand and real cap rates of 6–8% do exist. But across-the-board Flint investment based on the price-to-rent ratio alone is a trap. If you’re pursuing Flint, underwrite each property with Flint-specific vacancy (10–14%), get actual insurance quotes, and stress-test at 15% vacancy in the Michigan rental property calculator before you commit. See also: what’s a good cap rate for rental property — context matters as much as the number.
Run Your Michigan Deal Now
Michigan has some of the best risk-adjusted cap rates in the Midwest when you’re in the right city with the right numbers. The state average of 6.2% is real — but so are the Detroit tax bill and Flint’s vacancy. Every deal is its own math problem.
Tools to use for Michigan analysis:
- Michigan Cap Rate Calculator — Michigan-specific tax and vacancy defaults; three calculation modes including reverse-solve
- Michigan Rental Property Calculator — full cash flow, NOI, CoC, DSCR in one tool
- Michigan DSCR Calculator — verify loan qualification with Michigan-specific insurance and tax defaults
- Michigan Closing Costs Calculator — Michigan transfer tax, recording fees, title insurance estimates
- Michigan BRRRR Calculator — for Detroit and distressed-market value-add strategies
- Cap Rate Calculator — generic calculator for cross-state comparisons
- NOI Calculator — isolate operating performance before financing
For context on how Michigan fits into the national picture, read the cap rate by state guide, the Michigan rental property investment guide, and the good cap rate guide. Insurance expense is often the overlooked variable — the rental property insurance cost by state breakdown shows exactly how much Michigan varies from other markets.
Leave a Reply