Published: October 1, 2026 · By Alex Petrov
Every profitable flip starts with one number: ARV. After Repair Value tells you exactly what a property should sell for once the renovation is done — and getting it wrong by even 8–10% can turn a $30,000 profit into a $5,000 loss. I learned this the hard way on my third deal in 2019 when I overestimated ARV by $22,000 on a ranch in Parma, Ohio, and barely broke even after holding costs ate my margin. Since then, I have closed 17 flips across Ohio, Georgia, and Tennessee, and every single deal starts with the same process: finding the right comps. This guide walks you through exactly how to find ARV — from selecting comparable sales to adjusting them and getting a final number you can trust. Once you know how to find ARV with the right comps, plug them into the ARV calculator and run the math in under two minutes.
What Makes a Good ARV Comp
Knowing how to find ARV starts with choosing the right comps. Not every recent sale qualifies as a comparable. I have seen new flippers pull the highest sale in a 5-mile radius and call it a “comp” — that is not how this works. A good ARV comp is a recently sold property that represents what your property will look like after rehab. The comp should mirror your subject in size, style, location, and condition.
If you want to learn how to find ARV accurately, here is what separates a strong comp from a weak one:
| Criteria | Strong Comp | Weak Comp |
|---|---|---|
| Distance | Within 0.5–1 mile of subject | Over 2 miles away, different neighborhood |
| Recency | Sold in the last 3–6 months | Sold 9+ months ago |
| Size | Within 200 sqft of subject | 500+ sqft difference |
| Property type | Same type (SFR to SFR) | Different type (condo vs SFR) |
| Condition | Renovated — matching your post-rehab quality | Distressed or unrenovated sale |
| Bed/bath | Within ±1 bed and ±1 bath | 2+ bed/bath difference |
| Sale type | Arm’s-length transaction | Foreclosure, short sale, or family transfer |
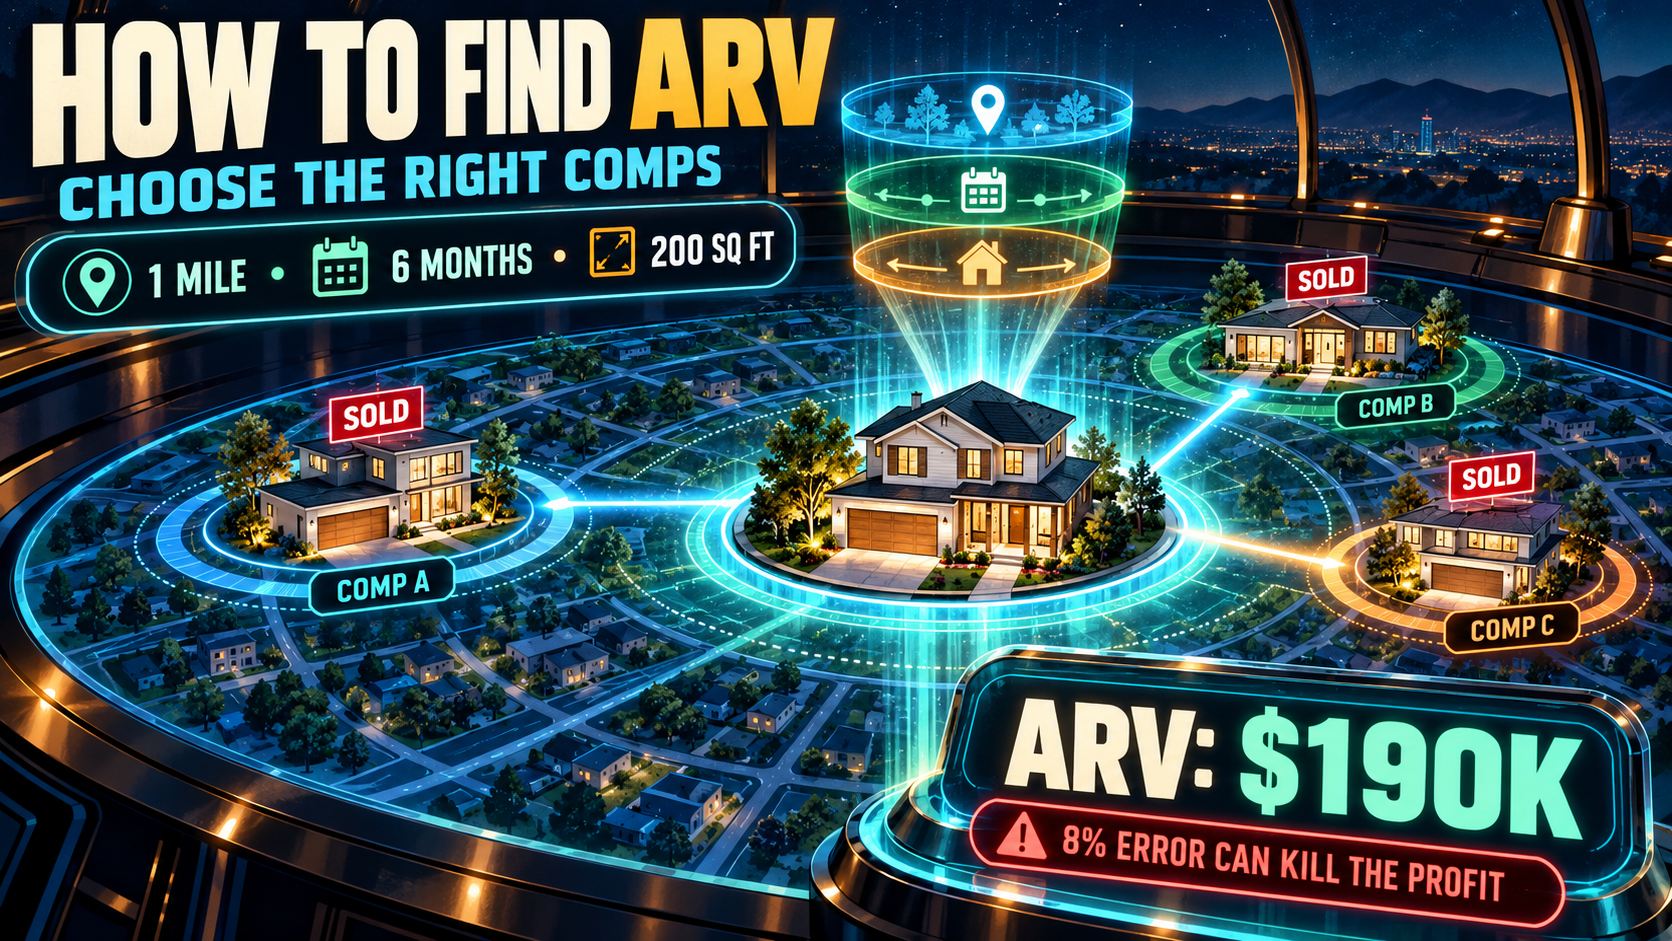
Appraisers use a nearly identical checklist. The Federal Housing Administration (FHA) requires appraisals to use comps within 1 mile and 12 months, but flippers should hold themselves to a tighter standard: 1 mile, 6 months, 200 sqft. If you cannot find 3 comps within those limits, gradually widen — first expand the time window to 9 months, then the radius to 1.5 miles. Never expand everything at once.
A strong comp set usually has 3–5 sales. Fewer than 3 gives you no statistical confidence; more than 5 starts diluting the signal with noise. Find your best 3, confirm with a 4th if possible, and move on. You can always run the numbers through the ARV calculator to see how sensitive the estimate is to each comp.
The 1-Mile, 6-Month, 200-Sqft Rule
This rule is the backbone of every ARV estimate I run. It is simple, and it works:
- 1 mile maximum radius — properties in the same school zone, same neighborhood character, same buyer pool. Cross a highway or a school district line and values can shift 10–15%. According to Zillow Research, median home values can vary by more than $50,000 between adjacent ZIP codes in the same metro area.
- 6 months maximum age — real estate markets shift. A comp from 9 months ago might reflect a different rate environment, different buyer demand, or a seasonal swing. In 2025–2026, with mortgage rates bouncing between 6.2% and 7.1%, even a 3-month difference in sale date can mean a 2–3% price gap.
- 200 sqft maximum size difference — price per square foot is not linear. A 1,200 sqft home and a 1,800 sqft home attract different buyers and hit different price points. Keep comps within 200 sqft of your subject’s post-rehab size (including any additions you plan).
I think of these three limits as concentric filters. Start tight. If the local MLS returns 4–5 renovated sales within 0.5 miles and 3 months? You are golden. If you get zero results, loosen one filter at a time. Here is the order I follow:
- Expand time to 9 months (keep distance and size tight)
- Expand radius to 1.5 miles (keep time at 9 months, size tight)
- Expand sqft to 300 (last resort — apply a price-per-sqft adjustment)
If you still cannot find 3 comps after loosening all three, that is a warning sign. Either the neighborhood has very low turnover (common in rural areas) or your property is truly unique. Both scenarios increase risk. For a deeper look at how ARV drives your offer price, check the 70% rule guide.
Where to Find Comps: MLS, Zillow, Redfin, County Records
You do not need MLS access to find good comps — though it helps. Here are the four sources I use on every deal, ranked by reliability:
1. MLS (via Agent or PropStream)
The MLS is the gold standard. It gives you sold prices, days on market, listing photos (so you can judge condition), and agent remarks. If you have a licensed agent on your team, ask them to pull a CMA (Comparative Market Analysis) for the subject property. If you do not have an agent, tools like PropStream and Privy pull MLS data for a monthly subscription.
Pro tip: Always look at the MLS photos of sold comps. A listing that says “updated kitchen” might mean new countertops and hardware, or it might mean a full gut reno with custom cabinets. Photos tell you the actual renovation level — and that matters for condition adjustments.
2. Redfin
Redfin shows sold data for free, including sale price, sqft, lot size, and — in many markets — interior photos from the original listing. Use the “Sold” filter, set your date range, and draw a polygon around your target neighborhood. Redfin’s Data Center also publishes monthly median sale prices by metro, which helps you gauge whether the market is trending up or down.
Workflow: Go to Redfin → search your property address → click “Nearby Sales” → filter to 6 months, similar sqft range → sort by distance. Screenshot each comp and save the listing URL.
3. Zillow
Zillow’s Zestimate is not an ARV — do not use it as one. But Zillow’s “Recently Sold” filter is excellent for finding comps. Filter by “Sold” status, set the date range, and look for renovated properties. Zillow also shows the price history, which helps you spot flips (bought low, sold high within 6–12 months). Those are your best comps — they show what a renovated version of a similar property actually sold for.
4. County Assessor / Public Records
Every county assessor’s office maintains public records of property transfers. Some counties (Cuyahoga in Ohio, Fulton in Georgia, Davidson in Tennessee) have excellent online portals where you can search by address and see sale prices, deed transfers, and tax assessments. County records are especially useful for verifying that a sale was arm’s-length — not a foreclosure, family transfer, or bank-owned sale that would skew your ARV.
I typically cross-reference at least two sources. If Redfin says a comp sold for $245,000 and the county records confirm $245,000, I am confident. If the numbers do not match, I dig deeper. For step-by-step instructions on finding ARV by property address, see the ARV by address guide.
Worked Example #1 — Finding ARV for a Cleveland Ranch Flip
Let me walk through a real-world comp search, start to finish.
Subject property: 3-bed/1.5-bath ranch, 1,280 sqft, built 1962
Location: West Park neighborhood, Cleveland, OH (44111)
Condition: Needs full kitchen remodel, bath update, new flooring, paint, roof repair
Post-rehab plan: Updated kitchen with granite counters, refinished hardwood floors, new bathroom tile, painted exterior
Estimated rehab: $38,000 (see the rehab cost guide for line-item breakdowns)
Step 1: Search for Comps
On Redfin, I search “West Park, Cleveland, OH” → filter: Sold in last 6 months, 1,000–1,500 sqft, 3+ beds, single-family. I get 11 results within 1 mile. I eliminate:
- 2 foreclosures (not arm’s-length)
- 1 sale at $89,000 (unrenovated — pre-flip condition, not a valid ARV comp)
- 3 sales over 1,500 sqft (too large)
- 2 sales with no interior photos (cannot verify condition)
That leaves me 3 strong comps:
Step 2: Analyze and Adjust
| Detail | Comp A — Triskett Rd | Comp B — Maplewood Ave | Comp C — Brookpark Rd |
|---|---|---|---|
| Sale price | $192,000 | $201,000 | $185,000 |
| Sale date | Apr 2026 | May 2026 | Feb 2026 |
| Sqft | 1,310 | 1,400 | 1,220 |
| Bed/bath | 3/1.5 | 3/2 | 3/1 |
| Condition | Renovated — similar to plan | Renovated — premium finishes | Renovated — basic update |
| Distance | 0.4 miles | 0.7 miles | 0.6 miles |
| Garage | 1-car detached (same) | 2-car detached | No garage |
Step 3: Make Adjustments
Comp A — Triskett Rd ($192,000):
- Sqft: 1,310 vs 1,280 = comp is 30 sqft larger → subtract $50/sqft × 30 = −$1,500
- Bed/bath: identical (3/1.5) → $0
- Condition: similar renovation level → $0
- Garage: same (1-car detached) → $0
- Adjusted: $192,000 − $1,500 = $190,500
Comp B — Maplewood Ave ($201,000):
- Sqft: 1,400 vs 1,280 = comp is 120 sqft larger → subtract $50/sqft × 120 = −$6,000
- Bed/bath: comp has full 2nd bath vs half bath → subtract −$4,000
- Condition: premium finishes vs standard → subtract −$5,000
- Garage: 2-car vs 1-car → subtract −$6,000
- Adjusted: $201,000 − $6,000 − $4,000 − $5,000 − $6,000 = $180,000
Comp C — Brookpark Rd ($185,000):
- Sqft: 1,220 vs 1,280 = comp is 60 sqft smaller → add $50/sqft × 60 = +$3,000
- Bed/bath: comp has 3/1 vs 3/1.5 = missing half bath → add +$2,500
- Condition: basic update vs standard reno → add +$3,000
- Garage: no garage vs 1-car detached → add +$8,000
- Adjusted: $185,000 + $3,000 + $2,500 + $3,000 + $8,000 = $201,500
Step 4: Calculate ARV
Adjusted comps: $190,500 + $180,000 + $201,500 = $572,000
ARV = $572,000 ÷ 3 = $190,667
Rounded: ARV = $190,000 (conservative)
With an ARV of $190,000 and rehab at $38,000, the 70% rule calculator gives me a max offer of $190,000 × 0.70 − $38,000 = $95,000. That is the ceiling. If the seller wants $110,000, I walk away — the numbers do not work. Run your own comps through the ARV calculator to see exactly where the math lands.
Worked Example #2 — Adjusting Comps for an Atlanta Bungalow
Different market, different property type, same process.
Subject property: 4-bed/2-bath Craftsman bungalow, 1,650 sqft, built 1948
Location: East Lake neighborhood, Atlanta, GA (30317)
Condition: Needs full gut rehab — new HVAC, electrical, plumbing, kitchen, baths, roof
Post-rehab plan: Open-concept living, white shaker kitchen, quartz counters, new master bath, refinished original hardwood, new deck
Estimated rehab: $72,000
Purchase price: $195,000
East Lake has been one of Atlanta’s hottest flip markets. According to Redfin’s Data Center, the 30317 ZIP code saw a 6.2% year-over-year price increase through Q2 2026. That matters for time adjustments — a comp from 6 months ago might undervalue today’s market.
Comp Search Results (Redfin + MLS)
| Detail | Comp 1 — Oakview Rd | Comp 2 — 2nd Ave | Comp 3 — Memorial Dr | Comp 4 — Hosea Williams Dr |
|---|---|---|---|---|
| Sale price | $365,000 | $348,000 | $372,000 | $340,000 |
| Sale date | Jun 2026 | Aug 2026 | May 2026 | Jul 2026 |
| Sqft | 1,700 | 1,580 | 1,800 | 1,600 |
| Bed/bath | 4/2 | 3/2 | 4/2.5 | 3/2 |
| Year built | 1952 | 1945 | 1955 | 1940 |
| Condition | Fully renovated | Fully renovated | Fully renovated, premium | Renovated, standard |
| Distance | 0.3 miles | 0.5 miles | 0.8 miles | 0.4 miles |
Adjustments
Comp 1 — Oakview Rd ($365,000):
- Sqft: 1,700 vs 1,650 = 50 sqft larger → −$4,000 ($80/sqft, Atlanta market)
- Bed/bath: identical → $0
- Condition: similar renovation scope → $0
- Adjusted: $361,000
Comp 2 — 2nd Ave ($348,000):
- Sqft: 1,580 vs 1,650 = 70 sqft smaller → +$5,600
- Bed/bath: 3/2 vs 4/2 = missing bedroom → +$12,000
- Condition: similar → $0
- Adjusted: $365,600
Comp 3 — Memorial Dr ($372,000):
- Sqft: 1,800 vs 1,650 = 150 sqft larger → −$12,000
- Bed/bath: 4/2.5 vs 4/2 = extra half bath → −$3,500
- Condition: premium finishes (marble, custom tile) → −$8,000
- Adjusted: $348,500
Comp 4 — Hosea Williams Dr ($340,000):
- Sqft: 1,600 vs 1,650 = 50 sqft smaller → +$4,000
- Bed/bath: 3/2 vs 4/2 = missing bedroom → +$12,000
- Condition: standard reno (builder-grade) vs mid-range plan → +$4,000
- Adjusted: $360,000
Final ARV Calculation
Adjusted comps: $361,000 + $365,600 + $348,500 + $360,000 = $1,435,100
ARV = $1,435,100 ÷ 4 = $358,775
Rounded: ARV = $358,000 (conservative)
With ARV at $358,000, purchase at $195,000, and rehab at $72,000, let me check profitability using the fix and flip calculator:
Gross profit = $358,000 − $195,000 − $72,000 = $91,000
Selling costs (8%): $28,640
Holding costs (5 months × $1,800/mo): $9,000
Net profit = $91,000 − $28,640 − $9,000 = $53,360
ROI = $53,360 ÷ ($195,000 + $72,000) = 20.0%
That is a solid deal. But notice how much hinges on the ARV being accurate. If the real ARV turns out to be $330,000 instead of $358,000, the net profit drops to $25,360 — still acceptable, but barely. Always run a downside scenario at 5–8% below your estimated ARV. For a full walkthrough of flip profitability math, read the fix and flip guide.
How to Adjust Comps: Price Per Sqft, Bed/Bath, Garage, Condition
Adjustments are the skill that separates experienced flippers from amateurs. The idea is straightforward: you adjust the comp’s price so it reflects what that comp would have sold for if it were identical to your subject property. If the comp is better than your subject, subtract. If the comp is worse, add.
Price-Per-Square-Foot Adjustment
The most common adjustment. Find the local price per sqft for renovated homes (Redfin and Zillow both show this in market stats), then multiply by the sqft difference.
- Budget markets (Cleveland, Detroit, Memphis): $40–$60/sqft
- Mid-range markets (Atlanta, Charlotte, Indianapolis): $70–$100/sqft
- High-cost markets (Austin, Denver, Nashville): $120–$180/sqft
Example: comp is 1,500 sqft, subject is 1,350 sqft, local rate is $75/sqft. Comp is 150 sqft larger → subtract 150 × $75 = $11,250 from comp price.
Bedroom and Bathroom Adjustments
Bedrooms and bathrooms add value, but not equally:
- Extra bedroom: $8,000–$15,000 depending on market (higher in family neighborhoods)
- Extra full bathroom: $5,000–$10,000
- Extra half bathroom: $2,500–$5,000
These numbers come from appraisal paired-sales analysis. The National Association of Realtors (NAR) publishes annual data on the value contribution of specific home features.
Garage Adjustment
- No garage vs 1-car: $6,000–$12,000
- 1-car vs 2-car: $5,000–$10,000
- Detached vs attached: $2,000–$5,000 (attached is worth more)
Condition / Renovation Level
This is the trickiest adjustment because it is subjective. I break renovation quality into three tiers:
- Basic update: Paint, carpet, basic fixtures, laminate counters — add $0–$5,000 if comp is basic and your plan is mid-range
- Mid-range reno: Granite or quartz counters, LVP or hardwood, tile showers, updated cabinets
- Premium reno: Custom cabinets, marble, designer fixtures, smart home — subtract $5,000–$15,000 if comp is premium and your plan is mid-range
Always look at photos. “Updated” in the listing description means nothing without visual confirmation. For a full breakdown of rehab cost tiers, see the cost to rehab a house guide.
ARV Mistakes That Cost Flippers $20,000+
I have made some of these mistakes personally. Others I have watched fellow investors make on deals that went sideways. Here are the errors that cost real money:
Mistake #1: Using Listing Prices Instead of Sold Prices
A property listed at $320,000 means nothing until it closes. It might sell for $305,000, $290,000, or not at all. Only use closed sale prices for ARV comps. Listing prices reflect what a seller hopes to get — sold prices reflect what the market actually pays. I have seen new flippers base their entire deal analysis on active listings and then wonder why their property sits on the market for 90 days.
Mistake #2: Cherry-Picking the Highest Comp
If your 4 comps adjust to $190K, $188K, $201K, and $192K, the ARV is around $193K — not $201K. That outlier might be a sale with unusual circumstances (motivated buyer, bidding war, seller concessions baked in). Using the average or, better yet, the median protects you from outlier bias. Conservative flippers drop the highest and lowest comp and average the middle ones.
Mistake #3: Ignoring Market Direction
A comp that sold 5 months ago in a declining market is worth less than its sale price today. A comp from 5 months ago in a rising market is worth more. Check Zillow Research or Redfin’s Data Center for your market’s price trend. If prices are dropping 0.5% per month, a comp from 5 months ago needs a 2.5% downward adjustment. I skipped this on a deal in early 2023 when rates were spiking, and it cost me about $14,000 in expected margin.
Mistake #4: Comparing Unrenovated to Renovated Sales
Your ARV is the after-repair value — so every comp should be in renovated condition. If you pull a comp that sold at $160,000 in as-is condition, that tells you what the property is worth before rehab, not after. Mix up pre-rehab and post-rehab comps and your ARV estimate will be wildly inaccurate.
Mistake #5: Crossing Neighborhood Boundaries
Two streets can be 0.3 miles apart and in completely different value zones. Railroad tracks, highways, school district lines, and flood zone boundaries create invisible walls between neighborhoods. In Cleveland, homes north of Lorain Avenue in West Park trade at $15–$20K more than homes south of it — same distance, same zip code, different buyer pool. Always confirm your comps are on the same side of any major dividing line.
Mistake #6: Not Accounting for Lot Size Differences
This one bites suburban and rural flippers. A comp on a 0.5-acre lot is worth more than the same house on a 0.15-acre lot. In metro areas, lot size premiums run $2,000–$5,000 per 0.1 acre. In suburban and semi-rural areas, the premium can reach $8,000–$15,000. If your subject is on a standard city lot and the comp sits on a double lot, you need to adjust downward.
Avoiding these errors is the difference between consistent 15–20% ROI flips and the kind of deal that makes you question your career choices. The beginner flipper guide covers more pitfalls to watch for.
When to Trust Your ARV (and When to Walk Away)
Not every deal passes the ARV confidence test. Here is how I think about it:
Trust Your ARV When:
- You have 3+ comps within 0.5 miles, all sold in the last 4 months
- Adjusted values are tightly clustered (within 5% of each other)
- All comps are arm’s-length sales of renovated properties
- Your price-per-sqft is consistent across comps (±$10/sqft)
- Market trends support your estimate (flat or rising prices)
Walk Away (or Reduce Your Offer) When:
- Comps are scattered — adjusted values range from $170K to $220K
- You had to go beyond 1.5 miles or 9 months to find 3 comps
- The best comp is a foreclosure or short sale
- Market data shows declining prices in the ZIP code
- Your property has a unique feature (commercial zoning, odd layout, environmental issue) with no true comparable
A spread of more than 10% between your highest and lowest adjusted comp means your ARV confidence is low. On those deals, I use the lowest adjusted comp as my ARV and run the numbers from there. If the deal still works at the conservative number, I proceed. If it only works at the optimistic number, I pass.
You can stress-test any deal by plugging both your conservative and optimistic ARV into the ARV calculator, then running the results through the fix and flip calculator to see how profit changes. If a 5% drop in ARV kills the deal, the margin is too thin.
How to Find ARV: Frequently Asked Questions
How many comps do I need to estimate ARV accurately?
Three comps is the minimum for a reliable ARV estimate. Appraisers typically use 3–5. Using fewer than 3 gives you no way to spot outliers or identify a trend. If all 3 adjusted values land within 3–5% of each other, your estimate is strong. Four or five comps add extra confidence, but beyond 5 you risk including weaker comparables that dilute accuracy. Start with 3 tight comps and add a 4th only if it genuinely matches your subject.
Can I use Zillow’s Zestimate as my ARV?
No. The Zestimate is an automated valuation model (AVM) that estimates current market value — not after-repair value. It does not account for your specific renovation plan, and Zillow’s own data shows a median error rate of about 2.4% for on-market homes and 7.5% for off-market homes. A 7.5% error on a $250,000 property is $18,750 — more than enough to wreck a flip’s profit. Use Zillow to find comp data, but calculate ARV yourself using adjusted comps. The ARV calculator guide shows how.
How do I find ARV if there are no recent renovated sales nearby?
Start by widening your search: expand the time window to 9 months, then the radius to 1.5 miles. If you still cannot find renovated comps, look for properties that sold twice within 12 months — the first sale was likely a distressed purchase and the second was the post-flip sale. That second sale is your comp. You can also talk to local agents who specialize in flips; they often know about recent sales not yet reflected in public data. As a last resort, find unrenovated sales and add the estimated value of renovations — but this method is less reliable and should be confirmed by at least one actual renovated sale.
Should I adjust ARV for the time of year I plan to sell?
Yes, seasonal adjustments matter. According to the U.S. Census Bureau’s housing data, home sales peak in May–July and dip in November–January. The price difference between peak and trough seasons averages 5–8% in most metro areas. If your comps sold in June and you plan to list in January, consider adjusting your ARV down by 3–5%. Conversely, if comps sold in winter and you are listing in spring, your ARV might be slightly conservative. Factor the seasonal cycle into your holding period and listing timeline.
What is the difference between ARV and appraised value?
ARV is your pre-purchase estimate of what a property will be worth after renovations. Appraised value is the figure a licensed appraiser assigns, typically during the buyer’s mortgage process or a cash-out refinance. They use similar methods — both rely on comparable sales and adjustments — but an appraisal is a formal, regulated opinion of value at a specific point in time. Your ARV estimate should be close to the eventual appraised value if your comps were solid. The risk is that an appraiser might select different comps or apply different adjustments, so always build a 3–5% cushion into your ARV estimate. For BRRRR investors, the appraised value at refinance determines cash-out proceeds — read the after repair value guide for details.
Related Calculators and Guides
Finding ARV is step one. Here are the tools and resources to take your analysis further:
- ARV Calculator — plug in your comps and get an instant after-repair value estimate with sensitivity analysis
- Fix and Flip Calculator — calculate total profit, ROI, and holding costs for any flip deal
- 70% Rule Calculator — find your maximum offer price based on ARV and rehab costs
- How to Use the ARV Calculator — step-by-step walkthrough of the calculator interface
- Find ARV by Address — look up ARV using a specific property address
- Cost to Rehab a House — line-item rehab cost breakdowns by project type
- Fix and Flip Guide — full walkthrough from deal sourcing to closing
- How to Flip a House: Beginner Guide — start-to-finish roadmap for first-time flippers
- 70% Rule Guide — when the 70% rule works and when to adjust it
Leave a Reply