Success: Updated custom field ‘_thumbnail_id’.
The 1 percent rule says a rental property should rent for at least 1% of its purchase price per month — $1,500/month on a $150,000 property. It is the fastest screening tool in real estate investing: check the ratio in 10 seconds, skip deals that fail, and spend your analysis time only on deals that pass. But in 2026, the 1 percent rule is harder to hit than ever. This guide explains what the rule actually measures, where it still works, where it fails, and the smarter alternatives investors use today — with data from 15 markets and worked examples.
What Is the 1 Percent Rule in Real Estate?
The 1 percent rule is a quick screening formula:
Monthly Rent ÷ Purchase Price ≥ 1%

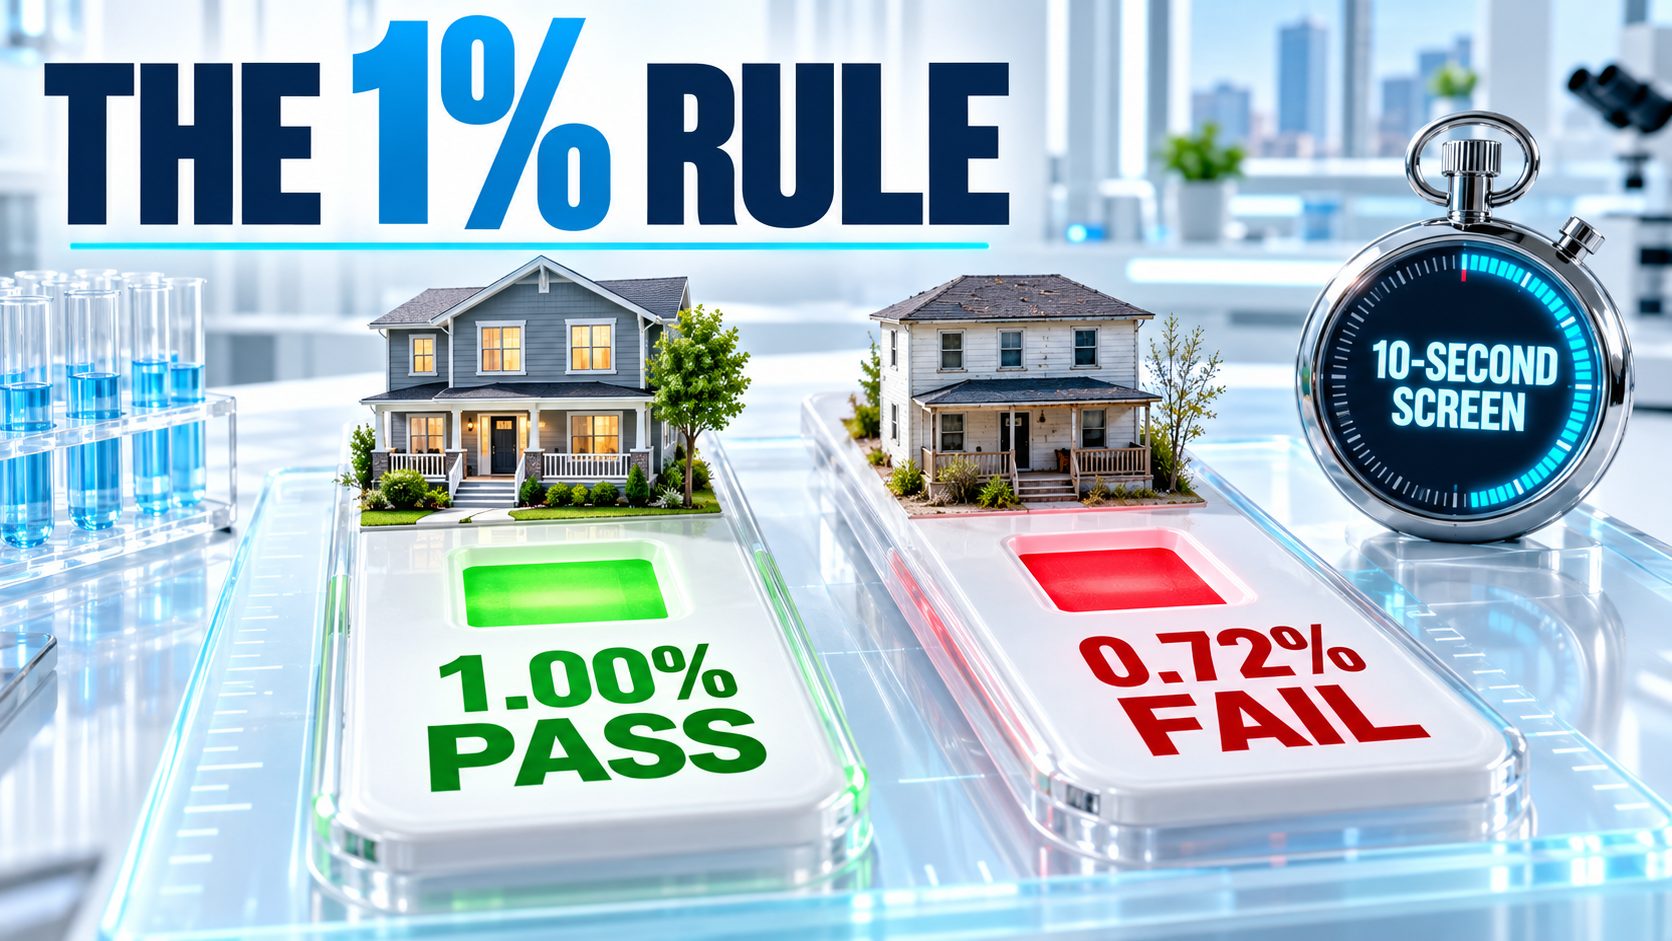
Example: $1,400/mo rent ÷ $140,000 purchase = 1.0% ✓ PASSES
Example: $1,800/mo rent ÷ $250,000 purchase = 0.72% ✗ FAILS
If the property meets or exceeds 1%, it is worth deeper analysis. If it falls below 1%, the property is unlikely to produce positive cash flow with conventional financing — skip it and move on.
The rule is a screening tool, not an analysis. Passing the 1 percent rule does not guarantee a good deal. It means the rent-to-price ratio is high enough that cash flow is possible after expenses. You still need to run a full analysis with vacancy, repairs, management, and CapEx. Use the rental property calculator for the complete picture.
The 1 Percent Rule vs. the 2 Percent Rule
There are actually two versions of this screening test:
| Rule | Formula | What It Means | Where It Works |
|---|---|---|---|
| 1% Rule | Rent ≥ 1% of price | Minimum for possible cash flow with financing | Most Midwest and Southeast markets |
| 2% Rule | Rent ≥ 2% of price | Strong cash flow likely even with high expenses | Low-price, high-rent markets (rare in 2026) |
The 2 percent rule is the aggressive version. A $100K property renting for $2,000/month (2%) will almost certainly cash flow — but these deals are rare in 2026 and typically come with trade-offs: high-crime neighborhoods, heavy deferred maintenance, or unreliable tenant bases. Per FRED median home price data, the national median home price is $420K+ while median rent is ~$2,100 — a 0.5% ratio. Finding 1% deals requires targeting specific markets.
The 1 Percent Rule by City: 2026 Data
Not all markets are equal. Here is the rent-to-price ratio across 15 US markets based on Census ACS housing data and Zillow Research rental data — showing where the 1 percent rule still works and where it is mathematically impossible.
| City | Median Price | Median Rent | Rent/Price Ratio | Passes 1%? |
|---|---|---|---|---|
| Cleveland, OH | $125,000 | $1,250 | 1.00% | ✓ Yes |
| Indianapolis, IN | $165,000 | $1,350 | 0.82% | Close |
| Memphis, TN | $155,000 | $1,300 | 0.84% | Close |
| Fort Wayne, IN | $135,000 | $1,100 | 0.81% | Close |
| Birmingham, AL | $140,000 | $1,200 | 0.86% | Close |
| Kansas City, MO | $195,000 | $1,400 | 0.72% | ✗ No |
| Columbus, OH | $230,000 | $1,500 | 0.65% | ✗ No |
| Charlotte, NC | $310,000 | $1,650 | 0.53% | ✗ No |
| Nashville, TN | $390,000 | $1,900 | 0.49% | ✗ No |
| Atlanta, GA | $340,000 | $1,750 | 0.51% | ✗ No |
| Dallas, TX | $350,000 | $1,800 | 0.51% | ✗ No |
| Austin, TX | $430,000 | $1,950 | 0.45% | ✗ No |
| Denver, CO | $520,000 | $2,100 | 0.40% | ✗ No |
| San Diego, CA | $800,000 | $2,800 | 0.35% | ✗ No |
| San Francisco, CA | $1,200,000 | $3,200 | 0.27% | ✗ No |
The pattern is clear: the 1 percent rule only works in markets with median prices under $170K. Once prices exceed $200K, the ratio drops below 0.7% and cash flow becomes impossible without significant down payment or value-add strategy.
Cleveland is the standout at exactly 1.0%. Indianapolis, Memphis, Fort Wayne, and Birmingham cluster around 0.8–0.86% — they do not hit 1% at the median, but individual deals within these markets regularly exceed 1% in B-class neighborhoods.
Check rent-to-price ratios for any market in the cap rate calculator and compare cities in our best states for rental property guide.
Does the 1 Percent Rule Still Work in 2026?
The honest answer: the 1 percent rule works as a screening tool but fails as an investment thesis.
Why It Still Works (as a Screen)
The rule eliminates 80% of bad deals in 10 seconds. If a property rents for 0.5% of purchase price, no amount of expense optimization will make it cash flow with a mortgage. You would need 50%+ down payment to break even. The 1% screen saves you hours of analysis on properties that were never going to work.
Why It Fails (as the Only Test)
A property can pass the 1% rule and still lose money. Here is why:
Property: Cleveland SFR, $120K, $1,250/mo rent
Rent/Price: 1.04% ✓ PASSES the 1% rule

But run the full analysis:
  Gross rent:           $1,250/mo
  Vacancy (7%):         -$88
  PITI (25% down):      -$685
  Repairs (10%):        -$125
  PM (9%):              -$101
  CapEx (5%):           -$63
  Total expenses:       -$1,062

  Cash flow:            $188/mo ✓ (with 25% down)

Same property, 5% down (FHA):
  PITI (5% down):       -$895
  Same other expenses:  -$377
  Cash flow:            -$22/mo ✗ (NEGATIVE with low down payment)
The 1% rule passed, but the deal only works with 25% down. With 5% down, the higher mortgage payment eats the cash flow. The 1% rule does not account for financing terms — and financing is what determines whether a passing deal actually produces cash.
What Smart Investors Use Instead
The 1% rule is step 1 of a 3-step screening process:
- Step 1 — 1% Rule screen: Does the property meet 1%? If no, skip. If yes, continue
- Step 2 — 50% Rule estimate: Assume 50% of gross rent goes to operating expenses (vacancy, repairs, PM, CapEx, insurance, taxes). Is the remaining 50% enough to cover the mortgage? If no, skip
- Step 3 — Full analysis: Run the deal through a rental property calculator with real numbers for every expense line. This is the only step that gives you an actual cash flow number
This 3-step process lets you screen 20 deals in an hour and identify the 2–3 worth deep analysis.
Historical Context: When the 1 Percent Rule Was Easy
From 2010 to 2018, the 1 percent rule was achievable in 30–40% of US metros. Median home prices were $180K–$250K nationally, mortgage rates were 3.5–4.5%, and rents were climbing steadily post-recession. An investor could find 1%+ deals in Columbus, Charlotte, Atlanta, and even parts of Phoenix — markets that now sit at 0.5–0.65%.
What changed: home prices rose 60–80% from 2018 to 2026 in most metro areas, while rents rose only 25–35%. This compressed the rent-to-price ratio across the board. At the same time, mortgage rates doubled from 3.5% to 7%+, making financing costs much higher. The 1 percent rule has not changed — the markets have.
In 2026, only about 10–15% of US metros pass the 1 percent rule at the median price point. These are concentrated in the Midwest (Ohio, Indiana) and parts of the Southeast (Tennessee, Alabama, Mississippi). Coastal and Sun Belt markets that worked in 2015 no longer qualify.
How Interest Rates Changed the 1 Percent Rule
The 1% rule was created during an era of 4% mortgage rates. At 4%, a $150K property with 25% down has a monthly PITI of ~$680. At 7.5% (2026 rates), the same property has PITI of ~$880 — a $200/month increase that directly reduces cash flow.
$150K property, $1,500/mo rent (1.0%), 25% down:

At 4.0% rate: PITI $680 → estimated cash flow $120/mo ✓
At 5.5% rate: PITI $760 → estimated cash flow $40/mo ⚠ thin
At 7.0% rate: PITI $855 → estimated cash flow -$55/mo ✗
At 7.5% rate: PITI $880 → estimated cash flow -$80/mo ✗

To cash flow at 7.5%, you need 1.15-1.2% ratio — not 1.0%.
The updated rule for 2026: At current interest rates, target 1.1–1.2% instead of 1.0%. The old 1% threshold is no longer sufficient to guarantee positive cash flow with conventional 25% down financing.
1 Percent Rule Screening Workflow: Zillow to Calculator in 5 Minutes
Here is the exact workflow to screen deals using the 1 percent rule. No software needed — just Zillow and a calculator.
Step 1: Set Up Your Zillow Search (2 minutes)
- Go to Zillow → filter by your target city
- Set price range: $80K–$180K (the range where 1% is achievable)
- Filter: 2–4 units (multifamily), or SFR with 3+ bedrooms
- Sort by: newest listings (freshest deals)
Step 2: Quick 1% Screen (1 minute per property)
- For each listing, estimate monthly rent. Use rent estimator by ZIP code or Zillow’s rent estimate
- Divide rent by listing price. If ≥ 1.1%, mark it for analysis. If < 0.9%, skip immediately
- Between 0.9–1.1%: borderline — save for later if you run out of 1%+ deals
Step 3: Full Analysis on Passing Deals (3 minutes per property)
- Open the rental property calculator
- Enter: purchase price, rent, down payment, interest rate, property tax (from county records), insurance estimate, vacancy rate, PM rate, repairs %
- Check: cash flow positive? Cash-on-cash above 5%? If yes, schedule a showing
This workflow lets you screen 15–20 properties in an hour. Most investors find 2–3 deals worth pursuing per session.
Worked Example: 1 Percent Rule Screening in Cleveland
Here is how the screening process works in practice. Five properties, screened in under 5 minutes.
SCREENING 5 DEALS:

Deal A: $95K, $1,050/mo rent → 1.11% ✓ PASS → analyze
Deal B: $145K, $1,200/mo rent → 0.83% ✗ FAIL → skip
Deal C: $110K, $1,150/mo rent → 1.05% ✓ PASS → analyze
Deal D: $185K, $1,400/mo rent → 0.76% ✗ FAIL → skip
Deal E: $125K, $1,300/mo rent → 1.04% ✓ PASS → analyze

3 pass, 2 fail. Now run full analysis on A, C, and E only.

FULL ANALYSIS — Deal A ($95K, $1,050/mo):
  Down payment (25%): $23,750
  Loan: $71,250 at 7.5%, 30yr
  PITI: $625/mo
  Vacancy (7%): -$74
  Repairs (10%): -$105
  PM (9%): -$95
  CapEx (5%): -$53
  Total expenses: $952
  Cash flow: $98/mo → CoC: 5.0% ✓ BUY

FULL ANALYSIS — Deal C ($110K, $1,150/mo):
  Down payment: $27,500
  PITI: $720/mo
  Operating expenses: -$349
  Total: $1,069
  Cash flow: $81/mo → CoC: 3.5% ⚠ THIN

FULL ANALYSIS — Deal E ($125K, $1,300/mo):
  Down payment: $31,250
  PITI: $815/mo
  Operating expenses: -$399
  Total: $1,214
  Cash flow: $86/mo → CoC: 3.3% ⚠ THIN
Result: Out of 5 deals, the 1% rule eliminated 2 instantly. Of the 3 that passed, only Deal A produces a meaningful cash-on-cash return (5.0%). Deals C and E pass the 1% rule but barely cash flow — they are not worth the risk at 3.3–3.5% CoC.
Run your own screening in the rental property calculator and check cash-on-cash in the cash-on-cash calculator.
The 50 Percent Rule: A Better Quick Estimate
The 50 percent rule is a companion to the 1% rule. It estimates that 50% of gross rent goes to operating expenses (everything except the mortgage): vacancy, repairs, maintenance, property management, CapEx, insurance, property tax.
50% Rule Formula:
  Cash Flow = (Gross Rent × 50%) - Mortgage Payment

Example: $1,400/mo rent, $850/mo mortgage
  ($1,400 × 50%) - $850 = $700 - $850 = -$150/mo ✗

Example: $1,400/mo rent, $580/mo mortgage (larger down payment)
  ($1,400 × 50%) - $580 = $700 - $580 = $120/mo ✓
The 50% rule is more accurate than the 1% rule because it includes operating expenses. But it is still an estimate — actual expenses can range from 35% (newer property, low-tax state) to 60% (older property, high-tax state like Texas or New Jersey).
Use both rules together: 1% rule for initial screening, 50% rule for quick cash flow estimate, full calculator for the final decision.
When to Ignore the 1 Percent Rule
The 1% rule is not universal. There are legitimate investment strategies where it does not apply:
1. Appreciation Markets
If you are buying in Austin, Nashville, or Denver for long-term appreciation, you will not hit 1%. These markets run at 0.4–0.5%. The investment thesis is different: you accept break-even or slightly negative cash flow in exchange for 5–8% annual appreciation. This is a valid strategy — but only with a long hold period (10+ years) and financial reserves to cover negative months.
2. BRRRR Strategy
In a BRRRR deal, you buy below market, renovate, rent, refinance, and repeat. The purchase price is artificially low because you are buying a distressed property. After rehab, the “real” value is much higher. The 1% rule applied to the purchase price may show 1.5–2%, but applied to the after-repair value (the real metric), it may only be 0.7%. Use the BRRRR calculator instead.
3. Short-Term Rentals
Airbnb and STR properties generate 2–3× the monthly income of long-term rentals. A property that fails the 1% rule at $1,500/month long-term rent may produce $3,500/month as an STR — well above 1%. But STR income is seasonal and management-intensive. Estimate STR income in the Airbnb calculator.
4. Value-Add Multifamily
Properties with below-market rents that can be raised after renovation. You buy at a 0.7% ratio, renovate, raise rents, and the ratio improves to 0.9–1.0%+. The 1% rule applies to the post-renovation numbers, not the acquisition numbers. Analyze in the multifamily calculator.
Common Mistakes When Using the 1 Percent Rule
1. Using Listing Price Instead of All-In Cost
The 1% rule should use your total acquisition cost: purchase price + closing costs + any immediate repairs. A $140K property with $5K closing costs and $10K in deferred maintenance is really a $155K property. At $1,400/month rent: $1,400 ÷ $155,000 = 0.90% — below 1%.
2. Using Asking Rent Instead of Market Rent
Sellers and listing agents inflate rental estimates. “This could rent for $1,600/month” may be $1,350 in reality. Use actual comparable rents from Zillow, Rentometer, or local property managers — not the seller’s projection. Check rents in the rent estimator.
3. Assuming 1% Means Profitable
The biggest misconception. A property at 1.0% with a 7.5% interest rate, 10% property tax rate (like Texas), and high insurance (like Florida) may still produce negative cash flow. The 1% rule was created when interest rates were 4–5%. At 7%+, you need closer to 1.1–1.2% to reliably cash flow.
4. Dismissing Sub-1% Markets Entirely
Markets at 0.7–0.9% can work with creative strategies: larger down payment (reduces mortgage), house hacking (live in one unit), or value-add (raise rents post-renovation). The house hacking guide shows how to make sub-1% markets work by eliminating your housing cost.
5. Chasing 2% Deals in War Zones
A property at $60K renting for $1,200/month (2.0%) looks incredible on paper. But 2% deals in 2026 almost always come from C/D neighborhoods with high crime, chronic vacancy, tenant damage, and deferred maintenance. The extra cash flow is consumed by 15–20% vacancy rates, $3,000–$5,000/year repair costs, and frequent turnover. A 1% deal in a B neighborhood will outperform a 2% deal in a D neighborhood over 5 years — every time. Check neighborhood vacancy in the vacancy rate calculator.
Frequently Asked Questions
What is the 1 percent rule in real estate?
The 1 percent rule states that a rental property’s monthly rent should be at least 1% of the purchase price. For example, a $150,000 property should rent for at least $1,500/month. It is a quick screening tool — not a complete analysis. Properties that pass the 1% rule are worth deeper investigation; properties that fail are unlikely to produce positive cash flow with conventional financing.
Does the 1 percent rule still work in 2026?
What is the difference between the 1% rule and the 2% rule?
What is the 50 percent rule in real estate?
Can you still find 1 percent rule properties in 2026?
Related Calculators and Guides
- Rental Property Calculator — Full cash flow analysis beyond the 1% screen
- Cap Rate Calculator — Rent-to-price and cap rate by market
- Cash-on-Cash Calculator — Return on invested cash
- Cash Flow Calculator — Monthly cash flow after all expenses
- GRM Calculator — Quick property comparison
- Rent Estimator — Market rent by ZIP code
- All 30+ Calculators
Related guides:
Leave a Reply