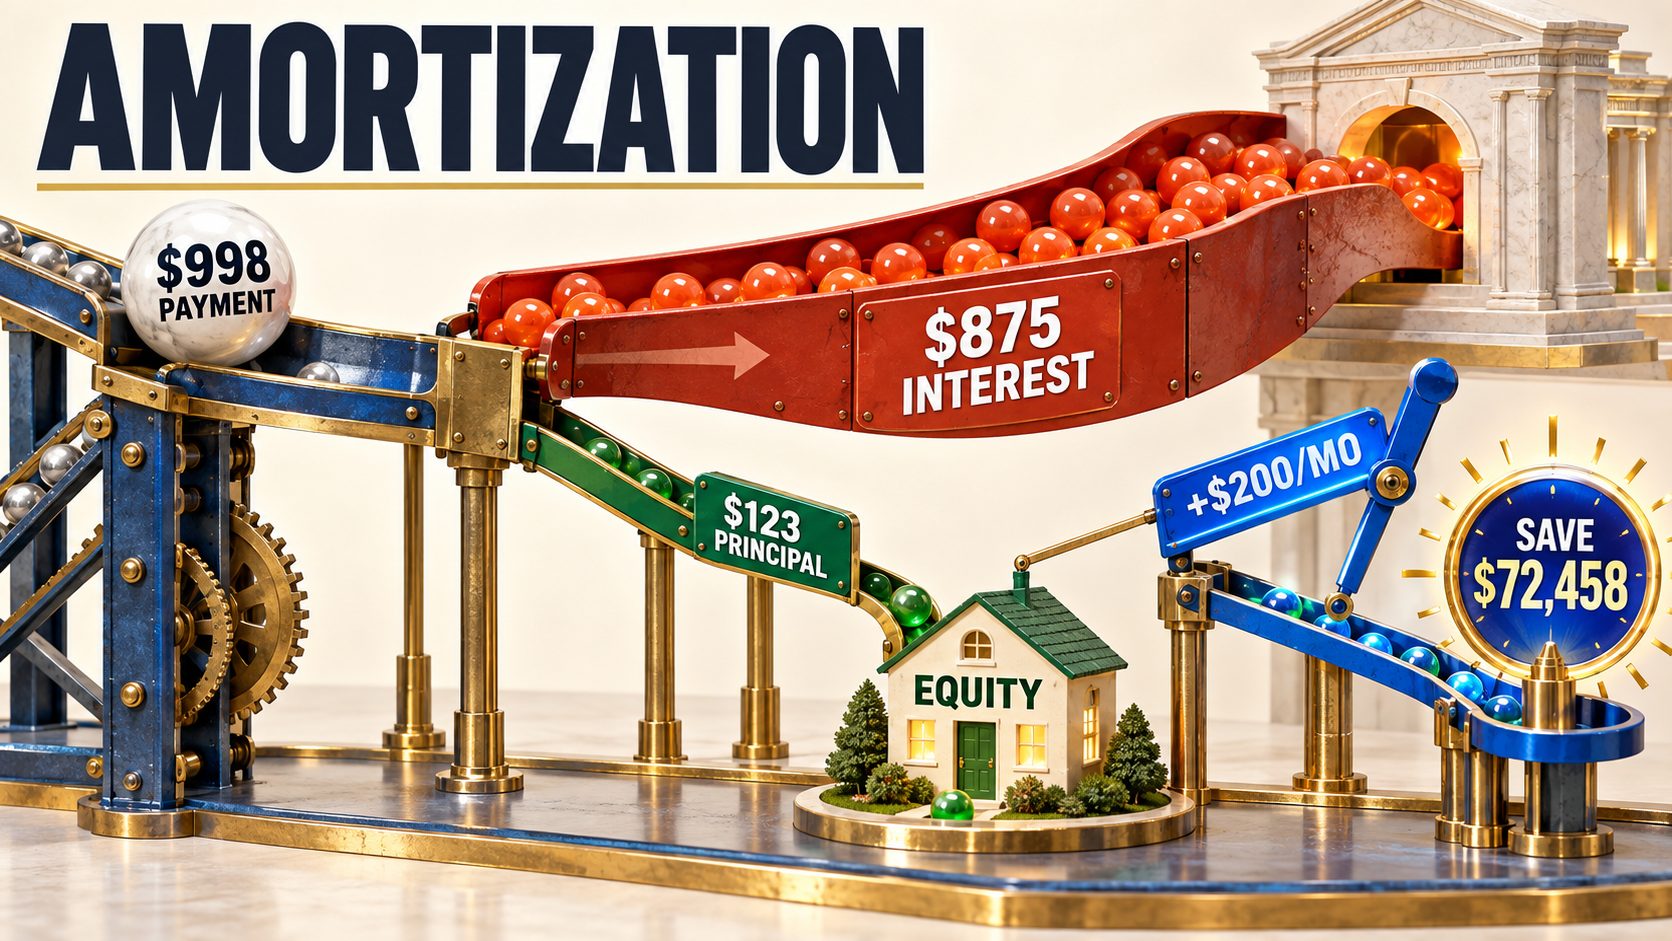
Your first mortgage payment on a $150,000 investment property at 7%: $998/month. Of that, $123 goes to principal and $875 goes to interest. You pay the bank 7× more than you pay yourself. After 12 months of payments ($11,976 total), you have reduced your loan balance by only $1,516. The other $10,460 went to interest. This is how amortization works — and why understanding your amortization schedule is critical for every real estate investor. This guide shows you how to use the amortization calculator, how to read the schedule, and how extra payments can save you $50,000–$100,000 in interest.
What Is an Amortization Schedule?
An amortization schedule is a month-by-month table showing how each mortgage payment is split between principal (reducing your loan balance) and interest (paying the bank for borrowing). Over the life of a 30-year loan, the split shifts dramatically: early payments are 85–90% interest, while final payments are 95%+ principal.
For real estate investors, the amortization schedule answers three critical questions:
- How much equity am I building each year? — Principal paydown is forced equity. On a $150K loan at 7%, you build $1,516 in equity the first year and $2,876 by year 5. This matters for refinancing (BRRRR) and net worth tracking
- How much total interest will I pay? — On a $150K / 30-year / 7% loan: $209,263 in total interest. You pay 1.4× the loan amount just in interest. Knowing this number changes how you evaluate deals
- How much do extra payments save? — An extra $200/month on that same loan saves $72,458 in interest and pays off the loan 10 years early. The amortization schedule shows you exactly when and how
Generate your full schedule in the amortization calculator.
How to Use the Amortization Schedule Calculator: Step by Step
Step 1: Enter Loan Details
- Loan Amount: The mortgage amount after down payment. $200K property with 25% down = $150,000 loan. Do not enter the property price — enter the loan amount
- Interest Rate: Your annual rate. In 2026, investment property rates are 7.0–8.0% conventional, 7.5–9.0% DSCR. Owner-occupied (house hack) rates are 6.5–7.0%. Per Freddie Mac PMMS, check current rates before calculating
- Loan Term: 30 years is standard. 15-year loans have higher payments but save 55–60% in total interest. Some DSCR loans are 25 years — enter the exact term
- Start Date: Month and year your payments begin. The schedule generates dates for each payment (Jan 2027, Feb 2027, etc.)
Step 2: Choose Your Mode
The calculator has three modes:
- Mode 1 — Standard Schedule: Full month-by-month amortization table. See how each payment splits between principal and interest, track your declining balance, view yearly summaries
- Mode 2 — Extra Payments: Add a monthly or annual extra payment. The calculator shows how many months you save, how much interest you avoid, and your new payoff date. This is the mode most investors should use
- Mode 3 — Refinance Compare: Enter your current loan terms and proposed new terms. See the monthly savings, breakeven month (when savings exceed closing costs), and total net savings
Step 3: Read the Results
The results panel shows:
- Monthly Payment (P&I): Principal and interest only — does not include taxes and insurance
- Total Interest: How much you pay the bank over the life of the loan. On a $150K / 30-year / 7% loan: $209,263
- Total Cost: Principal + total interest = what you actually pay. $150,000 + $209,263 = $359,263
- Interest as % of Loan: Total interest divided by loan amount. At 7%, this is 139% — you pay 1.39× the loan in interest alone
- Payoff Date: When the last payment is due
Step 4: Read the Amortization Table
The table is the core feature. Click any year row to expand monthly detail:
- Year rows (gray): Annual summary — total principal paid, total interest, ending balance
- Month rows (white): Each payment broken down — payment amount, principal portion (green), interest portion (red), remaining balance
- Extra Payment column: Visible in Mode 2 — shows extra amounts applied to principal
Amortization Schedule: Worked Example — $150K Investment Property Loan
A real 30-year amortization at 7% — the most common investment property scenario in 2026.
LOAN DETAILS:
  Loan Amount:    $150,000
  Interest Rate:  7.0%
  Term:           30 years (360 months)
  Monthly Payment: $998/month (P&I)

YEAR 1 BREAKDOWN:
  Month   Payment   Principal   Interest    Balance
  ─────   ───────   ─────────   ────────    ────────
  1       $998      $123        $875        $149,877
  2       $998      $124        $874        $149,753
  3       $998      $125        $873        $149,628
  ...
  12      $998      $132        $866        $148,484

  Year 1 totals:
    Payments:   $11,976
    Principal:  $1,516  (12.7% of payments)
    Interest:   $10,460 (87.3% of payments)
    Balance:    $148,484

YEAR 5 BREAKDOWN:
  Year 5 totals:
    Principal:  $1,788
    Interest:   $10,188
    Balance:    $141,895

YEAR 10:
    Principal:  $2,568
    Interest:   $9,408
    Balance:    $130,432

YEAR 20:
    Principal:  $5,304
    Interest:   $6,672
    Balance:    $90,432

YEAR 30 (final):
    Principal:  $11,808
    Interest:   $168
    Balance:    $0

LIFETIME TOTALS:
  Total payments:  $359,263
  Total principal: $150,000
  Total interest:  $209,263
  Interest/Loan:   139.5%
Amortization Schedule Summary Table
| Year | Annual Principal | Annual Interest | Principal % | Ending Balance | Cumulative Equity |
|---|---|---|---|---|---|
| 1 | $1,516 | $10,460 | 12.7% | $148,484 | $1,516 |
| 5 | $1,788 | $10,188 | 14.9% | $141,895 | $8,105 |
| 10 | $2,568 | $9,408 | 21.4% | $130,432 | $19,568 |
| 15 | $3,684 | $8,292 | 30.7% | $114,684 | $35,316 |
| 20 | $5,304 | $6,672 | 44.3% | $90,432 | $59,568 |
| 25 | $7,620 | $4,356 | 63.6% | $52,440 | $97,560 |
| 30 | $11,808 | $168 | 98.6% | $0 | $150,000 |
Key insight: In year 1, only 12.7% of your payments go to principal. By year 20, it flips to 44.3%. By year 30, payments are 98.6% principal. The amortization schedule front-loads interest — this is by design, and it is why investors who sell in years 1–5 build very little equity from payments alone.
Generate your own schedule in the amortization calculator.
Amortization Schedule: How Extra Payments Save $72,000 in Interest
The most powerful use of the amortization calculator: modeling extra payments. Even small amounts create massive savings because they reduce principal early — when interest charges are highest.
SCENARIO: $150K loan at 7%, 30 years

WITHOUT extra payments:
  Monthly payment:    $998
  Total interest:     $209,263
  Payoff:             360 months (30 years)

WITH $200/month extra:
  Monthly payment:    $998 + $200 = $1,198
  Total interest:     $136,805
  Payoff:             242 months (20.2 years)

SAVINGS:
  Interest saved:     $72,458
  Time saved:         118 months (9.8 years)
  Total extra paid:   $200 × 242 = $48,400
  Net savings:        $72,458 - $48,400 = $24,058

  You pay $48,400 in extra payments and save $72,458 in interest.
  Every $1 of extra payment saves $1.50 in interest.
The math is counterintuitive: you pay $48,400 extra but save $72,458. This is because each extra dollar reduces principal immediately, which reduces every future interest calculation for the remaining life of the loan. The earlier you start, the more you save.
When Extra Payments Make Sense for Investors
Extra payments are not always the best use of cash for real estate investors. Compare the return on extra payments vs. alternative uses:
| Use of $200/month | Annual Return | Best When |
|---|---|---|
| Extra mortgage payment (7% loan) | ~7% guaranteed (interest savings) | You have no better use for the cash, loan rate is high |
| Save for next down payment | Varies (next deal’s ROI) | Cash-on-cash on next deal exceeds your loan rate |
| CapEx/repair reserve | Loss prevention | Reserve is below 3 months of expenses |
| Index fund investment | ~10% historical average | Long time horizon, comfortable with volatility |
Rule of thumb: If your mortgage rate is above 6%, extra payments are competitive with most alternative investments. Below 5%, your money is likely better deployed elsewhere (next property, index fund). At 7%+ (typical 2026 investment property rate), extra payments are a strong guaranteed return.
Amortization Schedule and the BRRRR Strategy
For BRRRR investors, the amortization schedule is a planning tool for the refinance step. You need to know your loan balance at the refinance date to calculate:
- Equity position: Property value (after rehab) minus remaining loan balance = available equity
- Cash-out amount: New loan (75% of appraised value) minus old loan balance = cash back
- DSCR on new loan: Monthly rent ÷ new monthly PITI
BRRRR EXAMPLE:
  Purchase: $120K, hard money loan at 12% interest-only
  Rehab: $30K (6 months)
  ARV after rehab: $180K

  After 6 months:
    Hard money balance: $120K (interest-only, no paydown)
    Hard money interest paid: $120K × 12% × 0.5 = $7,200

  Refinance into conventional at 75% LTV:
    New loan: $180K × 75% = $135K
    Pay off hard money: -$120K
    Cash back: $15K (partial rehab recovery)

  New amortization (30yr at 7.5%):
    Monthly P&I: $944
    Year 1 principal paydown: $1,290
    Year 1 interest: $10,038
    Balance after year 1: $133,710
The amortization schedule shows that after refinancing, you build $1,290 in equity from payments in year 1 — plus whatever the property appreciates. Model this in the BRRRR calculator and generate the post-refi amortization in the amortization calculator.
15-Year vs. 30-Year Amortization Schedule for Investment Property
Should investors use 15-year or 30-year loans? The amortization schedule reveals the trade-off clearly.
| Factor | 30-Year at 7% | 15-Year at 6.5% |
|---|---|---|
| Loan amount | $150,000 | $150,000 |
| Monthly P&I | $998 | $1,307 |
| Total interest | $209,263 | $85,209 |
| Interest saved | — | $124,054 (59% less) |
| Year 1 principal | $1,516 | $5,598 |
| Year 5 equity (payments) | $8,105 | $31,746 |
| Monthly cash flow impact | Higher (+$309/mo) | Lower (-$309/mo) |
| DSCR impact | Better (lower payment) | Worse (higher payment) |
The 15-year loan saves $124,054 in interest and builds equity 3.9× faster. But the monthly payment is $309 higher — which can push cash flow negative on many rental properties. Most investors choose 30-year for cash flow and use extra payments strategically to accelerate payoff when cash flow allows.
Compare both scenarios in the amortization calculator.
How Amortization Affects Your Equity and Net Worth
Mortgage amortization is one of three equity-building forces in real estate:
- Principal paydown (amortization): Your tenants’ rent pays down your mortgage. On a $150K loan, tenants pay down $8,105 in the first 5 years — equity you build with other people’s money
- Appreciation: Property values historically rise 3–4% per year. A $200K property appreciates $30K–$40K over 5 years
- Forced equity (rehab): Value added through renovation. A $30K rehab that adds $50K in value creates $20K in instant equity
Together: $8,105 (paydown) + $35,000 (appreciation) + $20,000 (rehab) = $63,105 in equity over 5 years on a $50,000 down payment. That is a 126% return — not counting cash flow.
Track your total return in the ROI calculator.
Common Amortization Schedule Mistakes Investors Make
1. Confusing Monthly Payment with Monthly Cost
Your amortization payment ($998) is P&I only. Your actual monthly cost includes property tax ($200+), insurance ($150+), PM ($120+), vacancy ($100+), repairs ($150+). Total: $1,718+. The amortization schedule shows one piece of the puzzle — use the rental property calculator for the full picture.
2. Thinking Principal Paydown Is Cash Flow
First-year principal paydown ($1,516) is equity, not cash. You cannot spend it until you refinance or sell. A property with $200/month cash flow and $126/month principal paydown gives you $200 in pocket and $126 in forced equity — both matter, but only cash flow pays bills.
3. Ignoring Amortization When Comparing Loans
A 7% 30-year loan and an 8% 25-year loan have different monthly payments, different total interest, AND different paydown speeds. Compare them side by side in the amortization calculator before choosing. Per CFPB amortization guide, always compare total cost of each loan option.
4. Not Checking Your Amortization Before Refinancing
If you refinance a 30-year loan at year 7 into a new 30-year loan, you reset the amortization clock. You go back to 85% interest payments. Check your current balance and remaining term before refinancing — sometimes a shorter new term (20 or 25 years) saves more than the rate reduction.
5. Applying Extra Payments to Next Month Instead of Principal
When making extra payments, specify “apply to principal” with your servicer. If you just send extra money without designation, some servicers apply it to the next month’s payment — which does NOT reduce your principal early and does NOT save interest. Always confirm how extra payments are applied.
Frequently Asked Questions
What is an amortization schedule?
An amortization schedule is a month-by-month table that shows how each mortgage payment is divided between principal (reducing your loan balance) and interest (bank’s fee for lending). Early payments are mostly interest (85–90%), shifting to mostly principal by the end of the loan. On a $150,000 / 30-year / 7% loan, your first payment of $998 splits into $123 principal and $875 interest. The schedule tracks every payment through payoff.
How much interest do you pay on a 30-year mortgage?
How much can you save with extra mortgage payments?
Should I make extra payments on an investment property mortgage?
What is the difference between amortization and depreciation?
Related Calculators and Guides
- Amortization Schedule Calculator — Full month-by-month loan breakdown
- Investment Property Mortgage Calculator — Monthly PITI payment
- BRRRR Calculator — Buy Rehab Rent Refinance Repeat analysis
- ROI Calculator — Total return including equity build
- Rental Property Calculator — Full cash flow analysis
- DSCR Calculator — Debt service coverage ratio
- All 30+ Calculators
Related guides:
Leave a Reply