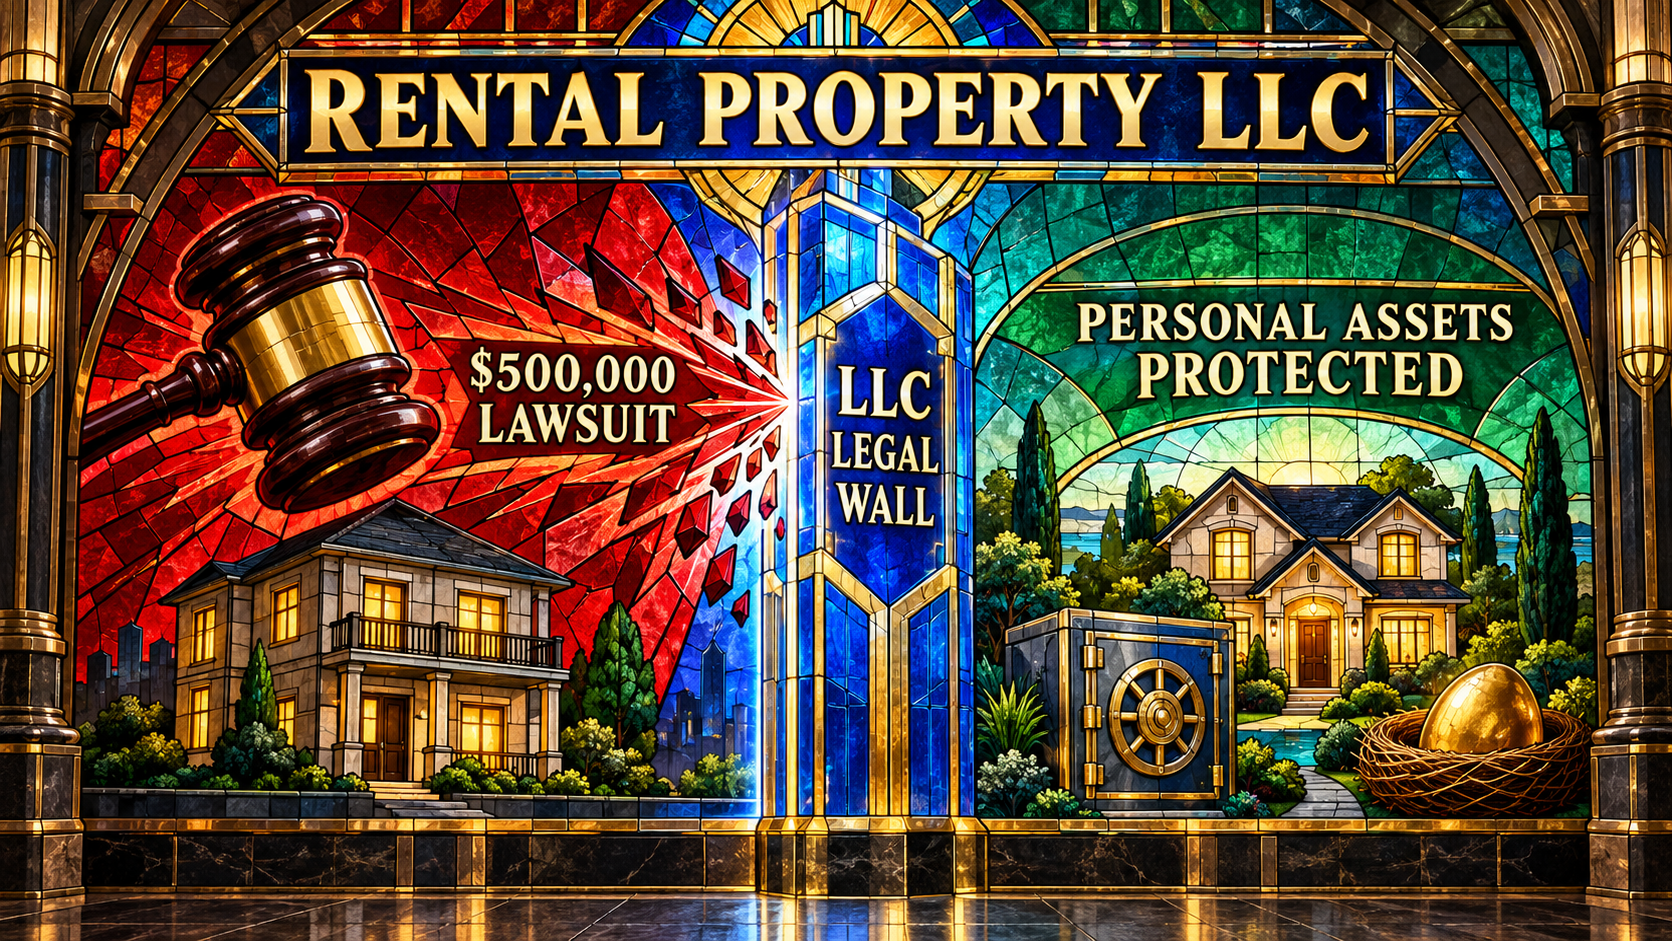
If a tenant slips on your rental property stairs and sues for $500,000, do you want that lawsuit to hit YOUR bank account — or a separate legal entity with limited assets? This is why rental property investors use LLCs. A Limited Liability Company creates a legal wall between your investment properties and your personal assets: home, savings, retirement accounts. But LLCs also come with costs, tax implications, and financing complications that many investors do not understand until it is too late. This guide covers when you need an LLC for rental property, how to set one up, what it costs, and the 5 mistakes that destroy your liability protection.
What Is an LLC for Rental Property?
An LLC (Limited Liability Company) is a business structure that separates your personal assets from your rental property business. When you hold rental property in an LLC, the LLC — not you personally — owns the property. If a tenant sues, they sue the LLC. Your personal home, savings, and other investments are protected.
Per SBA business structure guidelines, an LLC provides liability protection similar to a corporation but with the tax simplicity of a sole proprietorship or partnership. For real estate investors, this is the ideal combination: protection without complexity.
How LLC Protection Works
WITHOUT LLC:
  You personally own 123 Main St (rental property)
  Tenant sues for $500,000
  Lawsuit targets YOU
  At risk: your home, savings, retirement, other properties, wages

WITH LLC:
  "Main Street Rentals LLC" owns 123 Main St
  Tenant sues for $500,000
  Lawsuit targets the LLC
  At risk: only assets inside the LLC (the rental property + LLC bank account)
  Protected: your home, savings, retirement, other properties
The LLC acts as a legal shield. If the lawsuit exceeds the LLC’s assets, the plaintiff cannot typically reach your personal wealth. This is called “limited liability” — your risk is limited to what the LLC owns.
Do You Need an LLC for Rental Property?
Not every landlord needs an LLC immediately. Here is when it makes sense and when it does not.
You NEED an LLC When:
- You own 2+ rental properties — multiple properties = multiple liability exposures. An LLC (or multiple LLCs) isolates risk so one bad lawsuit does not take down your entire portfolio
- You have significant personal assets — if you have $200K+ in savings, retirement, or home equity, the $500–$1,500 annual LLC cost is cheap insurance
- You hire property managers or contractors — employees and contractors create additional liability. The LLC shields you from their mistakes
- You live in a litigious state — California, New York, Florida, and Texas see the most landlord lawsuits. LLC protection is more valuable here
- Your property has high-risk features — swimming pool, trampoline, old wiring, lead paint, multiple stories. Higher injury risk = higher lawsuit risk
You Can Wait When:
- You own 1 property and have few personal assets — a good landlord insurance policy ($1M+ liability) provides adequate protection for a single property when you are just starting out
- You are house hacking — if you live in the property with an FHA or VA loan, transferring to an LLC can trigger the due-on-sale clause. Wait until you move out and refinance. See our house hacking guide
How to Set Up an LLC for Rental Property: Step by Step
Step 1: Choose Your State
Form the LLC in the state where the property is located. If you own property in Ohio, form an Ohio LLC. Some investors form in Wyoming, Nevada, or Delaware for stronger privacy/protection laws — but you will still need to register as a foreign LLC in the state where the property sits, which adds cost and complexity.
Step 2: Choose a Name
The LLC name must be unique in your state. Best practice: use a generic name that does not reveal your personal identity. “Summit Property Holdings LLC” is better than “John Smith Rentals LLC” — it keeps your name off public records and reduces the chance of a personal lawsuit.
Step 3: File Articles of Organization
File with your state’s Secretary of State. Cost: $50–$500 depending on the state. Most states allow online filing.
Step 4: Get an EIN
Apply for an Employer Identification Number from the IRS (free, takes 5 minutes online). The EIN is the LLC’s tax ID — you use it to open bank accounts and file taxes.
Step 5: Create an Operating Agreement
Even for single-member LLCs, an operating agreement is critical. It documents how the LLC is managed, how profits are distributed, and what happens if you add a partner or sell. Many states do not require it legally, but without one, courts may disregard your LLC protection (“piercing the corporate veil”).
Step 6: Open a Separate Bank Account
This is the most important step. The LLC must have its own bank account. All rental income goes IN to this account. All property expenses come OUT of this account. Never mix personal and LLC funds — commingling is the #1 reason courts pierce the LLC veil and remove your protection.
Step 7: Transfer the Property (or Buy in the LLC’s Name)
If you already own the property, you transfer it to the LLC via a quit-claim deed. Cost: $50–$200 for recording. Warning: if the property has a mortgage, transferring ownership may trigger the due-on-sale clause (the lender can demand full repayment). In practice, most lenders do not enforce this for transfers to your own LLC — but it is a real risk. Consult an attorney before transferring.
If you are buying a new property, you can purchase directly in the LLC’s name — but most residential lenders will not lend to an LLC. You will need a commercial loan or DSCR loan. Check rates in the DSCR calculator.
LLC for Rental Property: Costs Breakdown
| Cost | One-Time | Annual | Notes |
|---|---|---|---|
| Articles of Organization | $50–$500 | — | Varies by state. CA: $70, NY: $200, WY: $100 |
| Annual Report / Franchise Tax | — | $0–$800 | CA: $800/yr. Many states: $0–$100 |
| Registered Agent | — | $100–$300 | Required in most states. Can use yourself if in-state |
| Operating Agreement | $0–$1,000 | — | DIY template: $0. Attorney-drafted: $500–$1,000 |
| EIN (IRS) | $0 | — | Free from IRS.gov |
| Quit-Claim Deed Transfer | $50–$200 | — | Recording fee to transfer property into LLC |
| Separate Bank Account | $0 | $0–$15/mo | Many business accounts are free |
| Total Year 1 | $200–$2,500 depending on state and attorney fees | ||
| Total Annual (ongoing) | $100–$1,100 per year | ||
For most states, the total ongoing cost is $100–$300/year per LLC. California is the most expensive at $800/year minimum franchise tax regardless of income. Compare this to a single lawsuit that could cost $50,000–$500,000 without protection.
LLC Filing Costs by State (Top 10 Investor States)
| State | Filing Fee | Annual Report | Franchise Tax | Total Year 1 | Annual Ongoing |
|---|---|---|---|---|---|
| Wyoming | $100 | $60 | $0 | $160 | $60 |
| Ohio | $99 | $0 | $0 | $99 | $0 |
| Indiana | $95 | $32 | $0 | $127 | $32 |
| Tennessee | $300 | $300 | $0 | $600 | $300 |
| Texas | $300 | $0 | $0* | $300 | $0* |
| Florida | $125 | $138 | $0 | $263 | $138 |
| Georgia | $100 | $50 | $0 | $150 | $50 |
| North Carolina | $125 | $200 | $0 | $325 | $200 |
| New York | $200 | $9 | $0 | $209+ | $9+ |
| California | $70 | $20 | $800 | $890 | $820 |
*Texas has no franchise tax for LLCs with revenue under $2.47M. NY requires publication in newspapers ($300–$1,500 depending on county).
Best states for LLC formation: Ohio ($99 total, $0 annual) and Wyoming ($100 filing, $60/year with strong privacy laws) are the cheapest. California at $820/year ongoing is the most expensive — but if your property is in California, you must register there regardless.
Transferring Existing Property Into an LLC
If you already own rental property in your personal name, transferring it to an LLC involves several steps and risks.
The Transfer Process
- Create the LLC — follow the 7 steps above
- Prepare a quit-claim deed — this transfers title from “Jane Smith” to “XYZ Properties LLC.” Cost: $50–$200 for recording with the county
- Update insurance — your landlord policy must list the LLC as the named insured, not you personally. Call your agent before the transfer
- Update leases — send tenants a letter informing them that ownership has transferred to the LLC. Rent payments should go to the LLC bank account
- Record the deed — file with your county recorder’s office
The Due-on-Sale Clause Risk
Most mortgages contain a due-on-sale clause — the lender can demand full repayment if ownership transfers. Transferring to your own single-member LLC technically triggers this clause. However, the Garn-St. Germain Act (12 USC 1701j-3) protects transfers to a trust — and some attorneys argue that single-member LLC transfers are similarly protected.
In practice: Most lenders do not enforce the due-on-sale clause for transfers to your own LLC as long as payments remain current. But it is a real risk — consult a real estate attorney in your state before transferring. Alternatives:
- Wait for refinance: When you refinance, close the new loan in the LLC’s name (requires DSCR or commercial loan). Check rates in the DSCR calculator
- Use a land trust: Transfer to a revocable land trust (protected by Garn-St. Germain), then assign the beneficial interest to the LLC. More complex but legally safer
- Buy the next property in the LLC: Skip the transfer hassle. Purchase new properties directly in the LLC’s name from the start
Title Insurance Considerations
Your existing title insurance policy may not cover the LLC after transfer. Contact your title company to confirm. Some insurers issue an endorsement ($100–$200) to extend coverage to the LLC. Others require a new policy. Do not skip this — a gap in title insurance leaves you unprotected against prior claims.
LLC Tax Benefits for Rental Property
An LLC does not change your tax rate — but it does provide structural advantages:
Pass-Through Taxation
A single-member LLC is a “disregarded entity” for tax purposes. Rental income flows through to your personal tax return (Schedule E). You do not file a separate corporate tax return. No double taxation.
All Rental Deductions Still Apply
Depreciation, mortgage interest, property tax, repairs, management fees, travel — all deductible whether you own personally or through an LLC. The LLC does not add or remove deductions. See our 15 rental property tax deductions guide.
QBI Deduction (Section 199A)
The Qualified Business Income deduction allows eligible rental property owners to deduct up to 20% of net rental income. The LLC structure strengthens the argument that your rental activity is a “business” (not just investment income), which helps qualify for QBI. Per IRS QBI guidelines, rental real estate can qualify under the safe harbor if you maintain separate books, perform 250+ hours of rental services per year, and keep records.
Easier Expense Tracking
With a separate LLC bank account, every transaction is automatically categorized as business. No more sorting personal from rental expenses at tax time. This also provides cleaner records for IRS audit protection.
Calculate your depreciation in the depreciation calculator and total deductions in the cost segregation guide.
One LLC or Multiple LLCs? How to Structure Your Portfolio
As your portfolio grows, the structure question becomes critical.
Option 1: One LLC for All Properties
Pros: Simple, one set of fees, one bank account, one tax return.
Cons: A lawsuit on ANY property exposes ALL properties in the LLC. If a tenant at Property A sues and wins $300K, Properties B, C, and D are at risk too.
Best for: 1–3 properties, small portfolio, low risk tolerance.
Option 2: Separate LLC for Each Property
Pros: Maximum isolation. A lawsuit on Property A only affects Property A’s LLC. Properties B, C, D are completely separate entities.
Cons: Expensive ($200–$1,100/year per LLC), more paperwork, more bank accounts.
Best for: High-value properties ($300K+), 4+ properties, litigious markets.
Option 3: Series LLC (Available in Some States)
Pros: One LLC with separate “series” (cells) for each property. Each series has its own assets and liabilities — isolated from other series. One filing fee, one annual report.
Cons: Only available in ~20 states (Texas, Delaware, Illinois, Nevada, others). Not tested in all courts. Some title companies and lenders unfamiliar with series LLCs.
Best for: 5+ properties in states that recognize series LLCs.
Option 4: Holding Company + Property LLCs
Pros: One parent LLC (“Holding Company”) owns multiple child LLCs, each holding one property. Maximum protection with centralized management.
Cons: Most expensive option. Each LLC has its own fees, bank account, and filings.
Best for: 10+ properties, professional investors, highest asset protection needs.
5 Mistakes That Destroy Your LLC Protection
1. Commingling Funds
The #1 way courts “pierce the corporate veil.” If you deposit rental income into your personal account, pay property expenses with personal credit cards, or loan money between personal and LLC accounts without documentation — a court can rule that the LLC is a sham and you are personally liable. Fix: Separate bank account for the LLC. Every dollar in and out goes through the LLC account.
2. Not Maintaining the LLC
Filing the Articles of Organization is not enough. You must file annual reports, pay franchise taxes, maintain a registered agent, and keep meeting minutes (if multi-member). If the LLC falls out of good standing, courts may disregard it.
3. Under-Capitalizing the LLC
An LLC with $0 in its bank account does not provide meaningful protection. Courts can rule it is an “alter ego” of the owner. Keep at least 2–3 months of operating expenses in the LLC account at all times.
4. Personally Guaranteeing Everything
Most investment property loans require a personal guarantee — this means the lender can pursue your personal assets if the LLC defaults. The LLC protects against tenant lawsuits, not lender claims. Understand what the LLC does and does not protect.
5. Signing Contracts Personally Instead of as LLC Manager
When you sign a lease, always sign as “Jane Smith, Manager of XYZ Properties LLC” — not just “Jane Smith.” If you sign personally, you may be personally liable for the contract. Same for vendor contracts, insurance policies, and purchase agreements.
LLC vs. Other Protection Strategies
| Strategy | Cost | Protection Level | Best For |
|---|---|---|---|
| Landlord Insurance ($1M liability) | $200–$500/yr | Good | 1 property, starting out |
| Umbrella Insurance ($1M–$5M) | $300–$600/yr | Good | Multiple properties, additional coverage layer |
| Single LLC | $200–$1,100/yr | Strong | 1–3 properties, moderate portfolio |
| Multiple LLCs | $500–$3,000/yr | Strongest | 4+ properties, high-value assets |
| LLC + Umbrella (recommended) | $500–$1,700/yr | Best | Serious investors, maximum protection |
Recommended approach: Start with landlord insurance on your first property. Add an LLC when you buy property #2. Add umbrella insurance when your portfolio exceeds $500K in value. This layered approach provides maximum protection at each stage of growth.
LLC for Rental Property vs. Umbrella Insurance: Detailed Comparison
Many investors ask: “Can I just get umbrella insurance instead of an LLC?” The answer: they protect against different things.
- LLC protection: Creates a legal separation. If a tenant wins a $500K judgment, only LLC assets are at risk. Your personal assets are walled off regardless of the judgment amount. But the LLC does not pay legal defense costs — you need insurance for that
- Umbrella insurance ($1M–$5M coverage): Pays legal defense costs AND settlement/judgment up to the policy limit. But if the judgment exceeds coverage, your personal assets ARE at risk. No legal wall — just a financial cushion
- Both together (recommended): The LLC walls off personal assets. The umbrella pays defense costs and settlements. If a $500K judgment hits, the umbrella covers it — and even if it did not, only LLC assets are exposed. You get both active protection (insurance pays the bill) and passive protection (LLC limits what is at risk)
Cost comparison: LLC = $100–$300/year. Umbrella ($1M) = $300–$600/year. Both together = $400–$900/year. This is less than a single month of rent on most investment properties — cheap insurance for your entire net worth.
LLC vs. Land Trust
A land trust provides privacy (your name does not appear on public records) but limited liability protection. Courts can easily pierce a land trust if you are the sole beneficiary. An LLC provides actual legal liability protection. Best practice: use a land trust for privacy + an LLC for protection (property in a land trust, LLC is the beneficiary).
Frequently Asked Questions
Should I put my rental property in an LLC?
Yes — if you own 2+ properties, have significant personal assets ($200K+), or operate in a litigious state. An LLC separates your personal assets from your rental business, protecting your home, savings, and retirement from tenant lawsuits. For a single property with few personal assets, a good landlord insurance policy ($1M liability) provides adequate protection while you build your portfolio.
How much does an LLC for rental property cost?
Can I get a mortgage in an LLC’s name?
Does an LLC change how I pay taxes on rental income?
Should I have one LLC or multiple LLCs for my rental properties?
Related Calculators and Guides
- Rental Property Calculator — Full cash flow analysis
- DSCR Calculator — Loan qualification for LLC purchases
- Depreciation Calculator — Tax deductions inside your LLC
- Seller Net Sheet Calculator — Net proceeds when selling LLC-held property
- Capital Gains Tax Calculator — Tax on property sale
- All 30+ Calculators
Related guides:
Leave a Reply