Published: October 7, 2026 · By Alex Petrov
I’ve spent nine years building a rental portfolio that includes both cash flow properties and appreciation bets. My Cleveland duplex throws off $650 a month in net income and hasn’t budged in value. My Austin townhouse lost money every month for three years — then doubled in price. Both strategies made me money. Both nearly broke me at different points.
The cash flow vs appreciation debate isn’t theoretical to me. I’ve lived it. And the answer to “which is better?” depends on factors that most blog posts ignore: your age, your W-2 income, your risk tolerance, and how long you can afford to bleed red before the numbers turn green.
In this article, I’m going to take the same $200,000 of investable capital, deploy it two completely different ways, and track both strategies over 10 years with actual math — not hand-waving. I’ll use real cities, real rent numbers, and current interest rates so you can see exactly how each approach plays out.
If you haven’t read it yet, my best cities to invest in real estate in 2026 article groups 12 markets by strategy. This piece goes deeper into the strategies themselves — when each one wins, when each one fails, and how to combine them.
What Cash Flow Investing Actually Means
Cash flow investing means buying properties where the rental income exceeds all expenses — mortgage, taxes, insurance, management, maintenance, vacancy — from month one. You get paid every single month. The property might never appreciate much, and you don’t care. Your profit comes from the spread between income and costs.
Cash flow investors target markets where prices are low relative to rents. Think Cleveland, Memphis, Indianapolis, Detroit. A $130,000 duplex renting for $1,400/month can generate $300–$500 in monthly net income after every bill is paid. That’s money hitting your bank account 30 days after closing.
The key metric for cash flow investors is cash-on-cash return. If you invest $40,000 (down payment plus closing costs) and collect $4,800 in annual net income, your cash-on-cash return is 12%. That’s how cash flow investors measure success — not by property value going up, but by the yield on their invested capital.
You also want to understand net operating income (NOI) because that’s the starting point for every cash flow calculation. NOI tells you what the property earns before debt service. If NOI doesn’t cover your mortgage payment, you don’t have a cash flow deal — you have an appreciation bet with extra steps.
Who Cash Flow Investing Is For
- Investors replacing W-2 income or building toward financial independence
- Retirees who need monthly income from their investments
- Anyone living in an expensive market (Bay Area, NYC, Seattle) who wants to invest out-of-state for yield
- Conservative investors who can’t afford to feed negative cash flow for years
- People scaling fast — each property’s income funds the next down payment
What Appreciation Investing Actually Means
Appreciation investing means buying properties in markets where home values are rising faster than the national average — and accepting thin or negative cash flow in exchange for equity growth. Your profit comes when you sell or refinance years later at a higher price.
Appreciation investors target markets with strong job growth, population inflows, and constrained housing supply. Austin, Raleigh, Nashville, Boise — markets where a $350,000 property might grow to $500,000 in five years. The monthly rent might not cover the mortgage, but the $150,000 in equity gain dwarfs whatever you lost in monthly cash flow.
The key metric here is internal rate of return (IRR). IRR accounts for the timing of all cash flows — the down payment going out, the monthly losses going out, and the big lump sum coming in at sale. A property that loses $200/month but gains $150,000 in value over five years can still deliver a 15%+ IRR.
This is also where cap rates come in. Appreciation markets have low cap rates — typically 3–5% — because prices are high relative to rents. Buyers are paying for future growth, not current income. If you see a 3.5% cap rate market, that’s the market telling you: “People are buying for appreciation here.”
Who Appreciation Investing Is For
- High-income earners who don’t need investment income today
- Younger investors with a 15–20 year time horizon
- People who can absorb $200–$400/month in negative cash flow without stress
- Investors focused on net worth growth over income replacement
- Those in high tax brackets who can use depreciation to offset W-2 income
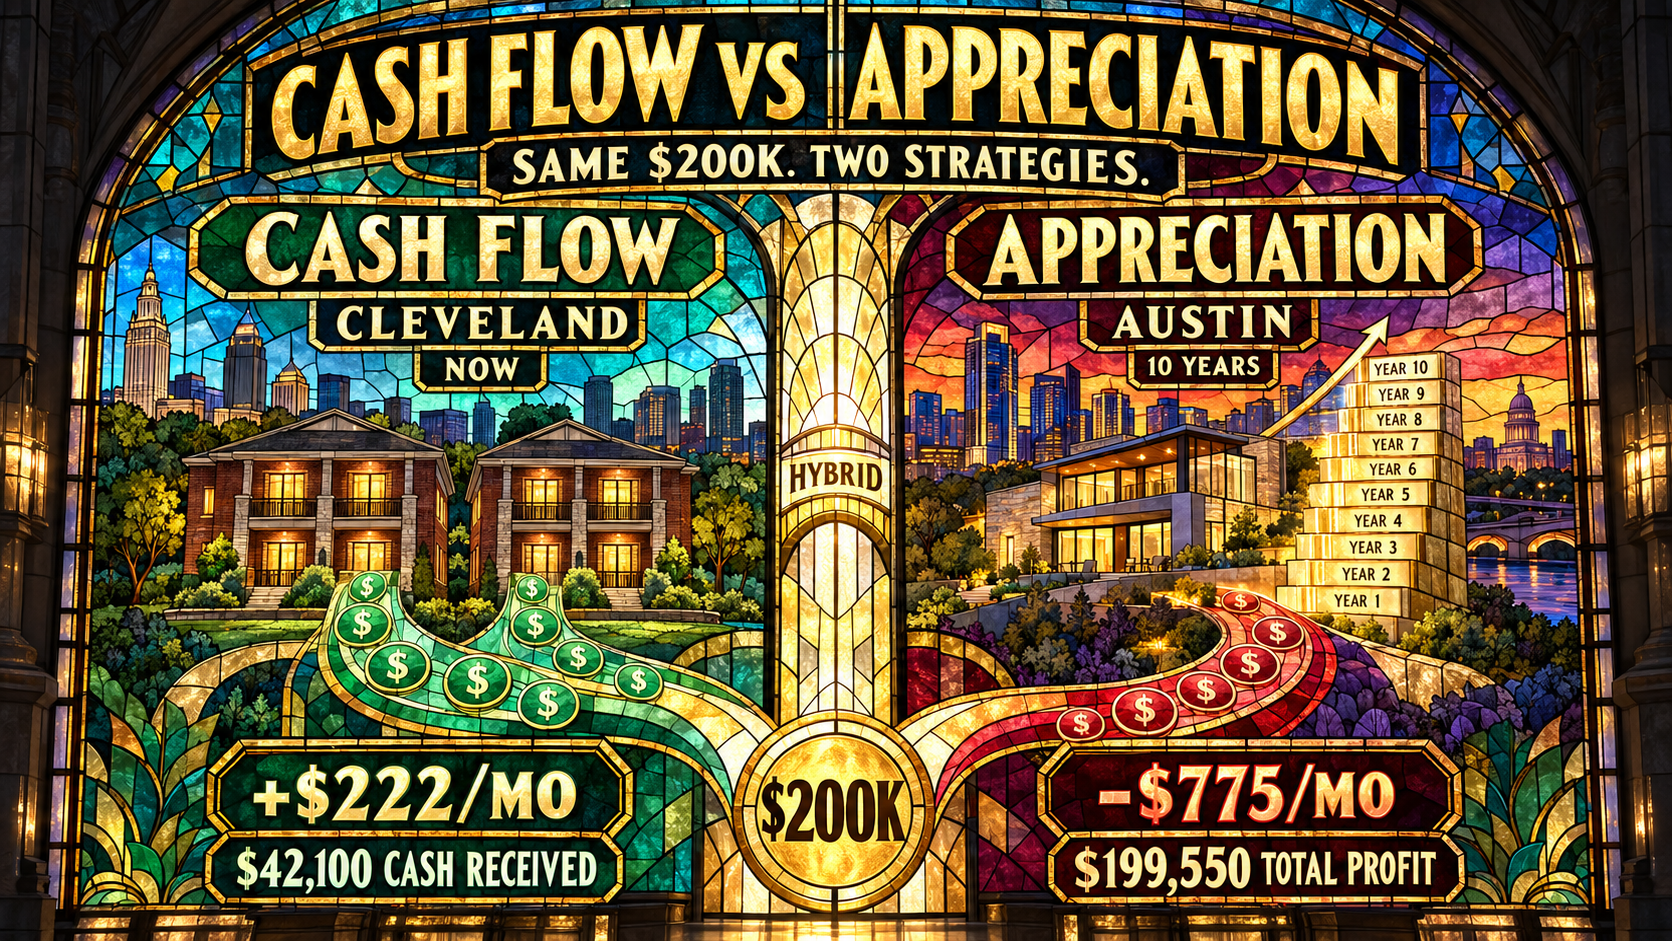
Same $200K — Two Different Strategies
Let’s stop talking in theory and run the actual numbers. I’m going to take $200,000 in investable cash and deploy it two different ways. Both scenarios assume a 30-year fixed mortgage at 6.75% (current average for investment properties, per Federal Reserve FRED data).
Strategy A: Cash Flow — Cleveland Duplex Portfolio
With $200K, I’m buying two duplexes in Cleveland’s west side (Lakewood/West Park area). Here’s the deal structure:
| Item | Property 1 | Property 2 | Total |
|---|---|---|---|
| Purchase Price | $135,000 | $145,000 | $280,000 |
| Down Payment (25%) | $33,750 | $36,250 | $70,000 |
| Closing Costs (3%) | $4,050 | $4,350 | $8,400 |
| Rehab Budget | $15,000 | $12,000 | $27,000 |
| Reserves (6 months) | $7,200 | $7,800 | $15,000 |
| Total Cash In | $60,000 | $60,400 | $120,400 |
| Monthly Rent (both units) | $1,400 | $1,500 | $2,900 |
| Mortgage Payment | -$657 | -$706 | -$1,363 |
| Taxes + Insurance | -$280 | -$310 | -$590 |
| Management (8%) | -$112 | -$120 | -$232 |
| Maintenance + CapEx (10%) | -$140 | -$150 | -$290 |
| Vacancy (7%) | -$98 | -$105 | -$203 |
| Monthly Cash Flow | $113 | $109 | $222 |
Remaining from the $200K: about $79,600 sits in reserves and ready for a third property when the right deal comes along. Annual cash flow from both properties: $2,664. Cash-on-cash return on the $120,400 invested: 2.2% in year one — not amazing, but that rises as rents increase. Use the property cash flow calculator to model your own scenario.
Where it gets interesting is the 10-year picture. Cleveland rents have grown about 3.5% annually over the past five years. Property values creep up 1–2% per year. Not exciting — but consistent.
Strategy B: Appreciation — Austin Single-Family Home
With $200K in Austin, I’m buying one single-family home in a high-growth suburb (Pflugerville, Round Rock, or Kyle).
| Item | Amount |
|---|---|
| Purchase Price | $385,000 |
| Down Payment (25%) | $96,250 |
| Closing Costs (3%) | $11,550 |
| Light Rehab | $8,000 |
| Reserves (6 months) | $14,400 |
| Total Cash In | $130,200 |
| Monthly Rent | $2,200 |
| Mortgage Payment | -$1,874 |
| Property Tax (2.1% of value) | -$674 |
| Insurance | -$165 |
| Management (8%) | -$176 |
| Maintenance + CapEx (8%) | -$176 |
| Vacancy (5%) | -$110 |
| Monthly Cash Flow | -$775 |
Negative $775 per month. That’s $9,300 a year coming out of your pocket. In Austin, Texas property taxes eat you alive — 2.1% of assessed value means your tax bill alone runs over $8,000/year. This is a pure appreciation play. You’re paying to own this asset.
But Austin’s median home price has grown at 6.8% annually over the past decade, according to Census American Housing Survey data. That $385,000 property could realistically hit $550,000–$600,000 in seven to eight years.
10-Year Side-by-Side Comparison
Here’s where the two strategies diverge dramatically. I’m projecting 10 years forward using conservative assumptions: 3.5% annual rent growth for Cleveland, 4% for Austin. Property appreciation of 1.5% for Cleveland, 5% for Austin. Vacancy at the rates above.
| Metric | Cash Flow (Cleveland) | Appreciation (Austin) |
|---|---|---|
| Total Cash Invested | $120,400 | $130,200 |
| Year 1 Cash Flow | +$2,664 | -$9,300 |
| 10-Year Cumulative Cash Flow | +$42,100 | -$61,400 |
| Property Value (Year 10) | $324,600 | $627,100 |
| Equity from Appreciation | $44,600 | $242,100 |
| Equity from Mortgage Paydown | $38,200 | $52,800 |
| Total Equity (Year 10) | $152,800 | $391,150 |
| Total Profit (Equity + Cash Flow – Cash In) | $74,500 | $199,550 |
| Annualized Return (IRR) | 9.4% | 14.8% |
| Liquidity (Cash in Pocket) | $42,100 received | $61,400 spent |
| Risk if Market Drops 20% | Still cash flow positive | Underwater + bleeding monthly |
At first glance, appreciation wins by a wide margin. The Austin property generated nearly $200K in total profit compared to $74.5K for Cleveland. But look at the liquidity column — the Cleveland investor received $42,100 in actual cash over those 10 years, while the Austin investor spent $61,400 feeding the property. That’s a $103,500 swing in your bank account balance.
And look at the risk row. If the market drops 20% in year four, the Cleveland investor still collects rent checks every month. The Austin investor is underwater on the mortgage AND still writing a $775 check every month. I’ve seen that scenario break people. Run both scenarios through the rental property calculator to see how different assumptions change the outcome.
When Cash Flow Wins
Cash flow doesn’t just “sort of” win in certain situations — it dominates. Here are the conditions where cash flow investing is clearly the superior strategy.
1. When You Need Income Replacement
If your goal is to replace your salary within 5–7 years, appreciation investing is mathematically impossible. You can’t eat equity. You can’t pay your mortgage with unrealized gains. Cash flow properties put money in your account every month — and with enough of them, that income replaces your paycheck.
Ten Cleveland duplexes generating $200–$300/month each means $2,000–$3,000/month in passive income. That’s life-changing money for someone in their 40s or 50s looking to exit the corporate world. Ten Austin appreciation plays means ten properties bleeding you dry while you wait for an exit that may or may not come.
2. During Rising Interest Rate Environments
When rates climb, appreciation markets get crushed. Higher rates mean higher mortgage payments, which compresses what buyers can afford, which kills price growth. Between 2022 and 2024, Austin prices dropped 15% from their peak. Investors who bought at the top in 2022 spent two years underwater.
Cash flow properties are rate-resistant. Yes, your mortgage payment rises on new purchases, but you can adjust for that by buying at lower prices or targeting higher-rent properties. The income stream itself doesn’t depend on rates — tenants pay the same rent whether the 30-year fixed is at 4% or 7%.
3. When You’re Scaling Your Portfolio
Each cash flow property funds the next one. If Property A generates $300/month, that’s $3,600/year toward the down payment on Property B. Multiply by five properties and you’re accumulating $18,000/year in down payment capital just from cash flow. This is how investors go from 2 properties to 10 in five years without injecting additional W-2 income.
Appreciation investors can’t scale this way. Each property is a drain on capital, not a source. You scale through equity events — refinances or sales — which are lumpy, unpredictable, and tax-inefficient.
4. In Flat or Declining Markets
Between 2006 and 2012, U.S. home prices dropped 33% nationally. Appreciation investors lost everything. Cash flow investors — the ones who bought at reasonable price-to-rent ratios — kept collecting rent through the entire crisis. Rents actually increased during the Great Recession because displaced homeowners became renters.
Cash flow is defensive. When you track your properties using a vacancy rate calculator, you’ll see that even in downturns, well-located rentals in affordable markets maintain 90%+ occupancy. You might lose equity on paper, but you don’t lose income.
When Appreciation Wins
Appreciation investing has its own clear advantages — and in the right conditions, it generates wealth that cash flow simply can’t match.
1. During Economic Expansions with Job Growth
When tech companies are hiring, population is growing, and housing supply is constrained, appreciation markets can deliver 8–12% annual price increases. An investor who bought in Austin in 2015 at $250,000 held a property worth $500,000 by 2022 — a $250,000 gain on roughly $75,000 of invested capital. That’s a 3.3x return in seven years, or approximately 18% annualized.
No cash flow market can touch that kind of total return. Cleveland’s best cash flow property might generate $4,000/year in income on $40,000 invested — a 10% yield, which is good, but the total dollar amount is small. Appreciation creates large absolute dollar returns because gains compound on the full property value, not just your invested capital.
2. When You Have a Long Time Horizon (10+ Years)
Appreciation is volatile year-to-year but remarkably consistent over long periods. According to National Association of Realtors historical data, U.S. median home prices have increased in 45 of the past 50 years. Over any 10-year rolling period since 1975, prices have gone up — even including the 2008 crash.
If you’re 30 years old and buying your first investment property, the math strongly favors appreciation. You have time to ride out downturns, and the compounding effect over 20–30 years is massive. A $400,000 property appreciating 5% annually is worth $1,061,000 in 20 years.
3. When You’re in a High Tax Bracket
Cash flow is taxed as ordinary income — the same rate as your W-2. If you’re in the 32% bracket, that $300/month cash flow is really $204 after federal tax. Appreciation, on the other hand, isn’t taxed until you sell. And when you do sell, you can use a 1031 exchange to defer taxes indefinitely — or step up the basis at death.
Depreciation also works harder in appreciation markets. A $385,000 Austin property (excluding land) might give you $10,000/year in paper losses that offset your W-2 income. That tax savings alone can cover your negative monthly cash flow.
4. When Housing Supply Is Constrained
Markets with geographic barriers (water, mountains), strict zoning, or slow permitting processes tend to appreciate faster because new supply can’t keep up with demand. Think coastal California, parts of Colorado, Raleigh (planning restrictions), and Austin (land supply is shrinking as suburbs expand).
Cash flow markets like Cleveland and Memphis have the opposite dynamic — land is cheap, permitting is easy, and new construction can always meet demand. That’s great for keeping purchase prices low, but it also caps price growth.
The Hybrid Strategy: Why You Don’t Have to Choose
The best investors I know don’t pick one strategy — they run both simultaneously. Here’s how a hybrid approach works in practice.
Phase 1: Cash Flow Foundation (Years 1–3)
Start with two to three cash flow properties. Target markets like Indianapolis, Cleveland, or Kansas City. Goal: build $1,500–$2,500/month in passive income. This cash flow does three things for you: it covers emergencies, it proves you can manage rentals, and it starts generating down payment capital for your next move.
At this stage, run every deal through the property cash flow calculator and demand positive cash flow from day one. Don’t stretch for break-even deals or count on rent increases to save you. Be conservative.
Phase 2: Appreciation Layer (Years 3–5)
Once you have stable cash flow from your foundation properties, add one or two appreciation plays. Use your cash flow income to offset the negative monthly cash flow on the appreciation properties. If your Cleveland duplexes generate $600/month and your Austin rental loses $500/month, you’re still net positive at $100/month — but now you have exposure to a high-growth market.
The cash flow properties are bankrolling the appreciation bet. That’s the magic of the hybrid approach.
Phase 3: Optimize and Harvest (Years 5–10)
By year five, your appreciation properties may have enough equity for a cash-out refinance. Pull $100K out of the Austin property and redeploy it into two more cash flow properties. Now you’ve used appreciation to accelerate your cash flow — the best of both worlds.
Alternatively, sell the appreciation property via 1031 exchange and buy three cash flow properties with the proceeds. You’ve converted speculative equity into reliable monthly income.
Sample Hybrid Portfolio (Year 5)
| Property | Market | Strategy | Monthly CF | Est. Value | Est. Equity |
|---|---|---|---|---|---|
| Duplex #1 | Cleveland | Cash Flow | +$180 | $145,000 | $65,000 |
| Duplex #2 | Cleveland | Cash Flow | +$195 | $156,000 | $72,000 |
| SFH #3 | Indianapolis | Cash Flow | +$240 | $215,000 | $78,000 |
| SFH #4 | Austin | Appreciation | -$550 | $490,000 | $198,000 |
| Totals | +$65 | $1,006,000 | $413,000 | ||
Net positive cash flow of $65/month — barely positive, but positive. Over $400,000 in equity across four properties. And you only invested $200,000 out of pocket. That’s the hybrid strategy in action.
To figure out whether your cash-on-cash return targets are realistic for this kind of blended approach, check the averages by market type.
The 8 Factors That Determine Which Strategy Fits You
Stop asking “which is better?” and start asking “which fits my situation?” Here’s how to decide.
| Factor | Cash Flow Favored | Appreciation Favored |
|---|---|---|
| Age | 45+ (shorter runway) | Under 40 (time to compound) |
| W-2 Income | Under $100K (need supplemental income) | $150K+ (can absorb losses) |
| Risk Tolerance | Conservative | Aggressive |
| Goal | Income replacement | Net worth growth |
| Time Horizon | 3–7 years | 10–20+ years |
| Interest Rates | Rising or high (6%+) | Falling or low (under 5%) |
| Market Cycle | Late cycle / uncertain | Early-to-mid expansion |
| Tax Bracket | 22% or lower | 32%+ (depreciation benefits) |
If you checked three or more items in the Cash Flow column, start there. If you lean Appreciation on most factors, that’s your path. If you’re split down the middle, the hybrid approach is your answer.
Common Mistakes in Both Strategies
I’ve made most of these myself. Learning from my errors is cheaper than making your own.
Cash Flow Mistakes
Underestimating expenses. The biggest killer of cash flow projections is optimism. New investors budget 5% for vacancy in Cleveland when the real number is 7–8%. They forget about CapEx reserves, and then the roof needs replacing in year three. Always run worst-case numbers. If a deal works at 10% vacancy and 12% total maintenance/CapEx, it’s a real cash flow deal. If it only works at 5% vacancy and 8% expenses, you’re fooling yourself.
Chasing yield in war zones. A $45,000 house with $900/month rent looks like a 16% cap rate. It’s actually a money pit. The tenant trashes it, stops paying, and takes six months to evict. The neighborhood has no rental demand from quality tenants. I bought a property like this in East Cleveland in 2018 and sold it at a loss two years later. Cap rate calculations only work when you can actually collect the rent. Use the cap rate calculator to check your numbers, but don’t trust the cap rate alone — context matters.
Ignoring opportunity cost. If your cash flow portfolio generates 8% annually, but an S&P 500 index fund averages 10%, you’re underperforming a completely passive investment. Cash flow investing requires management, even with a property manager. Make sure the return justifies the work.
Appreciation Mistakes
Buying at the peak. Appreciation investors tend to buy when markets are hottest — because that’s when the narrative is strongest. “Austin is booming!” felt true in March 2022 right before prices dropped 15%. Buying for appreciation during a frenzy is like buying stocks at all-time highs. The math doesn’t change just because everyone is excited.
Underestimating carrying costs. Negative $775/month doesn’t sound bad until you multiply by 36 months and realize you’ve spent $27,900 just waiting for appreciation that may or may not arrive. Factor in Texas property taxes (reassessed annually at market value), insurance increases, and occasional repairs, and the bleed can hit $35,000–$40,000 over three years.
No exit plan. What happens if the market doesn’t appreciate? What if it’s flat for five years? Can you carry the property for five years of negative cash flow? If the answer is no, you shouldn’t be in an appreciation market. Have a specific trigger for selling at a loss: “If the property hasn’t appreciated 10% by year three, I sell and redeploy the capital.”
How Interest Rates Change the Math
The cash flow vs appreciation balance shifts dramatically based on where interest rates sit. Here’s what I mean.
At 4% interest (2020–2021 environment), the Austin property from our example would have a monthly mortgage payment of $1,378 instead of $1,874. That’s $496 less per month, turning a -$775 cash flow into -$279. The appreciation bet becomes much cheaper to carry — and more attractive as a strategy.
At 8% interest (early 2024 peak), that same mortgage payment jumps to $2,117. Monthly cash flow drops to -$1,018 — over $12,000 per year in negative income. Meanwhile, the Cleveland duplex is still cash flow positive, just at a lower margin. Higher rates punish appreciation strategies disproportionately.
This is why so many investors shifted to cash flow strategies in 2023–2024. When rates are high, the carrying cost of appreciation bets becomes brutal. When rates drop — as the Fed is projected to do through 2026 and 2027 — appreciation strategies become attractive again because monthly carrying costs decline and buyer demand pushes prices up.
Whatever rate environment you’re in, run the numbers yourself with the rental property calculator to see exactly how rate changes affect your deal.
Real-World Performance: What Actually Happened 2016–2026
Theory is nice. Let’s look at what actually happened to investors who picked each strategy 10 years ago.
Cleveland cash flow investor (2016): Bought a duplex for $95,000 at a 4.25% mortgage. Collected roughly $900/month in rent (both units). After expenses, cleared about $200/month in cash flow. Over 10 years, collected approximately $30,000 in cumulative cash flow (accounting for rent increases and occasional vacancies). Property is now worth around $130,000 — a $35,000 gain. Total return on the $30,000 invested: approximately $65,000, or about 11.5% annualized IRR.
Austin appreciation investor (2016): Bought a single-family home for $265,000 at a 4.25% mortgage. Cash flow was roughly break-even. Property is now worth approximately $430,000 — a $165,000 gain. Mortgage paydown added another $35,000 in equity. Total return on the $80,000 invested: approximately $200,000, or about 16% annualized IRR.
Appreciation won this particular 10-year period. But that period included the most aggressive housing boom in American history (2020–2022). Past performance in appreciation markets is heavily skewed by that anomaly. The next 10 years might not look anything like the last 10.
To understand all four sources of rental property profit — cash flow, appreciation, mortgage paydown, and tax benefits — read the full rental property ROI breakdown.
Which Strategy for 2026 and Beyond?
Given where we sit right now — rates at 6.5–7%, inflation cooling, job growth positive but slowing — here’s my honest take.
Cash flow is safer right now. Rates are still too high for comfortable appreciation carries. Most appreciation markets (Austin, Phoenix, Boise) are still digesting the 2021–2022 price spike. The risk-reward for buying a negative cash flow property at current rates doesn’t make sense unless you expect rates to drop significantly in the next 12–18 months.
Appreciation becomes attractive again if rates drop below 6%. When (not if) mortgage rates decline, buyer demand will surge in supply-constrained markets. If you can stomach 12–18 months of negative cash flow and believe rates will drop, buying in an appreciation market NOW at “discount” prices could be very smart. You’re buying low and riding the rate-drop wave.
The hybrid approach is the best risk-adjusted play for most investors. Build a cash flow foundation in markets like Indianapolis or Cleveland (see the best states for rental property analysis for state-level comparisons). Then, when rates drop or when you find an appreciation deal with minimal negative cash flow, add that exposure. Don’t go all-in on either strategy.
Whatever you decide, know your numbers before you write an offer. The difference between a good deal and a bad deal isn’t the strategy — it’s the math. Use the cash-on-cash calculator for cash flow deals and track good cap rate benchmarks for your target market.
FAQ
Is cash flow or appreciation more important in real estate?
Neither is universally more important — it depends on your financial position and goals. Cash flow matters more if you need monthly income, are over 45, or have limited reserves. Appreciation matters more if you’re young, have a high W-2 income, and want to maximize net worth over 15+ years. Most experienced investors run a mix: 60–70% of their portfolio in cash flow properties for stability, and 30–40% in appreciation markets for growth. The question isn’t which is “more important” but which solves the problem you actually have right now.
Can a rental property have both cash flow and appreciation?
Yes, but it’s rare. Markets that cash flow well (Cleveland, Memphis, Detroit) tend to have slow appreciation because prices are low and housing supply is abundant. Markets that appreciate quickly (Austin, Raleigh, Nashville) tend to have negative or break-even cash flow because prices are high relative to rents. The “unicorn” markets that offer both — like Indianapolis and parts of Atlanta — typically deliver moderate amounts of each: 5–6% cap rates and 3–4% annual appreciation. They won’t be the highest cash flow or the best appreciation, but they give you a balanced return. Use the NOI calculator to check whether a property generates positive income before relying on appreciation as a bonus.
How much negative cash flow is acceptable for an appreciation property?
My personal rule: never more than $500/month per property, and never more than 10% of your monthly take-home pay across all properties. If you earn $8,000/month after taxes, your total negative cash flow across all appreciation properties should stay under $800. You also need 12–18 months of carrying costs in reserves before buying. If the property loses $500/month, you need $6,000–$9,000 set aside just for that property — on top of your regular emergency fund. If you can’t meet these thresholds, you’re not ready for an appreciation strategy yet.
What is a good cash-on-cash return for a cash flow property?
In 2026’s rate environment (6.5–7% mortgages), target 6–10% cash-on-cash return for cash flow properties. At 6%, you’re matching what many bond funds deliver, so you’d better have appreciation upside too. At 10%+, you’re in strong territory — but verify the numbers aren’t built on unrealistic vacancy or maintenance assumptions. Pre-2022, when rates were 3–4%, investors routinely hit 12–15% cash-on-cash returns. Those days are gone for now. Adjust your expectations to the current rate environment and use the cash-on-cash calculator to test deals before committing capital. For national benchmarks, check the average cash-on-cash return data.
Should I sell my appreciation property if it’s losing money every month?
Not necessarily — but you need a decision framework. Ask three questions: (1) Has the property appreciated enough to justify the cumulative losses? If you’ve lost $30,000 in cash flow but gained $80,000 in equity, you’re ahead. (2) Can you continue carrying the loss for 2–3 more years without financial stress? If not, sell now. (3) What does the local market outlook look like — is job growth continuing, is supply constrained, are rates likely to drop? If the fundamentals are still strong, holding through the rough patch usually pays off. If fundamentals have weakened (layoffs, oversupply, population decline), cut your losses and redeploy into cash flow. Run the full picture through the rental property calculator to see whether holding or selling produces a better outcome.
Leave a Reply