Last updated: October 20, 2026 · Originally published: June 7, 2026 · By Alex Petrov
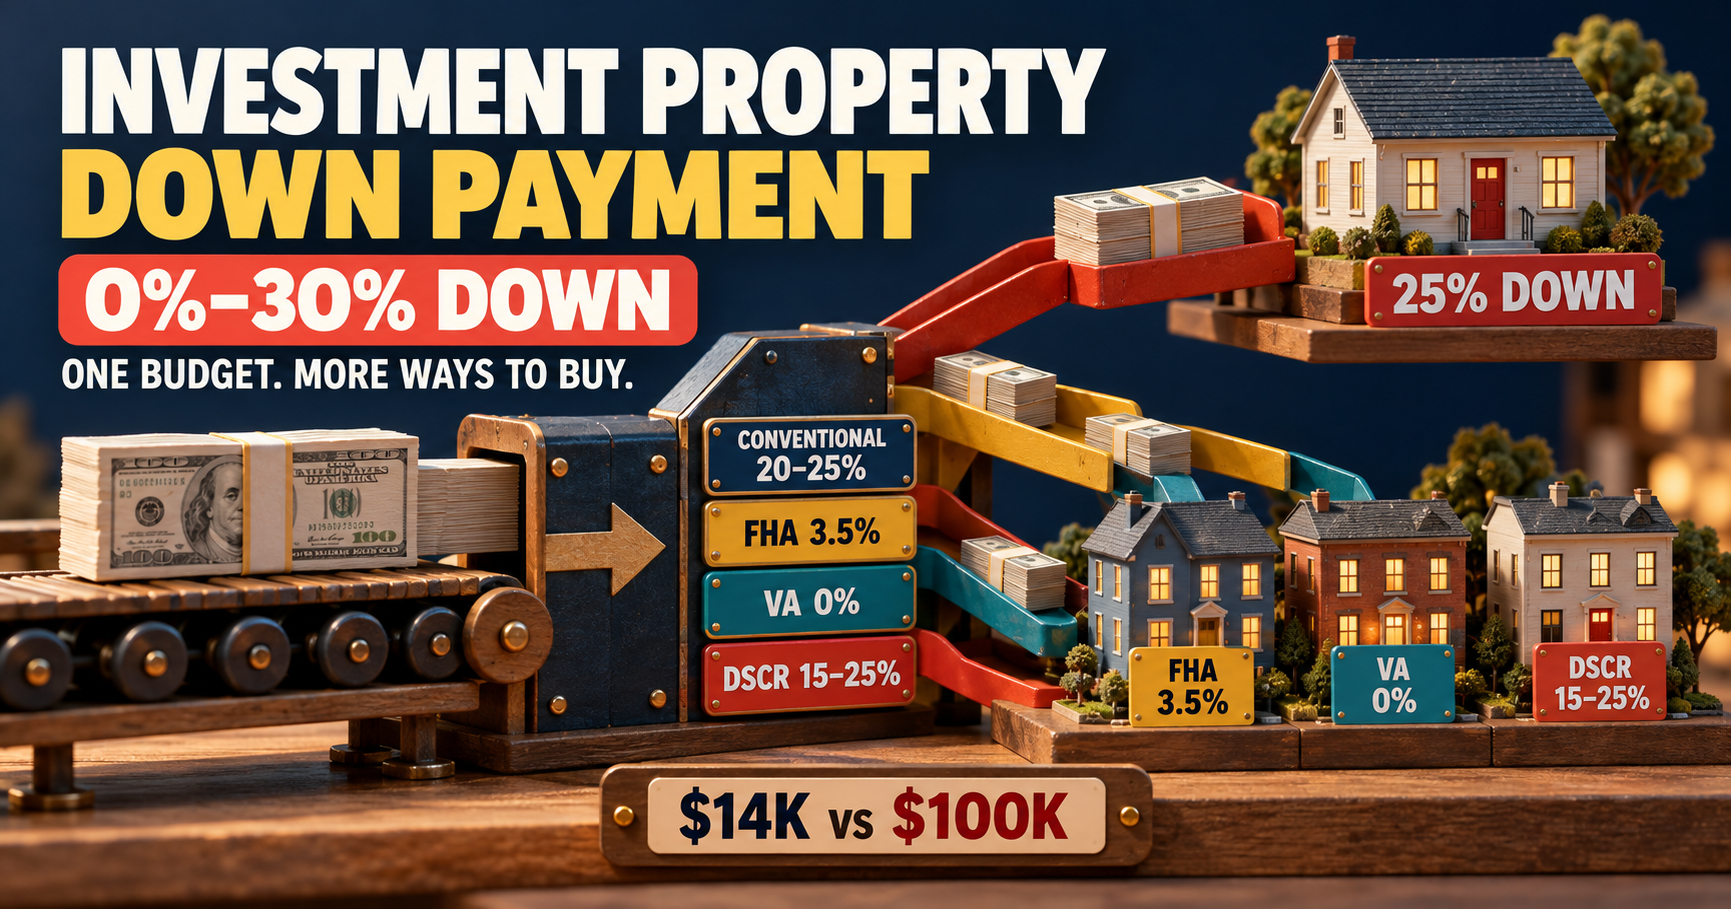
My first investment property required $67,500 down on a $270,000 duplex. My second required $14,000 down on a $400,000 fourplex. The difference was not luck — it was understanding which loan programs exist and which investment property down payment structure fits each deal. Most investors assume they need 20-25% down for every rental property purchase. That assumption costs them years of portfolio growth because they are saving for one property when they could already own three.
The actual investment property down payment requirement ranges from 3.5% to 30% depending on your loan type, the property, and whether you are willing to live in one of the units. This guide breaks down every option with real numbers so you can pick the strategy that matches your capital and goals. If you want to see how different down payment amounts affect your monthly cash flow, open the investment property mortgage calculator and follow along.
Investment Property Down Payment Requirements by Loan Type
Every loan program has different investment property down payment minimums. Here is the complete picture as of mid-2026, based on current lender guidelines and my experience closing deals through six different programs.
| Loan Type | Min Down Payment | Property Type | Owner-Occupied? | Min Credit Score | Best For |
|---|---|---|---|---|---|
| FHA | 3.5% | 1-4 units | Yes (12 months) | 580+ | First-time house hackers |
| VA | 0% | 1-4 units | Yes (varies) | No minimum (620 typical) | Eligible veterans |
| Conventional (1 unit) | 15-20% | SFR, condo | No | 620+ (680 preferred) | W-2 investors, first rentals |
| Conventional (2-4 units) | 25% | Duplex-fourplex | No | 680+ | Small multifamily investors |
| DSCR Loan | 15-25% | 1-4 units | No | 640+ | Self-employed, scaling investors |
| Hard Money | 10-35% | Any residential | No | Flexible | Fix-and-flip, BRRRR |
| Commercial | 25-30% | 5+ units, mixed-use | No | 660+ | Larger multifamily |
| Portfolio / Community Bank | 20-30% | Any | No | Flexible | Unique properties, relationships |
Notice the investment property down payment range: 0% (VA) to 30% (commercial). On a $400,000 property, that is the difference between $0 and $120,000 in cash at closing. The loan type you choose determines how fast you can scale. Let me walk through each one in detail.
FHA House Hack: 3.5% Down on a Rental Property
The FHA loan is the lowest investment property down payment option available to most buyers. You can purchase a 1-4 unit property with just 3.5% down — but you must live in one of the units for at least 12 months.
How FHA House Hacking Works
Buy a fourplex for $400,000 with 3.5% down ($14,000). Move into one unit. Rent the other three. After 12 months, you can move out and keep the property as a pure investment. Your tenants are effectively paying your mortgage while you live rent-free or close to it.
I did this with my second property — a fourplex in Indianapolis. Down payment: $14,000. Three units rented at $850 each ($2,550/month). My PITIA was $2,900/month. I paid $350 out of pocket for housing. In my previous apartment, I was paying $1,200/month. The fourplex saved me $850/month in living costs while building equity in a $400,000 asset.
The catch: FHA loans come with mortgage insurance premium (MIP) of about 0.85% annually for the life of the loan. On a $386,000 loan (96.5% of $400,000), that adds $273/month. Factor this into your DSCR calculation to make sure the deal still works.
After 12 months of owner-occupancy, you have a rental property with only $14,000 invested. Your effective LTV is 96.5%, which means maximum leverage from day one. Read our full house hacking guide for the complete strategy.
FHA Down Payment Sources
FHA allows down payment assistance from multiple sources that conventional loans often restrict:
- Gift funds: 100% of the down payment can come from family members, employers, or charitable organizations
- Down payment assistance programs: Many state and local governments offer grants or forgivable loans for FHA buyers
- Seller concessions: The seller can contribute up to 6% of the purchase price toward your closing costs (not the down payment itself, but this frees up your cash)
In theory, you could buy a $400,000 fourplex with zero of your own money if you stack gift funds with seller concessions. I have seen it done twice — both times by investors who planned the house hack months in advance and lined up family gift letters before starting the property search.
VA Loan: 0% Down (For Eligible Veterans)
If you have VA loan eligibility, you can purchase a 1-4 unit property with zero down payment — the lowest possible investment property down payment. No mortgage insurance. No monthly PMI or MIP. The VA funding fee (1.25-3.3% of the loan amount) can be rolled into the loan, so your actual cash at closing can be limited to inspection and appraisal costs.
The same owner-occupancy requirement applies: you must live in one unit. But the VA is more flexible than FHA on the timeline — there is no hard 12-month rule, though you need to establish it as your primary residence with genuine intent.
On a $500,000 property, the difference between VA (0% down) and conventional investment (25% down) is $125,000 in capital preserved. That $125,000 could fund two or three additional properties through other loan programs. Veterans who understand this advantage can build portfolios faster than almost anyone else in real estate.
Conventional Loans: 15-25% Down
The standard investment property down payment for conventional financing is 20% on single-family and 25% on 2-4 unit properties. Some lenders go as low as 15% on single-family investment properties, but expect a rate premium of 0.25-0.50% and mandatory private mortgage insurance (PMI).
Single-Family Investment: 15-20% Down
On a $350,000 single-family rental:
- 15% down: $52,500 cash + PMI (~$150-$250/month until you reach 20% equity)
- 20% down: $70,000 cash, no PMI
The $17,500 difference between 15% and 20% down saves you cash today but adds $150-$250/month in PMI. Over the 3-5 years it typically takes to reach 20% equity through appreciation and principal paydown, that PMI costs $5,400-$15,000 total. Run both scenarios in the rental property calculator to see which structure produces better cash-on-cash returns for your specific deal.
Multifamily (2-4 Units): 25% Down
Fannie Mae’s eligibility matrix requires 25% down on 2-4 unit investment properties. On a $500,000 triplex, that is $125,000 — a significant capital commitment. This is why many investors start with house hacking (FHA at 3.5%) and transition to conventional financing for subsequent properties.
The 25% down payment also means your LTV is 75%, which typically qualifies you for the best conventional rates — 0.25-0.50% lower than what you would get at 80% LTV. That rate savings can offset the higher capital requirement over the life of the loan.
DSCR Loans: 15-25% Down (No Income Docs)
DSCR loans qualify you based on the property’s rental income, not your personal income. The investment property down payment typically ranges from 20-25%, though some lenders offer 15% down programs with higher rates.
DSCR Down Payment Tiers
| Down Payment | Typical Rate (2026) | DSCR Requirement | Reserve Requirement |
|---|---|---|---|
| 15% ($52,500 on $350K) | 8.50-9.25% | 1.25+ DSCR | 12-18 months PITIA |
| 20% ($70,000 on $350K) | 7.50-8.00% | 1.0+ DSCR | 6-12 months PITIA |
| 25% ($87,500 on $350K) | 7.00-7.50% | 0.75+ DSCR (some lenders) | 6 months PITIA |
Notice how the rate drops significantly between 15% and 25% down — roughly 1.5 percentage points. On a $280,000 loan, that is $4,200 per year in interest savings, or $350/month. Use the DSCR calculator to see exactly how your property’s income covers the debt at each down payment level. For current rates across all tiers, check our DSCR loan rates guide.
Hard Money and Bridge Loans: 10-35% Down
Hard money lenders calculate down payment differently. Instead of a percentage of purchase price, they think in terms of loan-to-value (LTV) or loan-to-ARV. Your effective investment property down payment depends on how the lender structures the deal.
Purchase Price Basis
A hard money lender offering 70% LTV on a $250,000 purchase requires 30% down ($75,000). Add origination points (2-3%) and you need roughly $82,500 in cash at closing.
ARV Basis
The same property with an ARV of $380,000 and a lender offering 80% of ARV gets a $304,000 loan — more than the purchase price. In this scenario, your “down payment” might be zero on the acquisition, but you need cash for the portion of rehab costs the loan does not cover. Calculate the full picture with the hard money loan calculator and check total costs in our hard money loan cost guide.
How to Reduce Your Investment Property Down Payment
If the standard 20-25% down payment is blocking your next acquisition, here are seven strategies I have used or seen other investors use to get into deals with less capital.
1. House Hack with FHA or VA
Already covered above, but it bears repeating: living in one unit of a 2-4 unit property drops your investment property down payment from 25% to 3.5% (FHA) or 0% (VA). On a $400,000 property, that is $86,000-$100,000 in capital preserved. This is the single most impactful strategy for new investors.
2. Seller Financing
In a seller financing arrangement, the property owner acts as the lender. Down payment terms are negotiable — I have seen deals close at 5-10% down with seller financing, compared to 20-25% with institutional lenders. The tradeoff is usually a higher interest rate (7-10%) and a shorter term (5-10 years with a balloon payment).
Seller financing works best with motivated sellers who own the property free and clear — no existing mortgage means no due-on-sale clause complications. Look for older landlords who want steady income without management responsibilities.
3. Assume an Existing Mortgage
FHA and VA loans are assumable. If a seller has an FHA loan at 3.5% interest from 2021, you can assume that loan at the original rate and terms. Your “down payment” is the difference between the purchase price and the remaining loan balance. On a property bought for $300,000 in 2021 with $270,000 remaining balance, selling for $350,000 today, your down payment would be $80,000 — but you get a 3.5% interest rate that is impossible to find in 2026’s market.
4. Partner with Another Investor
Split the investment property down payment with a partner. One investor brings capital, the other brings deal-finding and management skills. On a $400,000 property with 25% down ($100,000), each partner contributes $50,000. Structure the partnership with a clear operating agreement that defines equity splits, management responsibilities, and exit procedures.
5. Use a HELOC on Your Primary Residence
If you have equity in your home, a home equity line of credit (HELOC) can fund your investment property down payment. Typical HELOC rates in 2026 are 8-9%, but the interest may be deductible if the funds are used for investment purposes (consult your CPA). On a home with $150,000 in equity, an 80% HELOC gives you $120,000 in available capital — enough for 25% down on a $480,000 investment property.
The risk: you are leveraging your primary residence to buy a rental property. If the rental goes badly, you have two properties at risk instead of one. Only use this strategy if you have strong reserves and the rental numbers are solid. Check your numbers with the rental property calculator before tapping your HELOC.
6. Negotiate Below-Market Purchase Price
Buying 10-15% below market value effectively reduces your down payment requirement in terms of capital at risk. Purchase a $400,000 property for $340,000, put 25% down ($85,000), and your day-one equity is $115,000 ($400,000 value – $255,000 loan). You committed $85,000 but have $115,000 in equity — a built-in cushion. Find below-market deals through direct mail, driving for dollars, and off-market networks.
7. BRRRR Strategy (Recycle Your Down Payment)
The BRRRR strategy — Buy, Rehab, Rent, Refinance, Repeat — lets you recycle the same down payment across multiple properties. Buy a distressed property with hard money (10-30% down), rehab it, rent it, then refinance into a long-term loan based on the higher after-repair value. If the ARV supports it, you pull out most or all of your original cash and redeploy it into the next deal.
I have completed four BRRRR cycles where I recovered 90-100% of my initial capital on the refinance. That means I effectively paid $0 in permanent down payment — the same $80,000 funded four different acquisitions over 18 months. Use the ARV calculator to verify your after-repair value before committing to a BRRRR deal.
Worked Example: Same Property, Four Down Payment Strategies
Let me show you how four different financing structures affect the same $400,000 duplex with $3,200/month total rental income.
| Strategy | Down Payment | Cash at Closing | Monthly Payment | Monthly Cash Flow | Cash-on-Cash Return |
|---|---|---|---|---|---|
| FHA House Hack (3.5%) | $14,000 | $22,000 | $3,150 (incl MIP) | $50 (renting 1 unit at $1,600) | 2.7% |
| Conventional (25%) | $100,000 | $112,000 | $2,240 | $320 | 3.4% |
| DSCR (20%) | $80,000 | $92,000 | $2,520 | $40 | 0.5% |
| Seller Finance (10%) | $40,000 | $46,000 | $2,780 (8%, 25-yr) | -$220 | -5.7% |
The FHA house hack requires $22,000 total cash and produces marginal positive cash flow while you live in one unit. Once you move out and rent all four sides of the duplex, cash flow jumps to $1,650/month (if you refinance out of FHA later). The conventional option requires 5x more capital but generates reliable cash flow from day one. The DSCR loan is a middle ground — less capital than conventional but higher rate eats the cash flow. Seller financing at 10% down preserves the most capital but the 8% rate makes it cash-flow negative.
Model your own deal with different down payment amounts using the investment property mortgage calculator to find the sweet spot between capital preservation and cash flow.
How Much Cash Do You Actually Need Beyond the Down Payment?
Your investment property down payment is not the only cash you need at closing. Budget for these additional costs:
| Cost | Typical Range | On a $400K Property |
|---|---|---|
| Closing costs | 2-5% of purchase price | $8,000-$20,000 |
| Inspection | $300-$600 | $400 |
| Appraisal | $400-$800 | $500 |
| Prepaid insurance (12 months) | $1,200-$3,000 | $2,000 |
| Prepaid taxes (2-6 months) | $1,500-$5,000 | $2,100 |
| Cash reserves (6-12 months PITIA) | $15,000-$35,000 | $16,800-$33,600 |
On a $400,000 investment property with 20% down ($80,000), your total cash requirement is roughly $105,000-$140,000 when you include closing costs, prepaids, and lender-required reserves. The down payment is only 57-76% of the total capital needed. Use the closing costs calculator to get a precise estimate for your state and purchase price.
Down Payment vs Cash Flow: Finding the Right Balance
More money down means lower monthly payments, better interest rates, and higher cash flow. Less money down means you preserve capital for additional investments but accept thinner margins. Which approach is right depends on your strategy.
Maximize down payment when:
- You want strong monthly cash flow from day one
- You are buying in a tight market where rents barely cover expenses at lower down payments
- You plan to hold long-term and want the lowest possible carrying cost
- You have limited income to cover negative cash flow months
Minimize down payment when:
- You are scaling quickly and want to acquire multiple properties
- The property cash flows comfortably even at higher leverage
- You have a concrete plan to deploy the preserved capital into additional deals
- You are comfortable with the risk of thinner margins and higher debt
There is no universally correct answer. A property in Memphis at $180,000 might cash flow beautifully at 15% down. The same leverage on a $600,000 property in Austin might produce negative cash flow. Always run the specific numbers through the rental property calculator before deciding how much to put down.
Investment Property Down Payment by State: What Changes?
Down payment percentages do not change by state — federal lending guidelines from CFPB set uniform minimums nationwide. However, the dollar amount varies dramatically because property prices differ by market.
Here is what 20% down looks like across different markets:
| Market | Median Investment Property Price | 20% Down Payment | 25% Down Payment |
|---|---|---|---|
| Indianapolis, IN | $210,000 | $42,000 | $52,500 |
| Memphis, TN | $185,000 | $37,000 | $46,250 |
| Columbus, OH | $240,000 | $48,000 | $60,000 |
| Charlotte, NC | $320,000 | $64,000 | $80,000 |
| Austin, TX | $420,000 | $84,000 | $105,000 |
| Miami, FL | $480,000 | $96,000 | $120,000 |
| San Francisco, CA | $950,000 | $190,000 | $237,500 |
The same 20% down payment buys you a rental property in Memphis ($37,000) or a parking spot in San Francisco ($190,000). This is why I encourage investors with limited capital to look beyond their local market. A $50,000 budget can acquire a cash-flowing rental in several Midwest and Southeast markets. Check our analysis of best cities for real estate investment in 2026 for market-specific data.
Common Down Payment Mistakes
I have made most of these mistakes personally or watched investors in my network make them. Each one either cost thousands of dollars or delayed portfolio growth by months.
Putting all your cash into the down payment. You need reserves after closing — for vacancy, repairs, and carrying costs during tenant turnover. An investor who puts $100,000 down on a rental and has $3,000 left in the bank is one water heater failure away from financial stress. Keep 6-12 months of PITIA in reserves after closing, minimum.
Not comparing loan programs. I have watched investors automatically go conventional at 25% down without checking if they qualify for a DSCR loan at 20% down or if house hacking at 3.5% makes sense for their situation. Spend two hours talking to three different lenders before committing to a financing structure. The savings can be tens of thousands of dollars.
Ignoring the rate impact of lower down payment. Putting 15% down instead of 25% saves $35,000 upfront on a $350,000 property. But the higher rate and PMI might cost $3,000-$5,000 per year. Over a 7-year hold, the “savings” from a lower down payment actually cost you more than they saved. Check the full picture in the LTV investment property requirements guide.
Saving for years instead of starting with less down. An investor who spends three years saving $100,000 for a conventional down payment misses three years of appreciation, rent collection, and principal paydown. Starting sooner with an FHA house hack at $14,000 down — even with mortgage insurance — is mathematically superior in almost every scenario I have modeled. Time in the market beats timing the market, and that applies to real estate as much as stocks.
Using retirement funds without understanding the penalties. Withdrawing from a 401(k) or IRA to fund an investment property down payment triggers income tax plus a 10% penalty if you are under 59½. On a $100,000 withdrawal, that could be $30,000-$40,000 in taxes and penalties. A self-directed IRA can hold real estate, but the rules are complex and violations result in the entire account being treated as a distribution. Talk to a CPA specializing in real estate before touching retirement accounts.
Down Payment Tax Implications
Your investment property down payment is not directly tax-deductible — it is a capital investment, not an expense. However, it affects your tax situation in several ways:
- Depreciation basis: Your depreciable basis is the purchase price minus land value, regardless of down payment. A $400,000 property with $100,000 land value gives you $300,000 in depreciable basis whether you put 3.5% down or 25% down. Run the numbers through a depreciation calculator to see annual deductions.
- Mortgage interest deduction: Higher leverage (lower down payment) means a larger loan and more deductible interest. At 80% LTV on $400,000, you deduct interest on $320,000. At 75% LTV, you deduct on $300,000. The extra $20,000 in loan balance generates roughly $1,400-$1,600 in additional interest deductions per year.
- Capital gains: When you sell, your gain is calculated from your purchase price, not your down payment. But the down payment determines how much cash you get from the sale. See our rental property tax deductions guide for the complete picture.
Related Calculators
Run your numbers with these free real estate investment calculators:
- ARV Calculator — estimate after-repair value from comparable sales
- Rental Property Calculator — full deal analysis with cash flow projections
- Cash-on-Cash Calculator — measure your return on invested capital
- Cash Flow Calculator — monthly and annual cash flow breakdown
- DSCR Calculator — check if your property qualifies for a DSCR loan
- Fix and Flip Calculator — project profit, holding costs, and ROI
- Capital Gains Tax Calculator — estimate taxes when you sell
- Cap Rate Calculator — compare properties by capitalization rate
Frequently Asked Questions
How much is a down payment on an investment property?
The standard investment property down payment is 20-25% for conventional loans — $60,000-$75,000 on a $300,000 property. However, you can pay as little as 3.5% down (FHA) or 0% down (VA) if you live in one unit of a 2-4 unit property. DSCR loans require 15-25% down depending on the lender and your credit score. Hard money lenders typically want 10-35% down depending on whether they calculate based on purchase price or after-repair value. Use the investment property mortgage calculator to see how different down payment amounts affect your monthly cash flow.
Can I buy an investment property with 10% down?
Not through conventional or DSCR loans for non-owner-occupied properties — minimum is typically 15-20%. However, you can achieve effective 10% down through seller financing (negotiable terms), some portfolio lenders with strong banking relationships, or hard money loans on value-add deals where the lender uses ARV-based calculations. The most reliable path to low down payment is FHA house hacking at 3.5% down, which requires living in one unit for 12 months.
Is it better to put 20% or 25% down on a rental property?
For single-family investment properties, 20% is typically sufficient and gives you a good balance between cash preservation and rate pricing. For 2-4 unit properties, conventional lenders require 25% minimum. Even on single-family, going from 20% to 25% down often drops your rate by 0.25% and eliminates any PMI — saving $100-$200/month. Over 10 years, that is $12,000-$24,000 saved. Model both scenarios in the rental property calculator to compare cash-on-cash returns at each level.
What credit score do I need for the lowest down payment?
FHA loans (3.5% down) require a minimum 580 credit score. Below 580 and down to 500, FHA requires 10% down. Conventional investment property loans require 620 minimum (most lenders want 680+) for 15-20% down. DSCR loans typically need 640+ for 20% down programs and 720+ for 15% down. Higher credit scores do not reduce minimum down payment requirements, but they do significantly improve your interest rate, which affects monthly cash flow more than most investors realize.
Can I use a HELOC for an investment property down payment?
Yes. A HELOC on your primary residence can fund all or part of an investment property down payment. The HELOC interest may be tax-deductible if the funds are used for investment purposes (consult your CPA). However, some lenders will count the HELOC payment in your debt-to-income ratio, which could affect qualification. Also, you are pledging your primary residence as collateral for an investment — if the rental property fails to perform, you have two properties at risk. Only use this strategy with strong cash reserves and conservative rental projections.
Start With the Numbers, Not the Strategy
The best investment property down payment approach is the one that matches your capital, your risk tolerance, and the specific deal you are evaluating. Do not choose a financing structure because it sounds clever — choose it because you ran the numbers and it produces the returns you need at a risk level you can handle.
Start here: open the investment property mortgage calculator, enter a real property you are considering, and model three scenarios — minimum down payment, 20% down, and 25% down. Compare the monthly cash flow, cash-on-cash return, and total interest paid. Then check your DSCR at each level to make sure the deal qualifies with the lender you plan to use.
The difference between an investor who buys one property every two years and one who buys three properties every year is rarely income or market timing. It is down payment strategy — understanding which loan programs exist, which structures fit your situation, and how to deploy your capital across multiple deals instead of concentrating it all in one.
Leave a Reply